


 |
市場調查報告書
商品編碼
2125552
越南資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Vietnam ICT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
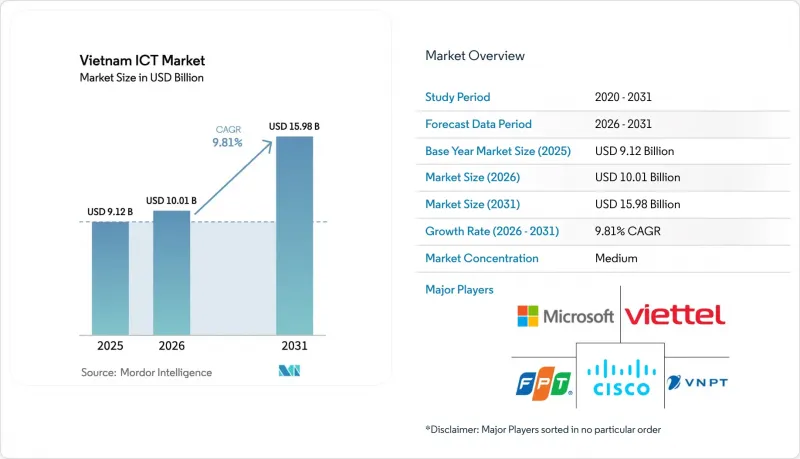
據 Mordor Intelligence 稱,越南 ICT 市場在 2025 年的價值為 91.2 億美元,預計到 2031 年將從 2026 年的 100.1 億美元成長到 159.8 億美元,在預測期(2026-2031 年)成長到 159.8 億美元,在預測期(2026-2031 年)內的複合年成長率為 9.81%。
本報告按類型(IT硬體、IT軟體、IT服務、 IT基礎設施、電信服務)、最終用戶公司規模(中小企業、大型企業)和最終用戶行業(政府/公共管理部門、銀行、金融服務和保險、能源和公用事業、零售、電子商務和物流、其他)進行分類。市場預測以美元計價。
越南資訊通訊技術市場的趨勢與洞察
智慧城市基礎建設計劃
政府批准的48項市政數位化藍圖圖為連接、感測器網路和網路安全平台創造了20億美元的投資管道。胡志明市防洪系統的升級和峴港市永續城市規劃都需要即時數據分析,推動了對邊緣運算和物聯網閘道的需求。強制要求公共部門IT預算至少10%用於網路安全的措施,進一步擴大了威脅偵測供應商的目標市場。全國數位身分識別系統「VNeID」的部署已惠及數百萬公民,並擴展了電子政府入口網站的身份驗證服務。這些項目正在為電信業者、雲端服務供應商和系統整合商帶來連鎖效應,同時也將越南打造成為區域智慧城市解決方案的試驗場。
工業4.0價值鏈中的數位轉型
已實施人工智慧預測維修系統的製造工廠報告稱,生產效率提高了30%至50%。紡織品出口企業Vinatex在實施基於物聯網的供應鏈分析後,其合併銷售額成長了6.1%。三星9.2億美元的擴張投資表明,越來越多的資金正流入基於機器學習的品管和自動化物流領域。第109號法令降低了國產車輛的註冊稅,透過機器人技術和連網工廠平台加速了汽車產業的數位轉型。基於區塊鏈的溯源追蹤和人工智慧驅動的需求預測,正幫助越南製造商縮短產品上市時間,並獲得高利潤的全球訂單。
建置網路資料中心的初始投資成本很高
5G頻段、光纖回程傳輸和三級資料中心建設的資本密集特性,正給電信業者的財務狀況帶來壓力,尤其是在兩個大都會圈以外的地區。在區域性城市,需求密度往往不足以達到利用率閾值,導致投資者的投資回收期延長。外匯波動和利率上升推高了資金籌措成本,而土地使用許可的核准流程也存在行政延誤。儘管公私合營(PPP)模式正在興起,但小規模區域電信業者和中立的基地台營運商仍面臨資金籌措。這些限制因素可能會延緩區域寬頻部署進度,進而限制許多工業4.0應用場景所需的邊緣運算覆蓋範圍。
細分市場分析
2025年,隨著電信業者升級基地台和資料中心設備以支援全國5G骨幹網路建設,IT硬體在越南ICT市場仍佔22.88%的佔有率。然而,隨著基礎建設日趨成熟,預計越南ICT市場硬體市場規模的成長速度將低於服務業。相較之下,受諮詢、系統整合和需要專業知識的安全管理專案等驅動的IT服務業,預計到2031年將以12.07%的複合年成長率成長。混合雲端、ERP現代化和人工智慧實施都需要持續的專業服務支持,這為供應商和整合商提供了穩定的收入來源。
隨著企業尋求透過計量收費模式擴充性,雲端服務的採用正在加速,這反過來又推動了對電信營運商提供的捆綁式連接和保全服務的需求。隨著企業從永久授權轉向基於訂閱的SaaS模式,軟體銷售額也在成長,從而降低了前期成本。通訊服務受惠於行動數據消費的成長和5G在企業中日益普及。託管服務契約,特別是網路安全監控服務,使中小企業能夠外包複雜任務,並以最少的人員滿足監管要求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 智慧城市基礎建設計劃
- 工業4.0價值鏈中的數位轉型
- 對雲端運算和人工智慧相關技術的資本投資正在激增。
- 政府的「越南製造」數位經濟藍圖
- 半導體自給自足的獎勵
- 超大規模區域IDC中心擴展
- 市場限制因素
- 網路資料中心的初始建置成本很高。
- 資訊與通訊技術專業人才短缺
- 過度依賴關鍵零件進口
- 應對分散的網路法規的負擔
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 重大技術投資
- 雲端技術
- 人工智慧
- 網路安全
- 數位服務
- 邊緣運算和物聯網
- 重大技術投資
- 波特五力分析
- 生態系分析
- 產業相關人員分析
- 新冠疫情的影響與復甦,以及宏觀經濟的轉型
第5章 市場規模與成長預測
- 按類型
- IT硬體
- 電腦硬體
- 網路裝置
- 周邊設備
- IT軟體
- IT服務
- 託管服務
- 業務流程服務
- 商業諮詢服務
- 雲端服務
- IT基礎設施
- 通訊服務
- IT硬體
- 按最終用戶公司規模分類
- 小型企業
- 大公司
- 按行業分類的最終用戶
- 政府/公共行政
- BFSI
- 能源公用事業
- 零售、電子商務、物流
- 製造業和工業4.0
- 醫療保健和生命科學
- 石油和天然氣(上游、中游、下游)
- 遊戲和電子競技
- 其他行業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- Cisco Systems Inc.
- Viettel Group
- VNPT Group
- FPT Corporation
- CMC Corporation
- Qualcomm Technologies Inc.
- Google LLC(Alphabet Inc.)
- Fujitsu Ltd.
- Fortinet Inc.
- Vietnamobile
- D-Link Systems Inc.
- Hewlett Packard Enterprise
- Telehouse Vietnam
- Oracle Corporation
- IBM Corporation
- Samsung Electronics Vietnam
- VNG Corporation
- MobiFone
- TMA Solutions
- KMS Technology
- NashTech
- Axon Active Vietnam
- Ciena Corporation
- Ericsson Vietnam
第7章 市場機會與未來展望
According to Mordor Intelligence, the Vietnam ICT market size was valued at USD 9.12 billion in 2025 and estimated to grow from USD 10.01 billion in 2026 to reach USD 15.98 billion by 2031, at a CAGR of 9.81% during the forecast period (2026-2031).
This report is Segmented by Type (IT Hardware, IT Software, IT Services, IT Infrastructure, Communication Services), End-User Enterprise Size (Small and Medium Enterprises, Large Enterprises), End-User Industry Vertical (Government and Public Administration, BFSI, Energy and Utilities, Retail, E-Commerce and Logistics, and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam ICT Market Trends and Insights
Smart-City Infrastructure Programs
Government approval of 48 municipal digitalization roadmaps has created a USD 2 billion pipeline for connectivity, sensor networks, and cybersecurity platforms. Ho Chi Minh City's flood-management upgrade and Da Nang's sustainable-city plan both require real-time data analytics, strengthening demand for edge computing and IoT gateways. Mandatory allocation of at least 10% of public-sector IT budgets to cybersecurity further expands the addressable market for threat-detection vendors. The national VNeID digital-identity roll-out already serves millions of citizens and is scaling authentication services for e-government portals. These projects generate multiplier effects for telecom carriers, cloud providers, and systems integrators while positioning Vietnam as a testbed for regional smart-city solutions.
Digital Transformation Across Industry 4.0 Value Chains
Manufacturing plants adopting AI-driven predictive-maintenance systems report production-efficiency gains of 30-50%. Textile exporters such as Vinatex have boosted consolidated revenue by 6.1% after deploying IoT-enabled supply-chain analytics. Samsung's USD 920 million expansion underscores rising capital inflows devoted to machine-learning-based quality control and automated logistics. Decree 109, which lowered registration taxes for locally produced vehicles, has accelerated automotive digitalization through robotics and connected-factory platforms. Blockchain-powered provenance tracking and AI-enhanced demand forecasting are helping Vietnamese manufacturers capture higher-margin global orders while shortening time-to-market.
High Up-Front Network and Data-Center Build Costs
The capital intensity of 5G spectrum, fiber backhaul, and Tier III data-center construction strains operator balance sheets, especially outside the two largest metros. Secondary cities often lack the demand density to hit utilization thresholds, extending payback periods for investors. Currency fluctuation risk and rising interest rates elevate funding costs, while land-use approvals add administrative delays. Although public-private-partnership models are emerging, financing gaps persist for small regional carriers and neutral-host tower companies. These constraints could defer rural broadband timelines and limit edge-computing coverage that many Industry 4.0 use cases require.
Other drivers and restraints analyzed in the detailed report include:
- Surging Cloud- and AI-Linked Capex
- "Make-in-Vietnam" Digital-Economy Roadmap
- Shortage of Specialized ICT Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IT Hardware maintained a 22.88% share of the Vietnam ICT market in 2025 as operators upgraded base-station and data-center equipment to support nationwide 5G backbones. However, the Vietnam ICT market size for hardware is expected to expand more slowly than that for services as infrastructure build-outs mature. In contrast, IT Services is on track for a 12.07% CAGR through 2031, propelled by consulting, systems integration, and managed-security projects that require specialized know-how. Hybrid cloud, ERP modernization, and AI implementation demand continuous professional-services support, creating sticky revenue streams for vendors and integrators.
Cloud-services adoption is escalating as enterprises pursue pay-as-you-go scalability; this, in turn, lifts demand for connectivity and cybersecurity offerings bundled by telecom carriers. Software revenue is also climbing as firms migrate from perpetual licenses to subscription-based SaaS, lowering up-front costs. Communication services benefit from growing mobile-data consumption and enterprise 5G use cases. Managed-services contracts, especially for cybersecurity monitoring, allow SMEs to outsource complex functions and keep headcount lean while meeting regulatory mandates.
Complete Report Scope:
- By Type
- IT Hardware
- Computer Hardware
- Networking Equipment
- Peripherals
- IT Software
- IT Services
- Managed Services
- Business Process Services
- Business Consulting Services
- Cloud Services
- IT Infrastructure
- Communication Services
- IT Hardware
- By End-User Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-user Industry Vertical
- Government and Public Administration
- BFSI
- Energy and Utilities
- Retail, E-commerce and Logistics
- Manufacturing and Industry 4.0
- Healthcare and Life Sciences
- Oil and Gas (Up-, Mid-, Down-stream)
- Gaming and Esports
- Other Verticals
- By Industry Vertical (Value)
List of Companies Covered in this Report:
- Microsoft Corporation
- Cisco Systems Inc.
- Viettel Group
- VNPT Group
- FPT Corporation
- CMC Corporation
- Qualcomm Technologies Inc.
- Google LLC (Alphabet Inc.)
- Fujitsu Ltd.
- Fortinet Inc.
- Vietnamobile
- D-Link Systems Inc.
- Hewlett Packard Enterprise
- Telehouse Vietnam
- Oracle Corporation
- IBM Corporation
- Samsung Electronics Vietnam
- VNG Corporation
- MobiFone
- TMA Solutions
- KMS Technology
- NashTech
- Axon Active Vietnam
- Ciena Corporation
- Ericsson Vietnam
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Smart-city infrastructure programmes
- 4.2.2 Digital transformation across Industry 4.0 value-chains
- 4.2.3 Surging cloud- and AI-linked capex
- 4.2.4 Government "Make-in-Vietnam" digital-economy roadmap
- 4.2.5 Semiconductor self-sufficiency incentives
- 4.2.6 Hyperscale and regional IDC hub build-out
- 4.3 Market Restraints
- 4.3.1 High up-front network and data-centre build costs
- 4.3.2 Shortage of specialised ICT talent
- 4.3.3 Heavy reliance on imported core components
- 4.3.4 Fragmented cyber-regulatory compliance burden
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.6.1 Key Technology Investments
- 4.6.1.1 Cloud Technology
- 4.6.1.2 Artificial Intelligence
- 4.6.1.3 Cyber-security
- 4.6.1.4 Digital Services
- 4.6.1.5 Edge Computing and IoT
- 4.6.1 Key Technology Investments
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Ecosystem Analysis
- 4.9 Industry Stakeholder Analysis
- 4.10 Impact and Recovery from COVID-19 and Macro Shifts
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 IT Hardware
- 5.1.1.1 Computer Hardware
- 5.1.1.2 Networking Equipment
- 5.1.1.3 Peripherals
- 5.1.2 IT Software
- 5.1.3 IT Services
- 5.1.3.1 Managed Services
- 5.1.3.2 Business Process Services
- 5.1.3.3 Business Consulting Services
- 5.1.3.4 Cloud Services
- 5.1.4 IT Infrastructure
- 5.1.5 Communication Services
- 5.1.1 IT Hardware
- 5.2 By End-User Enterprise Size
- 5.2.1 Small and Medium Enterprises
- 5.2.2 Large Enterprises
- 5.3 By End-user Industry Vertical
- 5.3.1 Government and Public Administration
- 5.3.2 BFSI
- 5.3.3 Energy and Utilities
- 5.3.4 Retail, E-commerce and Logistics
- 5.3.5 Manufacturing and Industry 4.0
- 5.3.6 Healthcare and Life Sciences
- 5.3.7 Oil and Gas (Up-, Mid-, Down-stream)
- 5.3.8 Gaming and Esports
- 5.3.9 Other Verticals
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Cisco Systems Inc.
- 6.4.3 Viettel Group
- 6.4.4 VNPT Group
- 6.4.5 FPT Corporation
- 6.4.6 CMC Corporation
- 6.4.7 Qualcomm Technologies Inc.
- 6.4.8 Google LLC (Alphabet Inc.)
- 6.4.9 Fujitsu Ltd.
- 6.4.10 Fortinet Inc.
- 6.4.11 Vietnamobile
- 6.4.12 D-Link Systems Inc.
- 6.4.13 Hewlett Packard Enterprise
- 6.4.14 Telehouse Vietnam
- 6.4.15 Oracle Corporation
- 6.4.16 IBM Corporation
- 6.4.17 Samsung Electronics Vietnam
- 6.4.18 VNG Corporation
- 6.4.19 MobiFone
- 6.4.20 TMA Solutions
- 6.4.21 KMS Technology
- 6.4.22 NashTech
- 6.4.23 Axon Active Vietnam
- 6.4.24 Ciena Corporation
- 6.4.25 Ericsson Vietnam
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 中東和北非資訊通訊技術(ICT):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)中國資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)日本資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)西班牙資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)新加坡資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲資訊通訊技術:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)法國資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)美國資訊通訊技術:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)