


 |
市場調查報告書
商品編碼
2116739
歐洲資訊通訊技術:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Europe ICT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
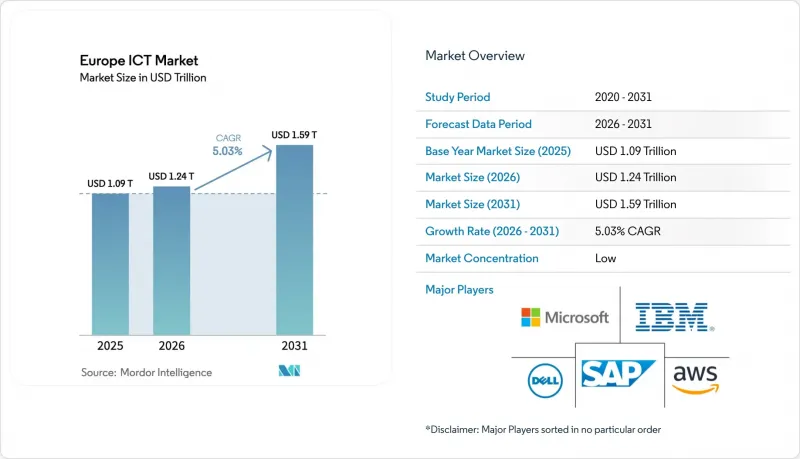
根據 Mordor Intelligence 預測,歐洲 ICT 市場規模將從 2025 年的 1.09 兆美元成長到 2026 年的 1.24 兆美元,到 2031 年達到 1.59 兆美元,預計 2026 年至 2031 年的複合年成長率為 5.03%。
本報告按產品類型(IT硬體、IT軟體、IT服務、 IT基礎設施、 IT安全與網路安全、通訊服務)、公司規模(中小企業、大型企業)、最終用戶產業(銀行、金融服務和保險業、政府及公共部門、製造業及工業、醫療保健業、其他)和地區進行細分。市場預測以美元計價。
歐洲資訊通訊技術市場的趨勢與洞察
歐盟「數位十年」(2021 年至 2030 年)的資金投入加速,將促進雲端運算和 5G 的部署。
大規模公共資金正在加速網路基礎設施建設進程。到2025年12月,成員國將累計投資580億歐元用於改善Gigabit連接和遍遠地區5G覆蓋,從而縮短了此前需持續到2020年代末的專案週期。光是沃達豐德國一家公司到2025年就將投入營運15,000個5G獨立組網基地台,為車用通訊系統和遠端手術等領域的網路切片技術鋪路。針對中小企業的轉型支援措施,涵蓋高達一半的雲端採用成本,正在運作平台供應商的潛在基本客群,預計到2025年,中小企業的雲端採用率將比上一年成長34%。然而,由於國家援助審查導致資金籌措延遲到位,義大利和西班牙的結算工作也因此受到影響,凸顯了歐盟內部實施過程中存在的風險。
Schrems II 裁決後,主權雲端資料位置要求激增。
歐盟-美國隱私權保護協議的失效引發了工作負載大規模回流至其本國的趨勢。 2025年,近三分之二的歐洲大型企業已將敏感資料遷移至歐盟境內的服務供應商或企業內部環境。 OVHcloud 的收入在公共部門訂單的推動下實現了兩位數成長,而德國電信則與多家大型超大規模資料中心業者運營商合作,構建了一個符合德國聯邦法規的基於 Kubernetes 的主權雲平台。託管服務提供者也紛紛效仿,在法蘭克福、阿姆斯特丹和巴黎擴建低延遲資料中心,以滿足金融和公共部門使用者對嚴格管轄權控制的需求。儘管由於法律審查成本飆升,資料遷移週期仍然較長,但整體趨勢仍然有利於那些在資料主權方面擁有良好記錄的服務提供者。
資料中心電力消耗量,正面臨電價飆漲和碳排放稅。
到2025年,資料中心電力需求將達到104兆瓦時,其中法蘭克福、阿姆斯特丹和都柏林三大資料中心將佔近三分之二的用電量。將於2026年1月生效的每噸90歐元的碳排放權價格,已使可再生能源設施的營運成本上漲了兩位數百分比。各國採取的干預措施進一步加劇了這種壓力。愛爾蘭暫停向都柏林資料中心新增併網,荷蘭對大型設施徵收能源稅,迫使營運商要么將額外容量分配給北歐市場,要么將資料中心選址在可再生能源發電發電廠附近。在德國,超過10兆瓦的新建資料中心必須參與需量反應計劃,迫使資料中心重新設計架構,並加速採用電池供電的微電網。
細分市場分析
受涵蓋18個關鍵產業的NIS2指令中24小時事件報告要求的推動, IT安全和網路安全市場預計將以7.26%的複合年成長率成長。識別及存取管理市場成長尤為強勁,這反映了歐盟範圍內的零信任要求,該要求強制銀行和公共服務部門採用多因素身份驗證。隨著企業實現合規性檢查的自動化,對雲端安全態勢管理工具的需求不斷成長;同時,由於主要作業系統供應商提供的捆綁式產品,終端保護領域的定價正在下降。在歐洲ICT市場,IT服務仍然是最大的市場,但由於具有豐富自動化功能的平台的出現,傳統諮詢服務正在萎縮。隨著混合辦公模式的日益普及,硬體更換週期持續延長,對桌上型電腦和筆記型電腦的需求正在下降。通訊服務收入依然強勁,這得益於供應商整合以及整合通訊捆綁包的推出,這些捆綁包降低了分散式員工的整體擁有成本(TCO)。基礎設施支出正在轉向邊緣設備,這在一定程度上抵消了對大規模本地伺服器需求的下降。
第二代安全控制技術結合了威脅情報源和機器學習分析,其應用範圍正從關鍵基礎設施擴展到中型企業用戶,顯示其基本客群正在不斷成長。網路安全方面的支出受益於5G核心網路的部署,這些核心網路在網路邊緣整合了分散式阻斷服務(DDoS)攻擊緩解功能。隨著軟體供應商根據《網路彈性法案》承擔法律責任,應用安全方面的應用也在不斷增加,這促進了「安全設計」實踐的普及。總而言之,這些趨勢支撐著歐洲ICT市場安全領域投資的持續成長。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟「數位十年」(2021 年至 2030 年)的資金投入加速,將促進雲端運算和 5G 的部署。
- Schrems II 裁決後,主權雲端資料位置要求激增。
- 歐洲「工業4.0走廊」推動了對工業邊緣運算的需求
- 透過加強資訊通訊技術領域的永續性法規來促進綠色資料中心的普及(歐盟綠色交易)
- 透過 O-RAN 試驗運作和初步 5G 獨立組網部署實現新的 B2B 服務。
- 透過生成式人工智慧技能提升計劃來促進軟體諮詢支出。
- 市場限制因素
- 資料中心電力消耗量,正面臨電價飆漲和碳排放稅。
- 由於持續缺乏數位化技能,導致專案進度延誤。
- 碎片化的頻率政策阻礙了5G的規模經濟效益。
- 對網路主權日益成長的擔憂限制了美國超大規模資料中心業者的市場滲透率。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素的影響
第5章 市場規模與成長預測
- 依產品類型
- IT硬體
- 電腦硬體
- 網路裝置
- 周邊設備
- IT軟體
- IT服務
- IT諮詢與實施
- IT外包(ITO)
- 業務流程外包(BPO)
- 資安管理服務
- 雲端平台服務
- IT基礎設施
- IT安全和網路安全
- 應用程式安全
- 雲端安全
- 資料安全
- 網路安全
- 端點安全
- 基礎設施保護
- 綜合風險管理
- 識別及存取管理 (IAM)
- 通訊服務
- 固定語音/數據
- 行動語音和數據
- 整合通訊協作
- IT硬體
- 按公司規模
- 小型企業
- 大公司
- 按最終用戶行業分類
- BFSI
- 政府/公共部門
- 石油和天然氣
- IT/通訊
- 零售、電子商務、消費者
- 製造業和工業
- 能源與公共產業
- 衛生保健
- 其他終端用戶產業
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 北歐的
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Hewlett Packard Enterprise Development LP
- Dell Technologies Inc.
- Apple Inc.
- Sony Europe BV
- Samsung Electronics Co., Ltd.
- Deutsche Telekom AG(T-Systems)
- IBM Corporation
- Capgemini SE
- Microsoft Corporation
- Oracle Corporation
- SAP SE
- Amazon Web Services, Inc.
- Google Cloud(Alphabet Inc.)
- Cisco Systems, Inc.
- Atos SE
- Accenture plc
- Fujitsu Limited
- Salesforce, Inc.
- Ericsson AB
- Nokia Corporation
- Schneider Electric SE
- Equinix, Inc.
- OVHcloud
- Orange Business Services
- Telefonica Tech
- Tata Consultancy Services Limited
- Infosys Limited
- Cognizant Technology Solutions
- NetApp, Inc.
- Sophos Ltd.
- Avast plc
- Darktrace plc
- Kaspersky Lab
- VMware Inc.
- ServiceNow, Inc.
- Zoom Video Communications, Inc.
- Logitech International SA
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe ICT market size is expected to increase from USD 1.09 trillion in 2025 to USD 1.24 trillion in 2026 and reach 1.59 trillion by 2031, growing at a CAGR of 5.03% over 2026-2031.
This report is Segmented by Product Type (IT Hardware, IT Software, IT Services, IT Infrastructure, IT Security/Cybersecurity, and Communication Services), Enterprise Size (SMEs and Large Enterprises), End-User (BFSI, Government, Manufacturing, Healthcare, and More), and Geography. The Market Forecasts are in Value (USD).
Europe ICT Market Trends and Insights
Accelerated EU Digital Decade Funding 2021-2030 Catalyzing Cloud and 5G Roll-outs
Large-scale public funding is front-loading network infrastructure timelines. By December 2025, member states had already invested EUR 58 billion toward gigabit connectivity and rural 5G coverage, compressing project cycles that previously stretched to the end of the decade. Vodafone Germany alone switched on 15,000 5G standalone sites in 2025, opening network-slicing pathways for automotive telematics and remote surgery. SME migration incentives covering up to half of cloud-adoption costs expanded the addressable base for platform vendors, evidenced by a 34% year-on-year rise in SME cloud take-up in 2025. Funding delays tied to state-aid reviews, however, slowed disbursements in Italy and Spain, highlighting execution risk within the bloc.
Surge in Sovereign Cloud and Data-Residency Requirements Post-Schrems II Ruling
The invalidation of the EU-US Privacy Shield triggered sweeping workload repatriation. By 2025, nearly two-thirds of large European enterprises had shifted sensitive data to EU-domiciled providers or on-premises stacks. OVHcloud booked double-digit revenue growth on the back of public-sector wins, while Deutsche Telekom partnered with a major hyperscaler to deliver a Kubernetes-based sovereign cloud aligned with German federal rules. Colocation operators followed suit, expanding low-latency facilities in Frankfurt, Amsterdam, and Paris to serve finance and public-sector users that demand strict jurisdictional control. Elevated legal-review costs continue to lengthen migration cycles, yet overall momentum favors providers with clear data-sovereignty credentials.
Energy-Intensive Data Centers Facing Escalating Power and Carbon Taxes
Data-center electricity demand hit 104 terawatt-hours in 2025, with hubs in Frankfurt, Amsterdam, and Dublin accounting for almost two-thirds of consumption. A EUR 90-per-tonne carbon-allowance price, effective January 2026, raised operating expenses for non-renewable sites by low-double-digit percentages. National interventions reinforce the pressure: Ireland's moratorium on new Dublin connections and the Netherlands' energy tax on large facilities are prompting operators to place incremental capacity in Nordic markets or to co-locate near renewable-generation assets. Participation in demand-response programs is compulsory for new German sites above 10 MW, forcing architectural redesigns and accelerating the adoption of battery-backed microgrids.
Other drivers and restraints analyzed in the detailed report include:
- Industrial Edge-Computing Demand Driven by Industry 4.0 Corridors
- Rising ICT Sustainability Mandates Under the EU Green Deal Fueling Green Data Centers
- Persistent Digital-Skills Gap Slowing Project Timelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IT security and cybersecurity are projected to expand at a 7.26% CAGR, buoyed by the NIS2 directive's 24-hour incident-reporting rule that covers 18 critical sectors. Identity and access management stands out, reflecting EU-wide zero-trust mandates that require multi-factor authentication across banking and public services. Cloud-security posture-management tools are growing as enterprises automate compliance checks, while endpoint protection faces price compression due to bundled offerings from major operating-system vendors. Meanwhile, the Europe ICT market size for IT services retains scale leadership, yet automation-rich platform offerings are shrinking traditional consulting effort. Hardware refresh cycles continue to stretch as hybrid work stabilizes, compressing demand for desktop and notebook replacements. Communication-services revenues remain steady due to vendor consolidation and unified-communications bundles that lower total cost of ownership for distributed workforces. Infrastructure spending tilts toward edge form factors, partially offsetting softer demand for large on-premises servers.
Second-generation security controls that combine threat-intelligence feeds with machine-learning analytics are spreading beyond critical infrastructure to mid-market users, signaling a deeper addressable base. Network-security spend benefits from 5G core launches, which embed distributed denial-of-service mitigation at the edge. Application-security adoption also rises as software suppliers face liability under the Cyber Resilience Act, incentivizing secure-by-design practices. Collectively, these patterns confirm that security allocations will continue to capture a rising share of the Europe ICT market.
Complete Report Scope:
- By Product Type
- IT Hardware
- Computer Hardware
- Networking Equipment
- Peripherals
- IT Software
- IT Services
- IT Consulting and Implementation
- IT Outsourcing (ITO)
- Business Process Outsourcing (BPO)
- Managed Security Services
- Cloud and Platform Services
- IT Infrastructure
- IT Security/Cybersecurity
- Application Security
- Cloud Security
- Data Security
- Network Security
- Endpoint Security
- Infrastructure Protection
- Integrated Risk Management
- Identity and Access Management (IAM)
- Communication Services
- Fixed Voice and Data
- Mobile Voice and Data
- Unified Communications and Collaboration
- IT Hardware
- By Enterprise Size
- Small and Medium-Sized Enterprises
- Large Enterprises
- By End-User Industry Vertical
- BFSI
- Government and Public Sector
- Oil and Gas
- IT and Telecom
- Retail, E-Commerce and Consumers
- Manufacturing and Industrial
- Energy and Utilities
- Healthcare
- Other End-User Industry Verticals
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Nordics
- Rest of Europe
List of Companies Covered in this Report:
- Hewlett Packard Enterprise Development LP
- Dell Technologies Inc.
- Apple Inc.
- Sony Europe B.V.
- Samsung Electronics Co., Ltd.
- Deutsche Telekom AG (T-Systems)
- IBM Corporation
- Capgemini SE
- Microsoft Corporation
- Oracle Corporation
- SAP SE
- Amazon Web Services, Inc.
- Google Cloud (Alphabet Inc.)
- Cisco Systems, Inc.
- Atos SE
- Accenture plc
- Fujitsu Limited
- Salesforce, Inc.
- Ericsson AB
- Nokia Corporation
- Schneider Electric SE
- Equinix, Inc.
- OVHcloud
- Orange Business Services
- Telefonica Tech
- Tata Consultancy Services Limited
- Infosys Limited
- Cognizant Technology Solutions
- NetApp, Inc.
- Sophos Ltd.
- Avast plc
- Darktrace plc
- Kaspersky Lab
- VMware Inc.
- ServiceNow, Inc.
- Zoom Video Communications, Inc.
- Logitech International S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated EU Digital Decade Funding 2021-2030 Catalyzing Cloud and 5G Roll-outs
- 4.2.2 Surge in Sovereign Cloud and Data Residency Requirements Post-Schrems II Ruling
- 4.2.3 Industrial Edge Computing Demand Driven by Europe's Industry 4.0 Corridors
- 4.2.4 Rising ICT Sustainability Mandates (EU Green Deal) Fueling Green Data Centres
- 4.2.5 O-RAN Trials and Early 5G Standalone Deployments Enabling New B2B Services
- 4.2.6 Generative AI Upskilling Programmes Stimulating Software and Consulting Spend
- 4.3 Market Restraints
- 4.3.1 Energy-Intensive Data Centres Facing Escalating Power and Carbon Taxes
- 4.3.2 Persistent Digital Skills Gap Slowing Project Timelines
- 4.3.3 Fragmented Spectrum Policies Hindering 5G Economies of Scale
- 4.3.4 Heightened Cyber-Sovereignty Concerns Limiting US Hyperscaler Penetration
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 IT Hardware
- 5.1.1.1 Computer Hardware
- 5.1.1.2 Networking Equipment
- 5.1.1.3 Peripherals
- 5.1.2 IT Software
- 5.1.3 IT Services
- 5.1.3.1 IT Consulting and Implementation
- 5.1.3.2 IT Outsourcing (ITO)
- 5.1.3.3 Business Process Outsourcing (BPO)
- 5.1.3.4 Managed Security Services
- 5.1.3.5 Cloud and Platform Services
- 5.1.4 IT Infrastructure
- 5.1.5 IT Security/Cybersecurity
- 5.1.5.1 Application Security
- 5.1.5.2 Cloud Security
- 5.1.5.3 Data Security
- 5.1.5.4 Network Security
- 5.1.5.5 Endpoint Security
- 5.1.5.6 Infrastructure Protection
- 5.1.5.7 Integrated Risk Management
- 5.1.5.8 Identity and Access Management (IAM)
- 5.1.6 Communication Services
- 5.1.6.1 Fixed Voice and Data
- 5.1.6.2 Mobile Voice and Data
- 5.1.6.3 Unified Communications and Collaboration
- 5.1.1 IT Hardware
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium-Sized Enterprises
- 5.2.2 Large Enterprises
- 5.3 By End-User Industry Vertical
- 5.3.1 BFSI
- 5.3.2 Government and Public Sector
- 5.3.3 Oil and Gas
- 5.3.4 IT and Telecom
- 5.3.5 Retail, E-Commerce and Consumers
- 5.3.6 Manufacturing and Industrial
- 5.3.7 Energy and Utilities
- 5.3.8 Healthcare
- 5.3.9 Other End-User Industry Verticals
- 5.4 By Country
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Netherlands
- 5.4.7 Nordics
- 5.4.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Hewlett Packard Enterprise Development LP
- 6.4.2 Dell Technologies Inc.
- 6.4.3 Apple Inc.
- 6.4.4 Sony Europe B.V.
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 Deutsche Telekom AG (T-Systems)
- 6.4.7 IBM Corporation
- 6.4.8 Capgemini SE
- 6.4.9 Microsoft Corporation
- 6.4.10 Oracle Corporation
- 6.4.11 SAP SE
- 6.4.12 Amazon Web Services, Inc.
- 6.4.13 Google Cloud (Alphabet Inc.)
- 6.4.14 Cisco Systems, Inc.
- 6.4.15 Atos SE
- 6.4.16 Accenture plc
- 6.4.17 Fujitsu Limited
- 6.4.18 Salesforce, Inc.
- 6.4.19 Ericsson AB
- 6.4.20 Nokia Corporation
- 6.4.21 Schneider Electric SE
- 6.4.22 Equinix, Inc.
- 6.4.23 OVHcloud
- 6.4.24 Orange Business Services
- 6.4.25 Telefonica Tech
- 6.4.26 Tata Consultancy Services Limited
- 6.4.27 Infosys Limited
- 6.4.28 Cognizant Technology Solutions
- 6.4.29 NetApp, Inc.
- 6.4.30 Sophos Ltd.
- 6.4.31 Avast plc
- 6.4.32 Darktrace plc
- 6.4.33 Kaspersky Lab
- 6.4.34 VMware Inc.
- 6.4.35 ServiceNow, Inc.
- 6.4.36 Zoom Video Communications, Inc.
- 6.4.37 Logitech International S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 中東和北非資訊通訊技術(ICT):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)中國資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)日本資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)西班牙資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)越南資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)新加坡資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)法國資訊通訊技術:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資訊通訊技術:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)美國資訊通訊技術:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)