


 |
市場調查報告書
商品編碼
2125544
東協行動虛擬網路營運商:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)ASEAN Mobile Virtual Network Operator (MVNO) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
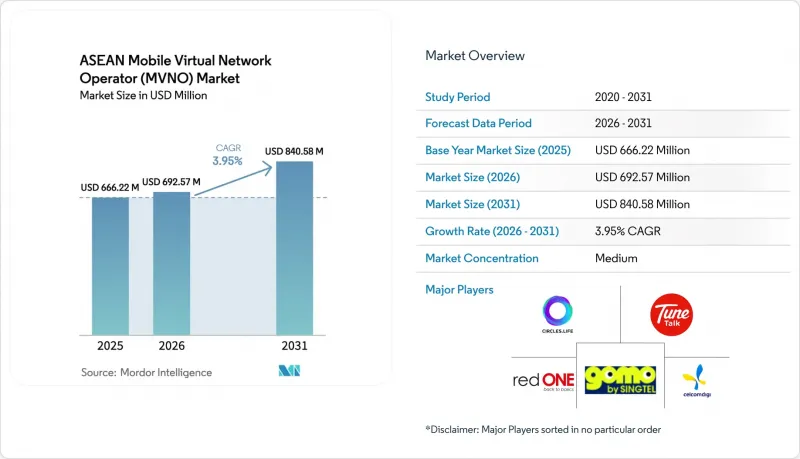
根據 Mordor Intelligence 預測,東協 MVNO 市場規模將從 2025 年的 6.6622 億美元成長到 2026 年的 6.9257 億美元,然後在 2031 年達到 8.4058 億美元,2026 年至 2031 年的複合年成長率為 3.95%。
本報告按部署模式(雲端/本地部署)、營運模式(經銷商等)、用戶類型(消費者等)、應用領域(折扣、企業、蜂窩M2M等)、網路技術(2G/3G、4G/LTE等)、分銷通路(線上/純數位通路等)和地區進行細分。市場預測以美元計價。
東協虛擬行動網路營運商 (MVNO) 市場趨勢與洞察
行動用戶數量和智慧型手機普及率不斷成長
2025年,東協行動寬頻網路用戶將超過4.5億,其中越南遙遙領先,三大業者控制超過90%的網路容量,用戶已達1.047億。在新加坡、馬來西亞和泰國,都市區智慧型手機普及率已超過80%。然而,在印尼和菲律賓的低收入地區和農村地區,用戶仍然依賴預付數據套餐,這為以性價比為導向的行動虛擬網路營運商(MVNO)提供了成長空間。在主要市場,年輕人口(中位數人口年齡在30歲以下)推動了數據使用量的成長,使其不再局限於語音通訊,這促使虛擬網路運營商設計以大資料方案和短通話時長為核心的套餐。歷史數據顯示,智慧型手機普及率每提高1個百分點,MVNO用戶數就會增加約1.5個百分點,進一步強化了這個良性循環。隨著獨立組網 5G 的部署,MVNO 可以推出差異化的低延遲服務,但在 4G 覆蓋仍然不足的地區,部署速度緩慢,預計 LTE 網路的角色在短期內仍將維持。
低價語音和資料方案的需求
新加坡的價格競爭異常激烈,平均每月用戶收入(ARPU)在5美元至8美元之間,而印尼和菲律賓則為15美元至20美元。 2025年,折扣型虛擬業者(MVNO)將透過銷售100GB至300GB的預付SIM卡(價格相當於該地貨幣5美元至15美元)來佔據28.71%的新契約佔有率,其定價低於行動網路營運商(MNO)的子品牌。全部區域約有1000萬外籍勞工,他們更傾向於無限國際通話和本地漫遊,而全球品牌正透過包含匯款服務的套餐來開拓這些細分市場。儘管泰國計劃在2026年將批發價格下調20%,這將為零售價格上漲創造空間,但持續的價格競爭將用戶的投資回收期延長至18至24個月,導致現金流緊張。因此,電信業者將數據流量結轉和忠誠度優惠作為套餐的一部分提供,以在不提高表面價格的情況下有效提高每位用戶平均收入 (ARPU)。
激烈的競爭給利潤率帶來了壓力。
GOMO 和 Giga 等行動網路營運商 (MNO) 旗下的數位品牌提供 100-300GB 的流量套餐,售價為 10-18 新元,利用其網路成本優勢與獨立虛擬網路營運商 (MVNO) 競爭。批發費用佔 MVNO 零售收入的 60% 之多,扣除行銷和支援成本後,毛利率僅為 15-20%。在新加坡,預計 2023 年至 2025 年間,每位用戶獲客成本將達到 40-60 新元,需要兩年時間才能收回成本。這導致一些營運商因新加入經營者面臨融資困境而退出市場。雖然馬來西亞的雙 5G 網路引入了正式的價格監管,但已披露的合約表明,主機營運商仍然主導著定價。最低保證條款規定,如果使用率低於平均水平,將受到處罰,這促使虛擬網路營運商將重點轉向高價值的企業和物聯網細分市場,因為這些市場的合約量與可預測的需求相符。
細分市場分析
預計到2025年,雲端託管解決方案將佔東協虛擬營運商(MVNO)市場佔有率的56.71%,受計量收費採用率驅動,東協MVNO市場規模預計將以4.58%的複合年成長率成長至2031年。從300萬至500萬美元的初始投資轉向「按需付費」的營運成本模式,促使許多新創公司採用AWS、Azure或Google Cloud來建立其業務支撐系統/營運支撐系統(BSS/OSS)。 MyRepublic在遷移到Tata Communications的雲端平台後僅花了90天就推出了服務,而本地部署則需要長達18個月的時間。此外,單一租戶雲端實例允許快速整合本地化模組,從而簡化跨國業務的擴張。這對於東協地區的成長策略至關重要。由於全功能MVNO和受監管行業更傾向於本地資料儲存和超低延遲,本地部署系統仍然佔據56.71%的市場佔有率。 Circles.Life 在 2024 年遷移到雲端原生核心系統後,用戶成本降低了近 40%,這種效率在傳統部署中難以複製。監管方面的細微差異也至關重要。印尼的資料主權法規要求某些特定類型的資料必須儲存在國內,因此,在過渡時期,混合雲端(收費在國內處理,而客戶關係管理 (CRM) 則運行在公共雲端上)很可能佔據主導地位。預計到 2028 年,東協市場超過 70% 的新型行動虛擬網路推出(MVNO) 將採用「雲端優先」策略,這反映了其策略重心從硬體所有權轉向服務編配。
競爭優勢在於速度和柔軟性。雲端API支援快速整合增值應用,例如行動支付、內容串流媒體和物聯網儀表板,使虛擬營運商能夠每周而非每季更新服務。然而,供應商鎖定問題日益凸顯,因為雲端遷移可能需要耗費年度IT支出的20%至30%,抵銷了部分敏捷性提升帶來的好處。儘管營運商正嘗試實施多重雲端以確保冗餘,但對於小規模的團隊而言,增加的複雜性可能超過其帶來的收益。整體而言,雲端的採用正在重塑成本結構,降低准入門檻,並加劇東協虛擬營運商市場的競爭。
儘管到2025年,轉售模式仍佔據38.57%的市場佔有率,但由全功能虛擬網路營運商(MVNO)組成的東協MVNO市場預計到2031年將以4.91%的複合年成長率成長。轉售商憑藉大量購買通話時間和資料通訊流量並以自有品牌轉售的簡單經營模式獲得了成功,這使得他們能夠將初始投資控制在100萬美元以下。然而,這種模式的代價是放棄了對路由、服務品質和批發成本的控制權。在日益激烈的競爭中,虛擬網路營運商正在向全功能MVNO轉型,部署HLR、封包閘道器和策略引擎以恢復利潤率並實現服務差異化。 Circles.Life和StarHub的「千兆」服務清晰地展現了這一轉變,這兩家公司都增加了核心網路元素來管理服務品質(QoS),並提供諸如面向企業的私有APN等增值功能。服務業者和輕量級/品牌化 MVNO 提供了一種在成本和有限差異化之間取得平衡的中間選擇,但它們的成長速度落後於整個 MVNO 產業。
資金籌措仍然是一大障礙。部署一個基本的核心網路需要500萬至1000萬美元以及技術嫻熟的工程師,這導致許多新參與企業選擇與託管服務供應商合作,由後者在多個客戶之間分攤基礎設施成本。監理政策的改變也是一個利多因素。泰國和越南現已強制實行開放式批發接入,這賦予了旨在成為完全MVNO(行動虛擬網路營運商)的營運商更強的議價能力,從而更有力地證明投資的合理性。盈利跡像也開始顯現,領先採用者報告稱,毛利率已從轉售時代的20%上升到全面轉型後的近35%。因此,預計到2029年後,完全MVNO將在東協MVNO市場佔有率中超越轉售商,並且該行業預計將朝著更深層的垂直整合方向發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 產業價值鏈分析
- 市場促進因素
- 行動用戶數量和智慧型手機普及率不斷成長
- 低價語音和資料方案的需求
- 物聯網和機器對機器(M2M)連接的擴展
- 監管機構推動利用裸井接入和eSIM技術進入市場
- 金融科技與通訊業的融合正在催生銀行品牌的行動虛擬網路營運商(MVNO)。
- 衛星網路和行動電話網路的整合使行動虛擬網路營運商能夠向全球提供服務。
- 市場限制因素
- 激烈的競爭給利潤率帶來了壓力。
- 網路品質和批發價格依賴主機行動網路營運商。
- 設備 OEM 廠商控制 eSIM 的所有權,繞過 MVNO 模式。
- 私有頻譜共享允許公司自行提供服務。
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
- 投資分析
第5章 市場規模與成長預測
- 按部署模式
- 雲
- 現場
- 透過操作模式
- 經銷商
- 服務提供者
- 完整的虛擬營運商
- 輕量級,品牌虛擬營運商
- 用戶類型
- 消費者
- 公司
- 物聯網專用
- 透過使用
- 折扣
- 商業
- 細胞M2M
- 媒體與娛樂
- 零售
- 漫遊
- 移民
- 批發郵購
- 透過網路技術
- 2G、3G
- 4G、LTE
- 5G
- 衛星,NTN
- 透過分銷管道
- 僅限線上數位平台
- 傳統零售店
- 開利子品牌商店
- 第三方批發
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- TracFone Wireless, Inc.
- Tesco Mobile Limited
- Virgin Mobile(Virgin Media O2)
- Lycamobile Group
- Lebara Group BV
- Boost Mobile LLC
- Cricket Wireless LLC
- Giffgaff Limited
- 1&1 Drillisch AG
- PosteMobile SpA
- Truphone Limited
- Kajeet, Inc.
- Ting Mobile(Dish Wireless)
- Google Fi Wireless
- Altice Mobile(Optimum Mobile)
- Asahi Net, Inc.
- FreedomPop, Inc.
- Airvoice Wireless LLC
- FRiENDi Mobile
- Voiceworks BV
第7章 市場機會與未來展望
According to Mordor Intelligence, the ASEAN MVNO market size is expected to grow from USD 666.22 million in 2025 to USD 692.57 million in 2026 and is forecast to reach USD 840.58 million by 2031 at 3.95% CAGR over 2026-2031.
This report is Segmented by Deployment Model (Cloud and On-Premise), Operational Mode (Reseller, and More), Subscriber Type (Consumer, and More), Application (Discount, Business, Cellular M2M, and More), Network Technology (2G/3G, 4G/LTE, and More), Distribution Channel (Online/Digital-Only, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
ASEAN Mobile Virtual Network Operator (MVNO) Market Trends and Insights
Rising Mobile-Subscriber Base and Smartphone Penetration
ASEAN counted more than 450 million mobile broadband lines in 2025, led by Vietnam with 104.7 million subscriptions under three dominant networks that control over 90% of capacity. Urban smartphone penetration already tops 80 percent in Singapore, Malaysia, and Thailand, but lower-income and rural zones across Indonesia and the Philippines still rely on prepaid data packs, creating headroom for value-driven MVNOs. Youthful demographics median age below 30 across key markets propel data usage that outpaces voice traffic, so virtual operators design plans centered on large data buckets and minimal voice minutes. Historical data show every 1-percentage-point uptick in smartphone penetration adds roughly 1.5 points to MVNO subscriber growth, reinforcing the positive feedback loop. As standalone 5G rolls out, MVNOs can launch differentiated low-latency services, yet adoption lags in areas where 4G coverage remains incomplete, preserving the near-term role of LTE networks.
Demand for Low-Cost Voice and Data Plans
Average monthly ARPU ranges between USD 5 and USD 8 in Indonesia and the Philippines, compared with USD 15-20 in Singapore, so price competition is acute. Discount MVNOs captured 28.71% of applications in 2025 by marketing prepaid SIMs with 100-300 GB for the local equivalent of USD 5-15, undercutting MNO sub-brands. Migrant workers about 10 million region-wide favour unlimited international calls and regional roaming, niches that global brands exploit with bundled remittance services. Thailand's 20% wholesale-fee reduction scheduled for 2026 will widen retail price headroom, but sustained undercutting lengthens subscriber payback periods to 18-24 months, stretching cash flow. Operators therefore bundle data rollover or loyalty rewards to lift effective ARPU without headline price hikes.
Margin Squeeze from Intense Price Competition
MNO digital brands such as GOMO and Giga price 100-300 GB plans at SGD 10-18, matching independent MVNO offers while enjoying network cost advantages. Wholesale fees absorb up to 60% of MVNO retail revenue, leaving slender 15-20% gross margins after marketing and support. Singapore saw multiple shutdowns between 2023 and 2025 because acquisition costs of SGD 40-60 per user demanded two-year payback periods that cash-strapped entrants could not sustain. Malaysia's dual 5G network introduces official price oversight, yet disclosed contracts show host operators still retain rate-setting leverage. Minimum-guarantee clauses penalize under-utilization, prompting virtual operators to pivot toward higher-value enterprise and IoT niches where volume commitments align with predictable demand.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of IoT and M2M Connections
- Regulatory Push for Open Wholesale Access and eSIM-Enabled Entry
- Dependence on Host MNOs for Network Quality and Wholesale Fees
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-hosted solutions captured 56.71% of the ASEAN MVNO market share in 2025, and the ASEAN MVNO market size for cloud deployments is forecast to expand at a 4.58% CAGR through 2031. Reduced capital outlay shift from USD 3-5 million upfront to pay-as-you-grow operating expense has convinced many start-ups to adopt AWS, Azure, or Google Cloud for BSS and OSS. MyRepublic launched in just 90 days after migrating to Tata Communications' cloud stack, whereas on-premises builds require up to 18 months. Single-tenant cloud instances also simplify multi-country expansion because localization modules plug in quickly, which is critical for pan-ASEAN growth strategies. On-premises systems still hold 56.71% share because full MVNOs and regulated verticals prefer local data custody and ultra-low latency. Circles.Life trimmed per-subscriber costs by almost 40% after shifting to a cloud-native core in 2024, an efficiency that is hard for legacy deployments to replicate. Regulatory nuances matter: Indonesia's data-sovereignty rules oblige certain data classes to reside domestically, so hybrid clouds that keep billing in-country while running CRM in public cloud will dominate the transition period. Looking ahead, over 70% of new ASEAN MVNO market launches are expected to be cloud-first by 2028, reflecting a strategic pivot from hardware ownership to service orchestration.
The competitive payoff is speed and flexibility. Cloud APIs support rapid integration of value-added apps mobile payments, content streaming, or IoT dashboards allowing virtual operators to refresh offers weekly rather than quarterly. However, vendor lock-in is emerging as a concern since migrating between clouds could cost 20-30% of annual IT spend, offsetting some agility gains. Operators are experimenting with multi-cloud for redundancy, though added complexity may outweigh benefits for smaller teams. Overall, cloud adoption is redefining cost structures and lowering entry barriers, intensifying rivalry within the ASEAN MVNO market.
Reseller models led with 38.57% share in 2025, yet the ASEAN MVNO market size for full MVNO configurations is projected to grow at a 4.91% CAGR to 2031. Resellers thrive on simplicity, purchasing bulk minutes and data, then rebranding, which keeps initial investment under USD 1 million. Still, they surrender control over routing, quality of service, and wholesale costs. As price competition intensifies, virtual operators are upgrading to full MVNO status, installing HLRs, packet gateways, and policy engines to reclaim margin and service differentiation. Circles.Life and StarHub's giga illustrate the shift, each adding core-network elements to manage QoS and launch value-added features like private APN for enterprises. Service Operator and Light/Brand MVNOs provide a middle path, balancing cost with limited differentiation, but growth rates lag the full MVNO frontier.
Capital remains the hurdle: basic core deployments need USD 5-10 million and skilled engineers, so many entrants partner with managed-service providers who amortize infrastructure across multiple clients. Regulatory changes help; Thailand and Vietnam mandate open wholesale access, giving would-be full MVNOs better bargaining power to justify investment. Profitability evidence is building early movers report gross margins rising from 20 percent as resellers to near 35 percent after full migration. Consequently, the share of full MVNOs in the ASEAN MVNO market is expected to overtake resellers after 2029, pushing the industry toward deeper vertical integration.
Complete Report Scope:
- By Deployment Model
- Cloud
- On-Premise
- By Operational Mode
- Reseller
- Service Operator
- Full MVNO
- Light, Brand MVNO
- By Subscriber Type
- Consumer
- Enterprise
- IoT-Specific
- By Application
- Discount
- Business
- Cellular M2M
- Media and Entertainment
- Retail
- Roaming
- Migrant
- Telecom Wholesale
- By Network Technology
- 2G, 3G
- 4G, LTE
- 5G
- Satellite, NTN
- By Distribution Channel
- Online, Digital-Only
- Traditional Retail Stores
- Carrier Sub-Brand Stores
- Third-Party, Wholesale
List of Companies Covered in this Report:
- TracFone Wireless, Inc.
- Tesco Mobile Limited
- Virgin Mobile (Virgin Media O2)
- Lycamobile Group
- Lebara Group B.V.
- Boost Mobile LLC
- Cricket Wireless LLC
- Giffgaff Limited
- 1&1 Drillisch AG
- PosteMobile S.p.A.
- Truphone Limited
- Kajeet, Inc.
- Ting Mobile (Dish Wireless)
- Google Fi Wireless
- Altice Mobile (Optimum Mobile)
- Asahi Net, Inc.
- FreedomPop, Inc.
- Airvoice Wireless LLC
- FRiENDi Mobile
- Voiceworks B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value-Chain Analysis
- 4.3 Market Drivers
- 4.3.1 Rising Mobile-Subscriber Base and Smartphone Penetration
- 4.3.2 Demand for Low-Cost Voice and Data Plans
- 4.3.3 Expansion of IoT, M2M Connections
- 4.3.4 Regulatory Push for Open Wholesale Access and eSIM-Enabled Entry
- 4.3.5 Fintech and Telco Convergence Spawning Bank-Branded MVNOs
- 4.3.6 Satellite-to-Cell Partnerships Enabling Global MVNO Coverage
- 4.4 Market Restraints
- 4.4.1 Margin Squeeze from Intense Price Competition
- 4.4.2 Dependence on Host MNOs for Network Quality and Wholesale Fees
- 4.4.3 Device-OEM Control of eSIM Ownership Bypassing MVNO Model
- 4.4.4 Private-Spectrum Sharing Lets Enterprises Self-Provision Service
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 Cloud
- 5.1.2 On-Premise
- 5.2 By Operational Mode
- 5.2.1 Reseller
- 5.2.2 Service Operator
- 5.2.3 Full MVNO
- 5.2.4 Light, Brand MVNO
- 5.3 By Subscriber Type
- 5.3.1 Consumer
- 5.3.2 Enterprise
- 5.3.3 IoT-Specific
- 5.4 By Application
- 5.4.1 Discount
- 5.4.2 Business
- 5.4.3 Cellular M2M
- 5.4.4 Media and Entertainment
- 5.4.5 Retail
- 5.4.6 Roaming
- 5.4.7 Migrant
- 5.4.8 Telecom Wholesale
- 5.5 By Network Technology
- 5.5.1 2G, 3G
- 5.5.2 4G, LTE
- 5.5.3 5G
- 5.5.4 Satellite, NTN
- 5.6 By Distribution Channel
- 5.6.1 Online, Digital-Only
- 5.6.2 Traditional Retail Stores
- 5.6.3 Carrier Sub-Brand Stores
- 5.6.4 Third-Party, Wholesale
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank, Share, Products and Services, Recent Developments)
- 6.4.1 TracFone Wireless, Inc.
- 6.4.2 Tesco Mobile Limited
- 6.4.3 Virgin Mobile (Virgin Media O2)
- 6.4.4 Lycamobile Group
- 6.4.5 Lebara Group B.V.
- 6.4.6 Boost Mobile LLC
- 6.4.7 Cricket Wireless LLC
- 6.4.8 Giffgaff Limited
- 6.4.9 1&1 Drillisch AG
- 6.4.10 PosteMobile S.p.A.
- 6.4.11 Truphone Limited
- 6.4.12 Kajeet, Inc.
- 6.4.13 Ting Mobile (Dish Wireless)
- 6.4.14 Google Fi Wireless
- 6.4.15 Altice Mobile (Optimum Mobile)
- 6.4.16 Asahi Net, Inc.
- 6.4.17 FreedomPop, Inc.
- 6.4.18 Airvoice Wireless LLC
- 6.4.19 FRiENDi Mobile
- 6.4.20 Voiceworks B.V.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 中國行動網路業者(MNO):市佔率分析、產業趨勢與統計及成長預測(2026-2031)西班牙電信行動網路業者:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)馬來西亞電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)中東和非洲電信營運商(MNO):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)印度電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)日本行動網路業者(MNO):市佔率分析、產業趨勢與統計及成長預測(2026-2031)法國電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)美國行動網路營運商(MNO):市場佔有率分析、產業趨勢與統計數據、成長預測(2026-2031 年)義大利行動網路營運商(MNO):市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)