


 |
市場調查報告書
商品編碼
2116872
法國電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)France Telecom MNO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
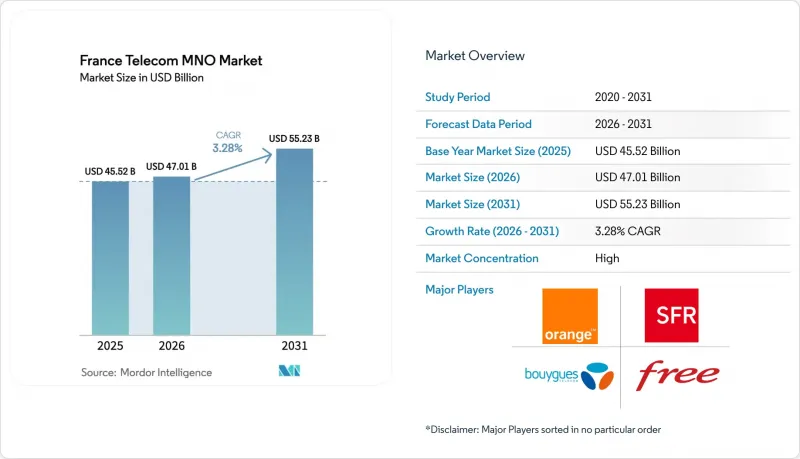
根據 Mordor Intelligence 預測,法國電信行動網路營運商 (MNO) 市場規模預計將從 2025 年的 455.2 億美元成長到 2026 年的 470.1 億美元,然後從 2026 年到 2031 年以 3.28% 的複合年成長率成長,達到 2031 億美元。
本報告按服務類型(語音服務、數據和網際網路服務、即時通訊服務、物聯網和機器對機器通訊服務、OTT和付費電視服務等)和最終用戶(企業和消費者)進行分類。市場預測以價值(美元)和規模(用戶數量)為單位呈現。
法國電信行動網路營運商市場的趨勢與洞察
5G覆蓋範圍的擴大和固定無線存取(FWA)正在推動以資料為中心的收入結構。
早期5G獨立組網(SA)服務的推出正在改變行動業務的經濟結構,優質網路切片技術提高了每用戶平均收入(ARPU),並緩解了尖峰時段的網路擁塞。固定無線存取(FWA)利用現有的無線資產為沒有光纖基礎設施的農村家庭提供服務,使營運商能夠更有效地利用頻段,同時擴大其競爭優勢。 Orange的5G核心網路即服務(CaaS)降低了區域營運商的進入門檻,加速了全國範圍的覆蓋擴展,並促進了服務創新。隨著對延遲敏感的工作負載向邊緣遷移,能夠在低延遲接入和雲端接近性之間取得平衡的營運商將在法國電信行動網路營運商(MNO)市場中佔據優勢。
基於光纖的FMC捆綁包正在提升固定和移動ARPU值。
Gigabit(FTTH) 和 5G 的無縫捆綁正在提升每戶家庭的消費額並降低解約率。目前,已有 2,060 萬戶家庭接入了 FTTH,普及率高達 78%。布依格電信 (Bouygues Telecom) 透過推廣全包套餐,在穩定行動資費的同時,實現了 33 歐元的固定平均每用戶收入 (ARPU),這表明融合服務能夠有效避免單純的價格競爭。整合智慧服務編配和跨通路服務的電信業者將能夠實現最佳的用戶終身價值。
由於競爭激烈,ARPU(每位使用者平均收入)整體保持停滯不前。
自Free Mobile加入價格戰以來,典型套餐的標價在2011年至2016年間下降了45%,業者仍在努力將與網路品質相符的溢價轉嫁給消費者。 Opensignal的研究表明,Orange在下載速度和覆蓋範圍方面仍然保持領先地位,但其行動ARPU值基本上保持不變,因為價格敏感的用戶會在促銷活動出現時立即更換營運商。這場持續不斷的價格戰迫使法國行動網路營運商(MNO)市場的所有營運商追求效率和服務多元化,而不是表面上的價格上漲。
細分市場分析
2025年,數據和網路服務將佔法國電信行動網路營運商(MNO)市場佔有率的57.39%,成為主要收入來源,取代語音通訊。物聯網(IoT)和機器對機器(M2M)市場預計到2031年將以3.39%的複合年成長率成長,反映出企業對連網機器和智慧城市網路的需求日益成長。 OTT和付費電視配套服務允許營運商將Netflix、Disney+和本地串流媒體應用整合到統一介面,從而提高客戶留存率,並降低捆綁服務以外的用戶流失率。雖然隨著客戶轉向OTT服務,語音和通訊收入正在下降,但它們在入境漫遊和履行監管規定的緊急通訊義務方面仍然發揮著重要作用。
隨著數據流量的持續成長,電信營運商被迫提高無線基地台密度並部署邊緣運算。同時,物聯網專案的蓬勃發展也推動了對輕量級核心網路和設備管理平台的投資。隨著為巴黎奧運和工業園區建設的專用5G網路的出現,預計專用網路切片的每位元收入將高於盡力而為型行動寬頻。將連接服務與分析、安全和雲端整合捆綁在一起的電信營運商將在法國電信行動網路營運商(MNO)市場這一快速成長的細分領域中佔據相當大的佔有率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 監理與政策框架
- 頻段狀況和競爭對手擁有情形
- 通訊業生態系統
- 宏觀經濟與外在因素
- 波特五力分析
- 主要行動網路營運商 (MNO) 的關鍵績效指標 (KPI) (2020-2025)
- 行動用戶數量和普及率
- 行動網路使用者數量和普及率
- 按接入技術分類的SIM卡合約數量和滲透率
- 蜂巢式物聯網/機器對機器連接數
- 寬頻連線數(移動和固定)
- ARPU(每位用戶平均收入)
- 用戶平均每月數據使用量(GB/月)
- 市場促進因素
- 5G 服務區域和 FWA(免費廣域網際網路)的擴展正在推動以數據為中心的錢包的發展。
- 基於光纖的FMC捆綁包正在提升固定和移動ARPU值。
- 影片串流媒體和雲端遊戲正在推動行動數據需求。
- 企業工業 4.0 專案正在加速物聯網 SIM 卡的普及應用。
- 開放 3.5 GHz 頻段用於民用 5G SA 網路。
- 僅支援 eSIM 的設備銷售管道可降低解約率和獲客成本。
- 市場限制因素
- 由於競爭激烈,混合平均每用戶收入 (ARPU) 一直保持穩定。
- 由於 SIM 卡普及率達到 110%,自然成長帶來的用戶數量成長受到抑制。
- 生態設計和能源效率法規導致營運成本增加。
- 毫米波頻率競標時間的不確定性正在推遲資本投資計畫。
- 技術展望
- 電信業關鍵經營模式分析
- 定價模型和定價分析
第5章 市場規模與成長預測
- 整個通訊業的銷售額和每用戶平均收入
- 按服務類型
- 語音服務
- 數據網際網路服務
- 通訊服務
- 物聯網/機器對機器服務
- OTT(非櫃檯)和付費電視服務
- 其他服務(附加價值服務、漫遊和國際服務、企業和批發服務等)
- 最終用戶
- 公司
- 消費者
第6章 競爭情勢
- 市場集中度
- 主要供應商的策略性舉措和投資(2023-2025 年)
- 2024年行動通訊業者(MNO)市佔率分析
- Product Benchmarking Analysis for mobile network services
- MNO snapshot(subscribers, churn rate, ARPU, etc.)
- 行動通訊業者(MNO)公司簡介*
- Orange SA
- SFR(Altice France)
- Bouygues Telecom
- Free Mobile(Iliad)
第7章 市場機會與未來展望
According to Mordor Intelligence, the France telecom MNO market size is expected to grow from USD 45.52 billion in 2025 to USD 47.01 billion in 2026 and is forecast to reach USD 55.23 billion by 2031 at 3.28% CAGR over 2026-2031.
This report is Segmented by Service Type (Voice Services, Data and Internet Services, Messaging Services, Iot and M2M Services, OTT and PayTV Services, and Other Services), and End User (Enterprises, Consumer). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Subscribers).
France Telecom MNO Market Trends and Insights
5G Coverage Expansion and FWA Drives Data-Centric Wallets
Early 5G standalone launches are shifting mobile economics as premium network slicing elevates ARPU and alleviates peak-hour congestion . Fixed Wireless Access leverages existing radio assets to serve rural households that lack fiber, enabling carriers to monetize spectrum more efficiently while extending competitive reach. Orange's 5G Core Network-as-a-Service offer lowers entry costs for regional operators, accelerating nationwide coverage and fostering service innovation. As latency-sensitive workloads migrate to the edge, the France telecom MNO market will favor providers that can pair low-latency access with cloud adjacency.
Fiber-Backed FMC Bundles Boost Fixed/Mobile ARPU Uplift
Seamless bundling of gigabit FTTH and 5G is raising household spend and reducing churn as 20.6 million homes now subscribe to FTTH with a 78% take-up rate . Bouygues Telecom has demonstrated an EUR 33 fixed ARPU while stabilizing mobile prices by promoting all-inclusive plans, confirming that convergent offers can insulate revenue from pure-price plays . Operators that integrate intelligent service orchestration and cross-channel care will capture the highest lifetime value.
Fierce Price Competition Keeps Blended ARPU Flat
Since Free Mobile disrupted pricing, the nominal price of a typical bundle has fallen 45% between 2011 and 2016, and operators still struggle to pass network-quality premiums to consumers. Opensignal continues to rank Orange at the top on download speed and coverage yet its mobile ARPU remains broadly flat because price-sensitive users switch quickly when promotions appear. This perpetual discounting forces carriers to chase efficiency and service diversification rather than headline price increases across the France telecom MNO market.
Other drivers and restraints analyzed in the detailed report include:
- Video-Streaming and Cloud Gaming Fuel Mobile Data Demand
- Enterprise Industry 4.0 Projects Accelerate IoT SIM Uptake
- >110% SIM Penetration Limits Organic Subscriber Growth
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Data and Internet services secured 57.39% of the France telecom MNO market share in 2025, displacing voice as the primary revenue pillar. The France telecom MNO market size for IoT and M2M is set to expand at a 3.39% CAGR through 2031, reflecting enterprise appetite for connected machinery and smart city grids. OTT and PayTV bundles broaden stickiness as carriers integrate Netflix, Disney+, and local streaming apps into unified interfaces that curb out-of-bundle churn. Voice and messaging revenues slide as customers shift to over-the-top alternatives, yet remain relevant for inbound roaming and regulatory emergency obligations.
Continued data traffic growth obliges operators to densify radio sites and introduce edge compute, while IoT project momentum encourages investment in lightweight cores and device-management platforms. As private 5G networks emerge for the Paris Olympics and industrial campuses, the France Telecom MNO market will see higher revenue per bit for specialized slices than for best-effort mobile broadband. Operators that bundle analytics, security, and cloud integration alongside connectivity will capture the bulk of value in this ascending segment of the France telecom MNO market.
Complete Report Scope:
- Overall Telecom Revenue and ARPU
- Service Type
- Voice Services
- Data and Internet Services
- Messaging Services
- IoT and M2M Services
- OTT and PayTV Services
- Other Services (VAS, Roaming and International Services, Enterprise and Wholesale Services, etc.)
- End-user
- Enterprises
- Consumer
List of Companies Covered in this Report:
- Orange S.A.
- SFR (Altice France)
- Bouygues Telecom
- Free Mobile (Iliad)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Regulatory and Policy Framework
- 4.3 Spectrum Landscape and Competitive Holdings
- 4.4 Telecom Industry Ecosystem
- 4.5 Macroeconomic and External Drivers
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Competitive Rivalry
- 4.6.2 Threat of New Entrants
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Bargaining Power of Buyers
- 4.6.5 Threat of Substitutes
- 4.7 Key MNO KPIs (2020-2025)
- 4.7.1 Unique Mobile Subscribers and Penetration Rate
- 4.7.2 Mobile Internet Users and Penetration Rate
- 4.7.3 SIM Connections by Access Technology and Penetration
- 4.7.4 Cellular IoT / M2M Connections
- 4.7.5 Broadband Connections (Mobile and Fixed)
- 4.7.6 ARPU (Average Revenue Per User)
- 4.7.7 Average Data Usage per Subscription (GB/month)
- 4.8 Market Drivers
- 4.8.1 5G coverage expansion and FWA drives data-centric wallets
- 4.8.2 Fibre-backed FMC bundles boost fixed/mobile ARPU uplift
- 4.8.3 Video-streaming and cloud gaming fuel mobile data demand
- 4.8.4 Enterprise Industry 4.0 projects accelerate IoT SIM uptake
- 4.8.5 Release of 3.5 GHz spectrum for private 5G SA networks
- 4.8.6 eSIM-only handset channels reduce churn and acquisition cost
- 4.9 Market Restraints
- 4.9.1 Fierce price competition keeps blended ARPU flat
- 4.9.2 >110 % SIM penetration limits organic subscriber growth
- 4.9.3 Eco-design and energy-efficiency regulation lift opex
- 4.9.4 Uncertainty over mmWave auction timing delays capex plans
- 4.10 Technological Outlook
- 4.11 Analysis of key business models in Telecom Sector
- 4.12 Analysis of Pricing Models and Pricing
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 Overall Telecom Revenue and ARPU
- 5.2 Service Type
- 5.2.1 Voice Services
- 5.2.2 Data and Internet Services
- 5.2.3 Messaging Services
- 5.2.4 IoT and M2M Services
- 5.2.5 OTT and PayTV Services
- 5.2.6 Other Services (VAS, Roaming and International Services, Enterprise and Wholesale Services, etc.)
- 5.3 End-user
- 5.3.1 Enterprises
- 5.3.2 Consumer
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Investments by key vendors, 2023-2025
- 6.3 Market share analysis for MNOs, 2024
- 6.4 Product Benchmarking Analysis for mobile network services
- 6.5 MNO snapshot (subscribers, churn rate, ARPU, etc.)
- 6.6 Company Profiles* of MNOs (Includes Business Overview | Service Portfolio | Financials | Business Strategy and Recent Developments | SWOT Analysis)
- 6.6.1 Orange S.A.
- 6.6.2 SFR (Altice France)
- 6.6.3 Bouygues Telecom
- 6.6.4 Free Mobile (Iliad)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 中國行動網路業者(MNO):市佔率分析、產業趨勢與統計及成長預測(2026-2031)東協行動虛擬網路營運商:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)西班牙電信行動網路業者:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)馬來西亞電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)中東和非洲電信營運商(MNO):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)印度電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國電信行動網路業者:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)日本行動網路業者(MNO):市佔率分析、產業趨勢與統計及成長預測(2026-2031)美國行動網路營運商(MNO):市場佔有率分析、產業趨勢與統計數據、成長預測(2026-2031 年)義大利行動網路營運商(MNO):市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)