


 |
市場調查報告書
商品編碼
2120311
西班牙太陽能:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Spain Solar Energy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年西班牙太陽能市場規模為 47.95 吉瓦,預計到 2031 年將達到 85.77 吉瓦,而 2026 年為 52.83 吉瓦,預測期(2026-2031 年)的複合成長率為 10.18%。
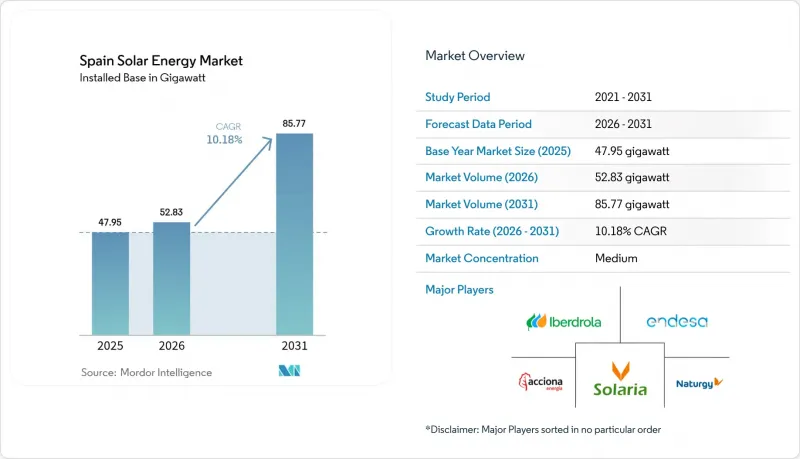
本報告按技術(太陽能和聚光太陽能)、併網類型(併網和離網)以及最終用戶(大型發電、商業和工業以及住宅)進行分類。市場規模和預測以裝置容量(GW)為單位。
西班牙太陽能市場趨勢與洞察
降低公用事業規模太陽能組件的成本
由於全球供應過剩,組件價格持續下降,使得卡斯蒂利亞-拉曼恰和埃斯特雷馬杜拉的計畫即使在土地品質較低的地區也能實現具有競爭力的平準化發電成本。雙面組件與單軸追蹤器的組合,如今可實現超過25%的容量係數,從而擴大了大規模地面光電站的經濟適用性。道達爾能源等國際電力公司報告稱,與2023年的數據相比,資本支出成本最多可降低15%。成本持平的實現正在加速與電池儲能的混合應用,因為節省下來的資金可以重新分配到系統平衡(BOS)升級和能源管理軟體方面。當地工程公司報告稱,系統設計正顯著轉向1500VDC,這可以減少電纜損耗和人工成本。因此,西班牙太陽能市場的潛力正在擴展到以前經濟上無利可圖的地區。
歐盟「Fit-for-55」和「REPowerEU」合規期限
具有法律約束力的2030年脫碳目標為開發商提供了監管確定性,加快了他們參與競標和資金籌措的步伐。西班牙在2024年批准了22,326兆瓦的太陽能發電項目,並在2025年第一季批准了另外3,019兆瓦。監管政策的協調一致也延伸到了儲能領域,用戶側儲能電池現在可以獲得容量獎勵,從而改善了分散式資產的現金流量。地方政府也與國家政策保持一致,安達盧西亞自治區政府正在加快推進一個1.4吉瓦計畫的併網程序,該計畫於2025年投入使用。清晰的政策規劃最大限度地降低了市場價格風險,並吸引了外國直接投資進入西班牙的太陽能市場。
與 Natura 2000 保護區的土地利用衝突
西班牙約30%的國土被劃為保護區,用地面積超過5公頃的計畫必須進行全面的環境影響評估。光是在穆爾西亞,到2030年就計畫興建3萬公頃的太陽能發電設施,其中60%是以前的農田,面臨農業合作社的強烈反對。開發商擴大將目光投向廢棄礦場等棕地,導致每兆瓦的土壤修復成本增加5萬至10萬歐元。專案集中在衝突較少的地區,導致發電能力集中在本就電力網路脆弱的地區,增加了限電的風險。
細分市場分析
到2025年,太陽能將佔西班牙太陽能市場的94.45%,預計到2031年將以10.45%的複合年成長率成長。同時,西班牙國家太陽能委員會(PNIEC)已將聚光型太陽熱能發電(CSP)的目標下調至4.8吉瓦。由於鋰離子電池的成本在2024年將降至140美元/千瓦時以下,且其儲能能力僅為熔鹽系統的一半,能夠儲存2-4小時的能量,因此開發商正優先考慮將太陽能與電池儲能相結合的混合系統。預計2025年至2030年間,西班牙新增太陽能裝置容量將超過31吉瓦。
聚光型太陽熱能發電(CSP)目前仍以每兆瓦時20-50歐元的價格供應工業過程熱,比價格波動較大的天然氣便宜。西班牙目前擁有2.3吉瓦的在運作中CSP電站。然而,2024年沒有新的公用事業規模CSP專案完成融資。隨著電力公司將資金重新分配給採用n型電池的雙面太陽能發電(效率可提高10-15%),預計CSP的市佔率將進一步下降。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 降低大型太陽能模組的成本
- 歐盟「Fit-for-55」和「REPowerEU」合規期限
- IBEX-35 成分股公司之間的公司間購電協議 (PPA) 激增
- 併網電池混合動力系統可提高專案內部報酬率
- 乾旱地區(安達盧西亞、卡斯蒂利亞-拉曼查)農業太陽能(Agri-PV)激勵措施
- 自給自足型消費合作社(autoconsumo colectivo)的快速成長
- 人工智慧驅動的最佳化調度正在提高營運商的收入。
- 市場限制因素
- 與 Natura 2000 保護區的土地利用衝突
- 在太陽輻射強度高的地區,逆變器飽和可能導致輸出功率下降。
- 第二天,泳池邊出現了幅度很大的自相殘殺式折扣。
- 從地方政府獲得雙軸追蹤器許可證的過程耗時很長。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- PESTLE分析
第5章 市場規模與成長預測
- 透過技術
- 太陽能(光伏)
- 聚光太陽能(CSP)
- 按電網連接類型
- 併網
- 離網
- 最終用戶
- 公用事業規模
- 商業和工業(C&I)
- 住宅
- 按組件
- 太陽能模組/面板
- 逆變器(組串式、集中式、微型)
- 安裝和追蹤系統
- 系統平衡和電氣設備
- 儲能和混合整合
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Iberdrola SA
- Acciona Energia
- Endesa(Enel Group)
- Solaria Energia y Medio Ambiente SA
- Repsol SA
- Engie Espana
- Naturgy Renovables
- Gransolar Group
- Soltec Power Holdings
- Cobra IS(ACS Group)
- RIC Energy
- Forestalia Renovables
- Prodiel
- Powertis(SPIC)
- Q-Energy
- X-Elio
- Opdenergy
- TotalEnergies Renewables Espana
- Sonnedix
- Fit Energy
第7章 市場機會與未來展望
According to Mordor Intelligence, the Spain solar energy market size was valued at 47.95 gigawatt in 2025 and estimated to grow from 52.83 gigawatt in 2026 to reach 85.77 gigawatt by 2031, at a CAGR of 10.18% during the forecast period (2026-2031).
This report is Segmented by Technology (Solar Photovoltaic and Concentrated Solar Power), Grid Type (On-Grid and Off-Grid), and End-User (Utility-Scale, Commercial and Industrial, and Residential). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
Spain Solar Energy Market Trends and Insights
Declining cost of utility-scale PV modules
Module prices continue to fall due to global oversupply, allowing projects in Castilla-La Mancha and Extremadura to reach competitive levelized costs even on lower-grade land. Bifacial panels paired with single-axis trackers now achieve capacity factors above 25%, widening the economic envelope for large ground-mounted plants. International utilities such as TotalEnergies cite capex savings of up to 15% compared with 2023 figures. Cost parity encourages hybridization with battery storage because freed capital can be reallocated to balance-of-system upgrades and energy management software. Local engineering firms report a notable shift toward 1,500 VDC system designs that cut cable losses and labor inputs. The net effect is an enlarged Spain solar energy market pipeline in regions previously on the economic margin.
EU Fit-for-55 & REPowerEU Compliance Deadlines
Binding 2030 decarbonization targets give developers regulatory certainty, accelerating auction participation and bankability. Spain authorized 22,326 MW of PV construction in 2024 and cleared an additional 3,019 MW in Q1 2025. Regulatory alignment extends to storage: behind-the-meter batteries now qualify for capacity revenues, improving cash flows for distributed assets. Regional authorities echo the national stance; the Junta de Andalucia fast-tracked grid interconnection for 1.4 GW of projects in 2025. Clear policy timelines minimize merchant-price risk, drawing foreign direct investment into the Spain solar energy market.
Land-Use Conflicts with Natura-2000 Conservation Areas
Protected zones cover about 30% of Spain and trigger full environmental impact studies for any project footprint larger than 5 hectares. Murcia alone plans 30,000 ha of PV by 2030, yet 60% lies on former cropland that faces organized opposition from farm cooperatives. Developers increasingly target brownfield sites such as disused mines, adding EUR 50,000-100,000/MW in remediation costs. Concentration in low-conflict land funnels capacity into regions already constrained by weak transmission, thereby amplifying curtailment risk.
Other drivers and restraints analyzed in the detailed report include:
- Corporate PPA Boom Among IBEX-35 Firms
- Grid-Connected Battery Hybrids Enhancing Project IRR
- Curtailment Risk from Inverter Saturation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solar photovoltaic commanded 94.45% of the Spain solar energy market in 2025 and is expanding at a 10.45% CAGR to 2031, whereas CSP's PNIEC target has fallen to 4.8 GW. Lithium-ion batteries cost below USD 140/kWh in 2024 and enable two-to-four-hour storage at half the cost of molten-salt systems, so developers prioritise PV-plus-battery hybrids. Spain's solar energy market size for photovoltaic additions will therefore increase by more than 31 GW between 2025 and 2030.
CSP still offers industrial process heat at EUR 20-50/MWh, cheaper than volatile natural gas prices, and Spain hosts 2.3 GW of operating plants. Yet no new utility-scale CSP projects reached financial close in 2024. As utilities redeploy capital into bifacial PV with n-type cells that lift yield by 10-15%, CSP's share will shrink further.
Complete Report Scope:
- By Technology
- Solar Photovoltaic (PV)
- Concentrated Solar Power (CSP)
- By Grid Type
- On-Grid
- Off-Grid
- By End-User
- Utility-Scale
- Commercial and Industrial (C&I)
- Residential
- By Component (Qualitative Analysis)
- Solar Modules/Panels
- Inverters (String, Central, Micro)
- Mounting and Tracking Systems
- Balance-of-System and Electricals
- Energy Storage and Hybrid Integration
List of Companies Covered in this Report:
- Iberdrola SA
- Acciona Energia
- Endesa (Enel Group)
- Solaria Energia y Medio Ambiente SA
- Repsol SA
- Engie Espana
- Naturgy Renovables
- Gransolar Group
- Soltec Power Holdings
- Cobra IS (ACS Group)
- RIC Energy
- Forestalia Renovables
- Prodiel
- Powertis (SPIC)
- Q-Energy
- X-Elio
- Opdenergy
- TotalEnergies Renewables Espana
- Sonnedix
- Fit Energy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining cost of utility-scale PV modules
- 4.2.2 EU Fit-for-55 & REPowerEU compliance deadlines
- 4.2.3 Corporate PPA boom among IBEX-35 firms
- 4.2.4 Grid-connected battery hybrids enhancing project IRR
- 4.2.5 Agri-PV incentives in drought-stricken regions (Andalucia, Castilla-La Mancha)
- 4.2.6 Surge in self-consumption cooperatives (autoconsumo colectivo)
- 4.2.7 AI-optimised dispatch lifting merchant revenue capture
- 4.3 Market Restraints
- 4.3.1 Land-use conflicts with Natura-2000 conservation areas
- 4.3.2 Curtailment risk from inverter saturation in high-irradiance provinces
- 4.3.3 Volatile cannibalisation discounts in day-ahead pool
- 4.3.4 Lengthy municipal permitting for 2-axis trackers
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Solar Photovoltaic (PV)
- 5.1.2 Concentrated Solar Power (CSP)
- 5.2 By Grid Type
- 5.2.1 On-Grid
- 5.2.2 Off-Grid
- 5.3 By End-User
- 5.3.1 Utility-Scale
- 5.3.2 Commercial and Industrial (C&I)
- 5.3.3 Residential
- 5.4 By Component (Qualitative Analysis)
- 5.4.1 Solar Modules/Panels
- 5.4.2 Inverters (String, Central, Micro)
- 5.4.3 Mounting and Tracking Systems
- 5.4.4 Balance-of-System and Electricals
- 5.4.5 Energy Storage and Hybrid Integration
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Iberdrola SA
- 6.4.2 Acciona Energia
- 6.4.3 Endesa (Enel Group)
- 6.4.4 Solaria Energia y Medio Ambiente SA
- 6.4.5 Repsol SA
- 6.4.6 Engie Espana
- 6.4.7 Naturgy Renovables
- 6.4.8 Gransolar Group
- 6.4.9 Soltec Power Holdings
- 6.4.10 Cobra IS (ACS Group)
- 6.4.11 RIC Energy
- 6.4.12 Forestalia Renovables
- 6.4.13 Prodiel
- 6.4.14 Powertis (SPIC)
- 6.4.15 Q-Energy
- 6.4.16 X-Elio
- 6.4.17 Opdenergy
- 6.4.18 TotalEnergies Renewables Espana
- 6.4.19 Sonnedix
- 6.4.20 Fit Energy
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 印度太陽能:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)太陽能:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)義大利太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)菲律賓太陽能:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)印尼太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)中國太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)德國太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)日本太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)法國太陽能:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)泰國太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)