


 |
市場調查報告書
商品編碼
2121563
馬來西亞電力:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Malaysia Power - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,馬來西亞電力市場規模在 2026 年將達到 42.79 吉瓦,高於 2025 年的 40.27 吉瓦,預計到 2031 年將達到 57.97 吉瓦。
預計從 2026 年到 2031 年,其複合年成長率將達到 6.26%。
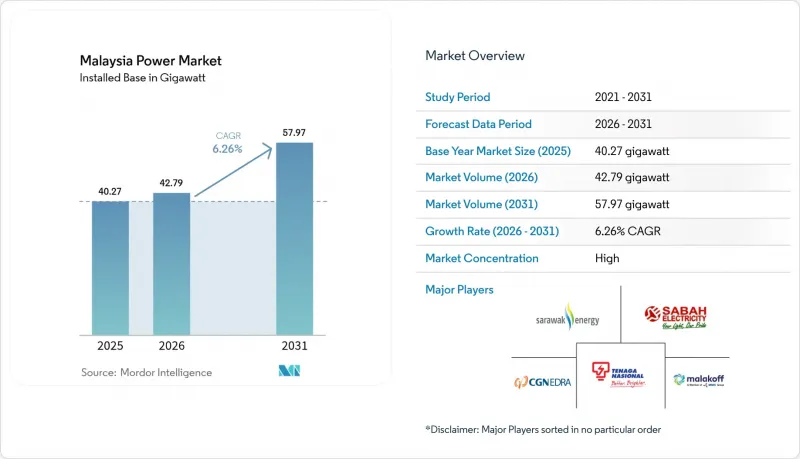
本報告按能源類型(火力發電、核能、可再生能源)和終端用戶(公用事業、商業/工業、居民)進行細分。市場規模和預測以裝置容量(吉瓦)為單位。
馬來西亞電力市場趨勢與分析
工業用電需求激增
英飛凌在居林投資20億歐元建設的碳化矽晶圓廠,象徵馬來西亞電力市場結構從傳統的石化產業向精密製造業的轉型,而精密製造業如今已成為馬來西亞電力市場的支柱。馬來西亞國家能源公司(TNB)已確認,僅資料中心用電量就將達到總合吉瓦,這迫使該公司預留了163億馬幣有條件資本投資的30%,以應對可能出現的負載激增。預計到2030年,工業需求仍將佔總用電量的一半,但其結構正在轉變為半導體和雲端運算等需要低碳電力的工作負載。發電和輸電網建設的延誤可能導致這些投資被擁有更先進可再生能源採購框架的區域競爭對手搶走。因此,地方政府正在加速變電站升級改造,並鼓勵部署電池儲能系統,以維持充足的備用容量。
可再生能源容量目標
國家能源轉型藍圖設定了2025年可再生能源發電裝置容量佔比達到31%,2035年達到40%的目標。要達成這些目標需要每年新增約1.5吉瓦的裝置容量,遠超過以往的建造速度。在2024年第五輪大型太陽能發電項目競標中,2吉瓦的裝置容量分配給了馬來西亞本土競標,優先考慮國內項目,同時也縮小了開發商的選擇範圍。國家能源公司(TNB)在水力發電水庫上建造的2.5吉瓦浮體式太陽能發電專案利用了現有的輸電線路,最大限度地減少了土地使用衝突。同時,砂拉越能源公司7,300兆瓦的水力發電廠將使東馬成為潛在的清潔電力出口地,前提是跨境輸電網連接已經建立。 2050年實現70%的可再生能源目標意味著幾乎要淘汰燃煤電廠,而與氫能相容的聯合循環燃氣燃氣渦輪機有望成為過渡技術,但燃料供應仍存在不確定性。
天然氣供應限制和價格波動
國內天然氣產量已趨於穩定,而馬來西亞國家石油公司(Petronas)優先發展液化天然氣(LNG)出口,導致週期性燃料短缺,迫使發電企業轉而使用成本更高的柴油作為備用電源。 2022年全球LNG價格飆升時,馬來西亞的定價機制未能跟上燃料成本上漲的步伐,擠壓了獨立發電公司(IPP)的利潤空間。規劃中的氫能燃氣渦輪機是基於綠色氫氣將逐步取代天然氣的假設,但工業規模的氫能基礎設施仍處於起步階段。除非在儲能、進口和定價方面進行協調一致的改革,否則對天然氣的依賴將抑制投資者對更柔軟性的火力發電資產的興趣,並減緩馬來西亞電力市場的擴張步伐。
細分市場分析
預計到2025年,馬來西亞可再生能源市場將以22.89%的複合年成長率成長,這將削弱目前佔馬來西亞電力市場74.92%的火力發電佔有率。太陽能發電是推動可再生能源蓬勃發展的主要動力,這得益於國家能源公司(TNB)推出的2.5吉瓦浮體式太陽能發電項目,以及透過「第五輪大型太陽能發電項目招標」分配的2吉瓦裝置容量。水力發電在馬來西亞東部仍然十分重要,但其擴張受到環境評估和與當地社區對話的限制。燃煤電廠預計將大幅減少,到2030年將有9.1吉瓦的裝置容量被淘汰,儘管與氫能相容的燃氣渦輪機正在提高電力儲備,並為電網未來的燃料轉型做好準備。電池儲能的引入是關鍵因素。充足的儲能容量可以提高太陽能發電的普及率,而容量不足則會延長中功率燃氣電廠的運作時間。
即使在儲能設施投入使用之前,到2024年,太陽能發電的平準化成本就已低於天然氣發電的邊際成本,這促使獨立發電商(IPP)除了與電力公司競標外,還積極簽訂企業購電協議(PPA)。砂拉越的水力發電資產以較低的可變成本提供接近基本負載的電力,一旦併網,該州有望成為潛在的電力出口目的地。風能和地熱發電仍處於試驗階段,而生質能發電的擴張則因原料價格飆升而放緩。這些電力結構的變化將影響馬來西亞整體電力市場的發電順序、排放強度和投資分配。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 工業用電需求激增
- 可再生能源發電裝置容量目標(2025年達31%,2035年達40%)
- 隨著老舊燃煤發電廠的退役,替代電廠的建設正在快速前進。
- 電力傳輸和分配網路現代化以及擴大電力傳輸和分配領域的資本投資。
- 第三方准入法規使得公司之間能夠簽訂購電協議(PPA)。
- 超大規模資料中心叢集造成負載集中。
- 市場限制因素
- 天然氣供應限制和價格波動
- 電費補貼改革
- 大型可再生能源專案面臨的土地和授權挑戰
- 東馬來西亞脆弱的電網面臨發電能力受限的風險
- 供應鏈分析
- 監理情勢
- 技術趨勢(智慧電網、氫能相容型燃氣聯合循環發電廠、電池儲能系統)
- 波特五力模型
- PESTLE分析
第5章:預測市場規模與成長率
- 透過電源
- 火力發電(煤炭、天然氣、石油和天然氣、柴油)
- 核能
- 可再生能源(太陽能、風能、水能、地熱能、生質能/廢棄物、潮汐能)
- 最終用戶
- 公用事業
- 商業和工業用途
- 家用
- 輸配電電壓等級(僅定性分析)
- 高壓輸電(230千伏特或以上)
- 次級輸電(69-161千伏特)
- 中壓配電(13.2–34.5 kV)
- 低壓配電(1千伏特或以下)
第6章 競爭情勢
- 市場集中度
- 策略趨勢(企業合併、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Tenaga Nasional Berhad(TNB)
- Sarawak Energy Berhad
- Sabah Electricity Sdn Bhd(SESB)
- Edra Power Holdings
- Malakoff Corporation Berhad
- YTL Power International
- Genting Sanyen Power
- Petronas Power Sdn Bhd
- Cypark Resources Berhad
- Solarvest Holdings Berhad
- ERS Energy Sdn Bhd
- Verdant Solar
- LYS Energy Group
- Pathgreen Energy Sdn Bhd
- Sunway Construction Group Bhd(RE EPC)
- JinkoSolar(Malaysia Module Fab)
- First Solar Malaysia
- KEPCO Engineering & Construction
- Huawei Digital Power Malaysia
- Siemens Energy Malaysia
第7章 市場機會與未來展望
According to Mordor Intelligence, Malaysia power market size in 2026 is estimated at 42.79 gigawatt, growing from 2025 value of 40.27 gigawatt with 2031 projections showing 57.97 gigawatt, growing at 6.26% CAGR over 2026-2031.
This report is Segmented by Power Source (Thermal, Nuclear, and Renewables) and End-User (Utilities, Commercial and Industrial, and Residential). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
Malaysia Power Market Trends and Insights
Industrial Electricity-Demand Surge
Infineon's EUR 2 billion silicon-carbide fab in Kulim exemplifies the structural shift from legacy petrochemicals toward precision manufacturing that now underpins the Malaysian power market. TNB has confirmed that data-center applications alone total 11 GW, compelling the utility to reserve 30% of its RM 16.3 billion contingent capital expenditure for unanticipated load growth. Industrial demand is expected to maintain half of total consumption through 2030, but the composition tilts toward semiconductor and cloud workloads that require low-carbon electricity. Any lapse in generation or transmission build-out risks divesting these investments to regional competitors with more advanced renewable procurement frameworks. Consequently, local authorities are fast-tracking substation upgrades and incentivizing battery storage to keep reserve margins adequate.
Renewable-Energy Capacity Targets
The National Energy Transition Roadmap sets milestones of 31% renewable capacity by 2025 and 40% by 2035. Achieving these goals requires annual additions near 1.5 GW, notably faster than historical build-out rates. Large-Scale Solar Round 5 allocated 2 GW in 2024 to Malaysian-controlled bidders, favoring domestic content capture but narrowing the developer field. TNB's 2.5 GW floating-solar program across hydro reservoirs leverages existing transmission corridors and minimizes land-use conflicts, while Sarawak Energy's 7,300 MW hydro fleet positions East Malaysia as a potential clean-power exporter once cross-border interconnections advance. The 70% renewable aspiration by 2050 implies near-zero coal, with hydrogen-ready combined-cycle gas turbines providing a bridge technology, albeit with fuel-supply uncertainties.
Natural-Gas Supply Constraints and Price Volatility
Domestic gas production has plateaued, and Petronas prioritizes LNG exports, resulting in periodic fuel shortages that force generators to switch to costlier diesel back-up.When global LNG prices spiked in 2022, Malaysia's tariff-pass-through mechanism lagged fuel costs, compressing IPP margins. Planned hydrogen-ready turbines assume green hydrogen will gradually displace gas, yet industrial-scale hydrogen infrastructure remains nascent. Unless coordinated storage, import, and pricing reforms materialize, gas exposure will weigh on Malaysia's power market expansion speed by suppressing investor appetite for flexible thermal assets.
Other drivers and restraints analyzed in the detailed report include:
- Aging Coal-Fleet Retirements Triggering Replacement Build-Outs
- Hyperscale Data-Center Clusters Driving Load Pockets
- Electricity-Tariff Subsidy Reforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Malaysian power market size for renewables is projected to rise at a 22.89% CAGR, eating into thermal technology's 74.92% Malaysia power market share in Malaysia in 2025. Solar leads the renewable surge, propelled by TNB's 2.5 GW floating-solar roll-out and 2 GW of allocated capacity under Large-Scale Solar Round 5. Hydro remains pivotal in East Malaysia, yet expansion is bound by environmental assessment and community engagement. Coal will decline sharply, with 9.1 GW scheduled to retire by 2030, while hydrogen-ready gas turbines pick up reserve margins and prepare the grid for future fuel transitions. Battery storage adoption becomes a gating factor: adequate storage unlocks higher solar penetration, while shortfalls would keep mid-merit gas plants online longer.
Solar's levelized cost fell below marginal gas generation in 2024, even before storage, encouraging IPPs to stack corporate PPAs on top of utility tenders. Hydro assets in Sarawak supply near-baseload output at low variable cost, positioning the state as a potential exporter pending interconnection. Wind and geothermal remain exploratory, and biomass expansion slows due to rising feedstock prices. The evolving mix will influence dispatch order, emissions intensity, and investment allocation across the Malaysia power market.
Complete Report Scope:
- By Power Source
- Thermal (Coal, Natural Gas, Oil and Diesel)
- Nuclear
- Renewables (Solar, Wind, Hydro, Geothermal, Biomass & Waste, Tidal)
- By End User
- Utilities
- Commercial and Industrial
- Residential
- By T&D Voltage Level (Qualitative Analysis only)
- High-Voltage Transmission (Above 230 kV)
- Sub-Transmission (69 to 161 kV)
- Medium-Voltage Distribution (13.2 to 34.5 kV)
- Low-Voltage Distribution (Up to 1 kV)
List of Companies Covered in this Report:
- Tenaga Nasional Berhad (TNB)
- Sarawak Energy Berhad
- Sabah Electricity Sdn Bhd (SESB)
- Edra Power Holdings
- Malakoff Corporation Berhad
- YTL Power International
- Genting Sanyen Power
- Petronas Power Sdn Bhd
- Cypark Resources Berhad
- Solarvest Holdings Berhad
- ERS Energy Sdn Bhd
- Verdant Solar
- LYS Energy Group
- Pathgreen Energy Sdn Bhd
- Sunway Construction Group Bhd (RE EPC)
- JinkoSolar (Malaysia Module Fab)
- First Solar Malaysia
- KEPCO Engineering & Construction
- Huawei Digital Power Malaysia
- Siemens Energy Malaysia
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Industrial electricity-demand surge
- 4.2.2 Renewable-energy capacity targets (31 % by 2025; 40 % by 2035)
- 4.2.3 Aging coal-fleet retirements triggering replacement build-outs
- 4.2.4 Grid-modernisation & T&D capex push
- 4.2.5 Corporate PPAs enabled by Third-Party Access rules
- 4.2.6 Hyperscale data-centre clusters driving load pockets
- 4.3 Market Restraints
- 4.3.1 Natural-gas supply constraints & price volatility
- 4.3.2 Electricity-tariff subsidy reforms
- 4.3.3 Land & permitting hurdles for utility-scale RE
- 4.3.4 Curtailment risk in East-Malaysia weak grids
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (Smart grid, hydrogen-ready CCGT, BESS)
- 4.7 Porters Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Power Source
- 5.1.1 Thermal (Coal, Natural Gas, Oil and Diesel)
- 5.1.2 Nuclear
- 5.1.3 Renewables (Solar, Wind, Hydro, Geothermal, Biomass & Waste, Tidal)
- 5.2 By End User
- 5.2.1 Utilities
- 5.2.2 Commercial and Industrial
- 5.2.3 Residential
- 5.3 By T&D Voltage Level (Qualitative Analysis only)
- 5.3.1 High-Voltage Transmission (Above 230 kV)
- 5.3.2 Sub-Transmission (69 to 161 kV)
- 5.3.3 Medium-Voltage Distribution (13.2 to 34.5 kV)
- 5.3.4 Low-Voltage Distribution (Up to 1 kV)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Tenaga Nasional Berhad (TNB)
- 6.4.2 Sarawak Energy Berhad
- 6.4.3 Sabah Electricity Sdn Bhd (SESB)
- 6.4.4 Edra Power Holdings
- 6.4.5 Malakoff Corporation Berhad
- 6.4.6 YTL Power International
- 6.4.7 Genting Sanyen Power
- 6.4.8 Petronas Power Sdn Bhd
- 6.4.9 Cypark Resources Berhad
- 6.4.10 Solarvest Holdings Berhad
- 6.4.11 ERS Energy Sdn Bhd
- 6.4.12 Verdant Solar
- 6.4.13 LYS Energy Group
- 6.4.14 Pathgreen Energy Sdn Bhd
- 6.4.15 Sunway Construction Group Bhd (RE EPC)
- 6.4.16 JinkoSolar (Malaysia Module Fab)
- 6.4.17 First Solar Malaysia
- 6.4.18 KEPCO Engineering & Construction
- 6.4.19 Huawei Digital Power Malaysia
- 6.4.20 Siemens Energy Malaysia
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 電力零售:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)日本電力產業:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)歐洲電力市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)西班牙電力市場:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)電力:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)印度電力產業:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)義大利發電:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國電力市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)越南能源市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 電力零售市場-全球產業規模、佔有率、趨勢、機會和預測:按市場結構、客戶類型、服務類型、支付方式、地區和競爭格局分類,2021-2031年