


 |
市場調查報告書
商品編碼
2124707
西班牙電力市場:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Spain Power - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
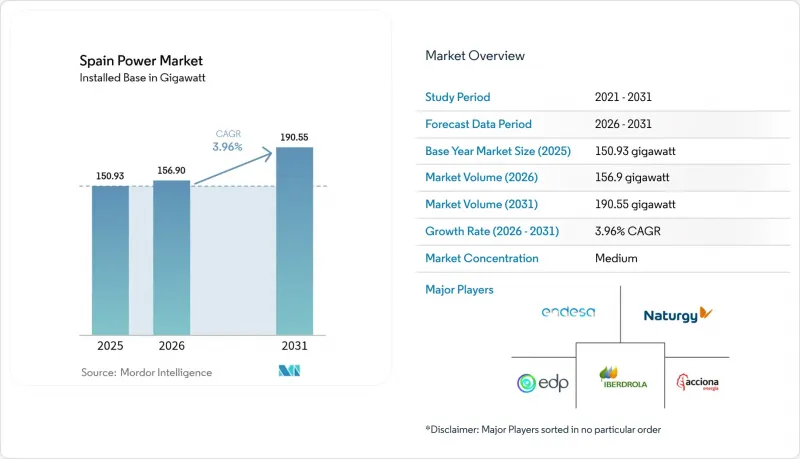
根據 Mordor Intelligence 預測,西班牙電力市場規模將從 2025 年的 150.93 吉瓦擴大到 2026 年的 156.9 吉瓦,然後從 2026 年到 2031 年以 3.96% 的複合年成長率成長,到 2031 年達到 190.190.
本報告按能源類型(火力發電、核能、可再生能源)、終端用戶(公共產業、商業/工業、住宅)以及輸配電電壓等級進行細分。市場規模和預測均以總容量(GW)為基礎。
西班牙電力市場趨勢與洞察
加速併網太陽能發電的推廣應用
2024年,西班牙太陽能發電產業迎來關鍵轉捩點,超越天然氣和風能,成為全國最大的能源來源。當局批准了2024年26,159.2兆瓦的可再生能源建設項目,其中太陽能發電項目佔22,326.1兆瓦。這主要歸功於成本降低、核准程序簡化以及企業對可再生能源認證(REC)需求的成長。卡斯蒂利亞-萊昂、阿拉貢和卡斯蒂利亞-拉曼恰大區由於日照條件優越且土地資源豐富,獲得了最大的配額。同樣,分散式屋頂太陽能發電系統在工業園區內迅速普及,有助於降低能源成本和範圍2排放。大型發電廠和現場發電設施的共同作用,正在提高可再生能源在西班牙電力市場的滲透率,使西班牙更容易實現2030年可再生能源佔比達到81%的目標。
超大規模資料中心的出現正在推動企業購電協定(PPA)的普及。
超大規模平台的需求正在改變西班牙電力市場的收入模式。谷歌簽署的35兆瓦風電購電協議(10年期)、亞馬遜承諾建設469兆瓦太陽能發電設施以及蘋果簽署的105兆瓦契約,都清晰地表明了電力市場正向開發商主導、以開發為導向的建設模式轉變。到2026年,資料中心容量可能達到600兆瓦,到2030年可能達到3000兆瓦,預計這將支撐數吉瓦級可再生資金籌措開發平臺。購電協議能夠提供穩定的現金流並降低資金籌措成本,這與超大規模企業的淨零排放策略相契合,並加速了電力裝置速度,遠超傳統公用事業公司的採購能力。
增加用於電網升級的資本支出
義大利電力公司(Red Electrica)已撥款65億歐元用於在2026年前加強電網建設,但預計到2030年需要100億歐元,這將導致35億歐元的資金缺口。由於電價上限將年漲幅限制在15%,成本回收受到阻礙。土地糾紛一直困擾著變電站的建設,15座400千伏變電站中有8座因法律糾紛延誤了兩年。鋼鐵和銅價上漲導致輸電線路建設成本從2020年的每公里120萬歐元上漲到2024年的每公里180萬歐元。如果不進行改革,到2028年,可再生能源發電發電量可能每年減少5太瓦時,太陽能發電的有效利用率可能降至22%。
細分市場分析
2025年,可再生能源裝置容量將佔西班牙總裝置容量的67.10%,年成長率達6.95%,西班牙清潔能源來源市場規模必將從2025年的101.27吉瓦成長到2031年的150.66吉瓦。 2025年1月,太陽能發電裝置容量達32.0吉瓦,與風電持平,超過風電。這主要得益於較低的競標價格和24%的產能利用率。改造現有風電場將提高陸域風電的發電效率,而無需佔用新的土地;同時,一項2吉瓦的浮體式海上風電租賃協議將充分利用尚未開發的海洋資源。水力發電裝置容量維持在17吉瓦的水平,但由於水庫水位下降,其抑低尖峰負載能力受到限制。隨著燃煤電廠在 2027 年逐步淘汰,尖峰負載將轉向燃氣電廠,可再生能源的免稅容量也將增加,在風能和太陽輻射較少的日子裡,備用容量將變得更加緊張。
到2025年,火電裝置容量在總裝置容量中的佔比將降至25.80%。恩德薩燃煤電廠的分階段關閉將減少2吉瓦的裝置容量和每年1,200萬噸的二氧化碳排放量。聯合循環燃氣發電的總裝置容量為24吉瓦,但由於可再生能源的擴張,運作時間正在減少,而混合儲能系統可實現4小時的輸出調整。核能發電在2035年之前將保持在7.1吉瓦的水平,但此後,電廠的關閉將造成50太瓦時的電力供應缺口,需要透過進口或電池儲能來填補。在循環經濟獎勵的推動下,預計到2030年,生質能發電裝置容量將從1.2吉瓦成長到1.8吉瓦。這些轉變凸顯了西班牙電力市場正在向脫碳技術轉型,儘管電網柔軟性方面的挑戰日益增加。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 併網太陽能發電的擴張正在加速。
- 1990年代和1921世紀初建造的風力發電廠發電量增加
- 參與企業超大規模資料中心市場的公司之間簽訂的購電協議(PPA)。
- 歐盟的「適合55歲族群」計畫和「國家能源與氣候計畫2030年」都要求實現脫碳。
- 交通和暖氣的快速電氣化
- 歐盟為跨境高壓直流輸電線路提供資金
- 市場限制因素
- 因電網升級而增加的資本支出(CAPEX)
- 從環境部門和地方當局獲得許可需要時間。
- 資源豐富地區電力生產限制風險增加
- 當地居民反對位置陸上風力發電廠。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- PESTLE分析
第5章 市場規模與成長預測
- 透過電源
- 火力發電(煤炭、天然氣、石油和天然氣、柴油)
- 核能
- 可再生能源(太陽能、風能、水力、地熱能、生質能/廢棄物、潮汐能)
- 最終用戶
- 公共產業
- 商業和工業
- 住宅
- 輸配電電壓等級(僅定性分析)
- 高壓輸電(230千伏以上)
- 半輸電線路(69-161千伏)
- 中壓配電(13.2–34.5 kV)
- 低壓配電(1千伏特或以下)
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Endesa SA
- Iberdrola SA
- Naturgy Energy Group SA
- EDP Group(EDP HC Energia)
- Acciona Energia
- Repsol Electricidad y Gas
- Grupo Red Electrica
- Siemens Gamesa Renewable Energy
- Nordex SE
- TotalEnergies SE
- Enel Green Power Espana
- Vestas Mediterranean
- ABO Wind AG
- Engie Espana
- Capital Energy
- Forestalia Renovables
- Grenergy Renovables
- Hive Energy Spain
- Solarpack Corporacion Tecnologica
第7章 市場機會與未來展望
According to Mordor Intelligence, the Spain power market size is expected to grow from 150.93 gigawatt in 2025 to 156.9 gigawatt in 2026 and is forecast to reach 190.55 gigawatt by 2031 at 3.96% CAGR over 2026-2031.
This report is Segmented by Power Source (Thermal, Nuclear, and Renewables) and End-User (Utilities, Commercial and Industrial, and Residential). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
Spain Power Market Trends and Insights
Accelerating Grid-Connected Solar PV Build-Out
Spain's solar segment set a watershed in 2024 when it overtook gas and wind as the country's top power source. Authorities cleared 26,159.2 MW of renewable construction in 2024, 22,326.1 MW of which is PV, underscoring cost declines, streamlined permitting, and corporate REC demand. Castilla y Leon, Aragon, and Castilla-La Mancha garnered the largest quotas, benefiting from superior irradiation and land availability. Distributed rooftop systems are likewise proliferating across industrial estates, cutting energy bills and Scope-2 emissions. Together, utility-scale and on-site arrays are raising the Spain electricity market's renewable penetration, easing compliance with the 81% green-power target for 2030.
Corporate PPAs Led by Hyperscale Data-Center Entrants
Demand from hyperscale platforms is reshaping revenue models in the Spain electricity market. Google's 35 MW, 10-year wind PPA, Amazon's 469 MW solar commitment, and Apple's 105 MW deal illustrate a shift toward developer-financed build-outs backstopped by tech majors. Data-center capacity could hit 600 MW in 2026 and 3,000 MW by 2030, sustaining multi-gigawatt renewable pipelines. PPAs provide bankable cash flows, lower financing costs, and dovetail with hyperscalers' net-zero strategies, accelerating installations beyond traditional utility procurement volumes.
Escalating Transmission Upgrade CAPEX
Red Electrica budgets EUR 6.5 billion for reinforcements through 2026, yet identifies a EUR 10 billion need by 2030, leaving a EUR 3.5 billion gap. Tariff caps limit annual hikes to 15%, throttling cost recovery. Substation builds face land disputes, with 8 of 15 400-kV facilities delayed two years by legal appeals. Steel and copper inflation pushed line costs from EUR 1.2 million /km in 2020 to EUR 1.8 million /km in 2024. Absent reform, 5 TWh of renewable output could be shed each year by 2028, trimming effective solar utilization to 22%.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Electrification of Mobility & Heating
- EU Fit-for-55 & NECP-2030 Decarbonisation Mandates
- Lengthy Environmental & Municipal Permitting
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Renewables accounted for 67.10% of installed capacity in 2025, and their 6.95% yearly advance ensures the Spain power market size for clean sources rises from 101.27 GW in 2025 to 150.66 GW in 2031. Solar photovoltaic eclipsed wind at 32.0 GW versus 32.0 GW in January 2025, propelled by low auction tariffs and 24% capacity factors. Repowering lifts onshore wind productivity without new land, while 2 GW of floating offshore leases open an untapped marine resource. Hydropower remains steady at 17 GW but suffers from lower reservoir levels that curb peak-shaving ability. Coal's exit by 2027 and gas's shift to peaking duty-free capacity for renewables will yet tighten reserve margins on low-wind, low-sun days.
Thermal fleets fell to 25.80% of capacity in 2025. Endesa's coal phase-out removed 2 GW, slashing 12 million tpy of CO2. Combined-cycle gas totals 24 GW but runs fewer hours as renewables scale, with hybrid storage enabling four-hour ramps. Nuclear stays flat at 7.1 GW through 2035, after which closures leave a 50 TWh gap to fill with imports or batteries. Biomass grows from 1.2 GW to a projected 1.8 GW by 2030 under circular-economy incentives. Together, this transformation underlines how the Spain power market pivots toward carbon-free technologies even as grid flexibility challenges mount.
Complete Report Scope:
- By Power Source
- Thermal (Coal, Natural Gas, Oil and Diesel)
- Nuclear
- Renewables (Solar, Wind, Hydro, Geothermal, Biomass & Waste, Tidal)
- By End User
- Utilities
- Commercial and Industrial
- Residential
- By T&D Voltage Level (Qualitative Analysis only)
- High-Voltage Transmission (Above 230 kV)
- Sub-Transmission (69 to 161 kV)
- Medium-Voltage Distribution (13.2 to 34.5 kV)
- Low-Voltage Distribution (Up to 1 kV)
List of Companies Covered in this Report:
- Endesa S.A.
- Iberdrola S.A.
- Naturgy Energy Group S.A.
- EDP Group (EDP HC Energia)
- Acciona Energia
- Repsol Electricidad y Gas
- Grupo Red Electrica
- Siemens Gamesa Renewable Energy
- Nordex SE
- TotalEnergies SE
- Enel Green Power Espana
- Vestas Mediterranean
- ABO Wind AG
- Engie Espana
- Capital Energy
- Forestalia Renovables
- Grenergy Renovables
- Hive Energy Spain
- Solarpack Corporacion Tecnologica
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating grid-connected solar PV build-out
- 4.2.2 Repowering of 1990s-2000s wind farms
- 4.2.3 Corporate PPAs led by hyperscale data-centre entrants
- 4.2.4 EU Fit-for-55 & NECP-2030 decarbonisation mandates
- 4.2.5 Rapid electrification of mobility & heating
- 4.2.6 EU funding for cross-border HVDC links
- 4.3 Market Restraints
- 4.3.1 Escalating transmission upgrade CAPEX
- 4.3.2 Lengthy environmental & municipal permitting
- 4.3.3 Rising curtailment risk in resource-rich regions
- 4.3.4 Local opposition to on-shore wind siting
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Power Source
- 5.1.1 Thermal (Coal, Natural Gas, Oil and Diesel)
- 5.1.2 Nuclear
- 5.1.3 Renewables (Solar, Wind, Hydro, Geothermal, Biomass & Waste, Tidal)
- 5.2 By End User
- 5.2.1 Utilities
- 5.2.2 Commercial and Industrial
- 5.2.3 Residential
- 5.3 By T&D Voltage Level (Qualitative Analysis only)
- 5.3.1 High-Voltage Transmission (Above 230 kV)
- 5.3.2 Sub-Transmission (69 to 161 kV)
- 5.3.3 Medium-Voltage Distribution (13.2 to 34.5 kV)
- 5.3.4 Low-Voltage Distribution (Up to 1 kV)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Endesa S.A.
- 6.4.2 Iberdrola S.A.
- 6.4.3 Naturgy Energy Group S.A.
- 6.4.4 EDP Group (EDP HC Energia)
- 6.4.5 Acciona Energia
- 6.4.6 Repsol Electricidad y Gas
- 6.4.7 Grupo Red Electrica
- 6.4.8 Siemens Gamesa Renewable Energy
- 6.4.9 Nordex SE
- 6.4.10 TotalEnergies SE
- 6.4.11 Enel Green Power Espana
- 6.4.12 Vestas Mediterranean
- 6.4.13 ABO Wind AG
- 6.4.14 Engie Espana
- 6.4.15 Capital Energy
- 6.4.16 Forestalia Renovables
- 6.4.17 Grenergy Renovables
- 6.4.18 Hive Energy Spain
- 6.4.19 Solarpack Corporacion Tecnologica
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 電力零售:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)日本電力產業:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)歐洲電力市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)電力:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)印度電力產業:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)馬來西亞電力:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)義大利發電:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國電力市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)越南能源市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 電力零售市場-全球產業規模、佔有率、趨勢、機會和預測:按市場結構、客戶類型、服務類型、支付方式、地區和競爭格局分類,2021-2031年