


 |
市場調查報告書
商品編碼
2119005
OTT機上盒:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)OTT Set-Top Box - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年 OTT 機上盒市值為 48.4 億美元,預計到 2031 年將從 2026 年的 52.3 億美元成長至 79.1 億美元,預測期(2026-2031 年)的複合年成長率為 8.63%。
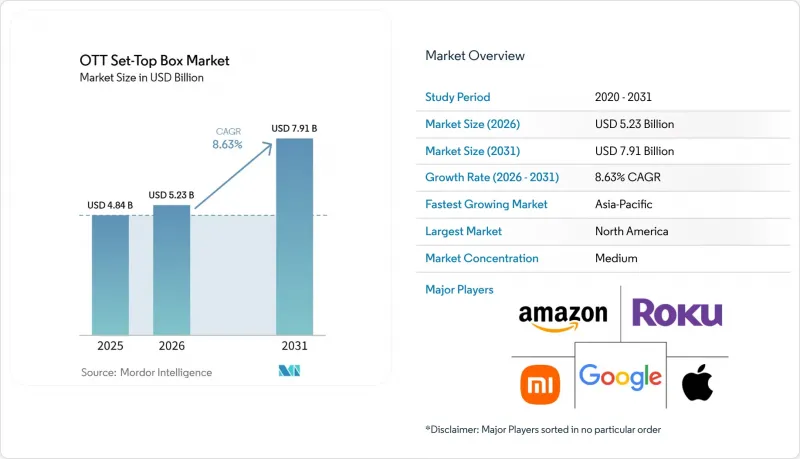
本報告按產品類型(僅支援IP/OTT的機上盒、混合型廣播/OTT機上盒)、作業系統和平台(Android TV和Google TV、RDK、專有消費者平台等)、銷售管道(零售商、電信業者、寬頻業者、付費電視業者等)以及地區(北美、南美等)進行細分。市場預測以美元計價。
全球OTT機上盒市場趨勢與洞察
「停掉有線電視服務」現像以及向靈活串流媒體聚合的轉變
傳統付費電視的衰退正在推動OTT機上盒市場的硬體更換需求。 VAB預測,到2026年底,美國將有8070萬戶家庭成為“剪線族”(cord-cutters)或“從未訂閱過有線電視的用戶”,首次超過付費電視用戶數量。對於那些需要管理多個訂閱服務的家庭來說,他們可能更傾向於使用中立的內容發現平台,而不是電視製造商優先展示自身廣告和內容的介面。這種需求衝突正在推動對能夠將服務、搜尋和收費整合到單一體驗中的獨立設備平台的需求。隨著聚合服務越來越受到用戶的信任,並能影響用戶的消費和日常觀看選擇,OTT機上盒市場也將從中受益。
光纖和 5G 固定無線網路的擴展,實現了高品質的 OTT 傳輸。
網路容量是高碼率串流媒體播放的關鍵需求,因此光纖和固定無線存取的日益普及將擴大OTT機上盒市場的潛在基本客群。根據愛立信統計,截至2026年6月,71%的固定無線接取服務供應商已透過5G網路提供服務,其中394家業者已實現5G固定無線服務的商用部署。該公司預測,到2031年,全球固定無線用戶將達到3.5億。 2026年第一季,行動和固定無線網路流量年增22%,其中大部分成長來自印度和北美。固定無線網路還可以服務於人口稀少的郊區和農村地區,在這些地區鋪設光纖在經濟上不可行。這些家庭可能正在從直播衛星電視(DTH)或DSL設備升級到能夠處理4K服務的基於IP的設備。
智慧電視的普及導致對專用OTT硬體的需求下降。
智慧電視的普及性降低了對基礎串流媒體棒和入門級OTT機上盒的需求。售價低於250美元的入門級機型通常內建Android TV原生功能,因此當家庭更換電視時,無需再單獨購買設備。自2019年以來,「Shield TV」一直沒有硬體更新,這表明,當低價智慧電視提供類似的作業系統功能時,高階Android TV盒子的銷售面臨挑戰。獨立設備最吸引人的應用場景仍然是聚合高階體育賽事直播,這可能需要全屋物聯網控制、60fps杜比視界以及更高的處理能力和連接性。大眾市場電視內建的晶片組並不一定優先考慮這些功能。因此,智慧電視的更迭對中階設備的影響最大,而非高階營運商級設備。
細分市場分析
預計到2025年,專用IP/OTT設備將佔OTT機上盒市場62.15%的佔有率,並將在2031年之前以9.21%的複合年成長率成長。這是規模最大且成長最快的產品類型,顯示西歐和南美正在加速全IP轉型。透過取消DVB-T2、DVB-S2和ISDB-T調諧器,製造商可以將晶片產能重新分配到AV1解碼、硬體DRM和Wi-Fi 6E上。這種設計為OTT機上盒市場提供了一條清晰的路徑,使其能夠在相近的價格水平上與整合式電視軟體競爭。此外,它還減少了長期在同一機箱內維護廣播和IP功能的必要性。
在2025年IBC展會上,創維和晶晨聯合發布了一款面向營運商的4K安卓電視設備,該設備採用6奈米系統晶片(SoC),支援手勢控制、邊緣AI和攝影機功能,可用於健身應用。這些功能較適合純IP設計,而非混合廣播底盤。在需要地面電波或衛星廣播連續性的地區,例如北美遍遠地區、南歐以及巴西的TV 3.0過渡區,混合設備仍然至關重要。雖然大規模營運商正在採用支援空中升級的雲端管理IP設備,但雲端容量有限的區域營運商仍繼續使用混合設備來維持訊號連續性。美國導航法規支援可互通的客戶設備,並優先考慮經過認證的平台,而非封閉的傳統設計。
區域分析
2025年,北美佔據了全球OTT機上盒市場43.58%的佔有率。這主要得益於高昂的售價、成熟的串流平台以及大規模的「停掉有線電視服務族」(放棄有線電視的用戶群)。根據Roku 2025年年度報告,其營收預計達到47.4億美元,淨利為8,840萬美元,自由現金流也將創歷史新高。這表明,北美領先的OTT平台並非依靠設備利潤率,而是依靠平臺本身的獲利能力。 2026年6月,福斯宣布提案以220億美元收購Roku,該交易尚需獲得監管部門批准,預計於2027年上半年完成。如果提案成功,Roku的聯網電視平台將整合Tubi和福斯的內容,從而加劇與亞馬遜Fire TV、Google電視和蘋果電視的競爭。在加拿大,由寬頻支援的成熟的OTT基礎設施已經建立;而在墨西哥,隨著光纖擴展到區域城市,DTH(直播到戶)衛星廣播正在轉變為IPTV和寬頻服務。
亞太地區預計將成為成長最快的地區,到2031年複合年成長率將達到9.06%。在印度,JioFiber的擴張以及Airtel Xstream的配套服務正推動家庭用戶從傳統的直播衛星電視(DTH)設備轉向支援IP的串流媒體設備,該國的寬頻用戶數量預計將從2025年的7億成長到2030年的11億以上。中國擁有最多的IPTV用戶,預計2030年將達到5億至5.5億戶家庭,但由於工信部(MIIT)的認證和GB硬體標準,需求正轉向國內供應商和串流媒體服務。東南亞是一個快速成長的地區,2026年5月對「MyIPTV4K」的打擊表明,認證設備有助於打擊盜版。這些因素使得亞太地區成為OTT機上盒市場的重要擴張區域。
在歐洲,隨著Android TV營運商層級和RDK的引進,現代化進程正在推進。挪威電信(Telenor)於2026年1月在挪威推出的「T-We Boxes III」為覆蓋挪威、瑞典和芬蘭的整個北歐地區的服務部署奠定了基礎。在南美洲,隨著巴西持續推動數位轉型,銷售額穩定成長。 2026年5月,中興通訊(ZTE)和Claro聯合推出了“Z4KW6”,這是一款支援4K超高清影片、語音控制、Wi-Fi和本地串流媒體存取的IPTV機上盒。中東和非洲市場規模雖小,但隨著沙烏地阿拉伯光纖到戶(FTTH)網路的擴展以及電信營運商部署支援IPTV的設備,該市場正在蓬勃發展。隨著串流媒體用戶數量的成長以及對支援影片管理傳輸的設備的需求增加,預計這些地區的OTT機上盒市場將持續成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 停掉有線電視服務和向靈活的串流聚合服務過渡
- 光纖和5G固定無線網路的擴展將實現高品質的OTT傳輸。
- 快速和混合直播電視體驗的成長
- 4K、HDR、杜比音效和高級體育串流升級
- 電信業者部署 Android TV、RDK 和雲端管理 CPE。
- 智慧家庭中心的整合為電視螢幕帶來了新的效用。
- 市場限制因素
- 智慧電視的普及性降低了對專用OTT硬體的需求。
- 設備更換週期延長,零售價格下降。
- 每個市場的內容版權、數位版權管理 (DRM) 和身分驗證的複雜性。
- 水貨IPTV機上盒和網路安全的信任缺失。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 依產品類型
- IP/OTT專用機上盒
- 混合廣播和OTT機上盒
- 按作業系統和平台
- Android TV 和 Google TV
- RDK
- 專有消費者平台
- 其他作業系統和平台
- 透過分銷管道
- 零售
- 電信業者、寬頻業者、付費電視業者
- 分銷商和系統整合商
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- Vendor Positioning Analysis
- 公司簡介
- Roku, Inc.
- Amazon.com, Inc.
- Apple Inc.
- Google LLC
- Samsung Electronics Co., Ltd.
- Vantiva SA
- SAGEMCOM Broadband SAS
- Skyworth Digital Technology Co., Ltd.
- Huawei Technologies Co., Ltd.
- ZTE Corporation
- Humax Co., Ltd.
- CommScope Holding Company, Inc.
- Kaonmedia Co., Ltd.
- Shenzhen SDMC Technology Co., Ltd.
- Xiaomi Corporation
- Comcast Corporation
- Netgem SA
- Vestel Elektronik Sanayi ve Ticaret AS
第7章 市場機會與未來展望
According to Mordor Intelligence, the OTT set-Top box market size was valued at USD 4.84 billion in 2025 and is estimated to grow from USD 5.23 billion in 2026 to reach USD 7.91 billion by 2031, at a CAGR of 8.63% during the forecast period (2026-2031).
This report is Segmented by Product Type (IP/OTT-Only Set-Top Boxes, and Hybrid Broadcast-OTT Set-Top Boxes), Operating System and Platform (Android TV and Google TV, RDK, Proprietary Consumer Platforms, and More), Distribution Channel (Retail, Telecom, Broadband, and Pay-TV Operators, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global OTT Set-Top Box Market Trends and Insights
Cord-Cutting and Migration to Flexible Streaming Aggregation
The shift away from traditional pay television is driving demand for hardware replacements in the OTT set-top box market. The VAB projected that 80.7 million U.S. households would be cord-cutters or cord-nevers by the end of 2026, exceeding pay-TV subscribers for the first time. Households that manage multiple subscriptions can seek a neutral discovery layer instead of a television-maker interface that also prioritizes its own advertising and content arrangements. That tension supports independent device platforms that can combine services, search, and billing into a single experience. The OTT set-top box market can benefit when aggregation is trusted enough to influence subscriber spending and daily viewing choices.
Fiber and 5G Fixed Wireless Expansion Enabling High-Quality OTT Delivery
Network capacity is a basic requirement for high-bitrate streaming, so broader fiber and fixed wireless access expand the addressable base for the OTT set-top box market. Ericsson reported that 71% of fixed wireless access service providers delivered services over 5G in June 2026, and that 394 operators had commercially launched 5G fixed wireless services. The company expects global fixed wireless subscriptions to reach 350 million by 2031. Mobile and fixed wireless network traffic rose 22% year over year in the first quarter of 2026, with India and North America providing much of the increase. Fixed wireless can reach lower-density suburban and rural locations where fiber deployment is less economical. Those households may upgrade from satellite direct-to-home or DSL equipment to IP-based devices that can support 4K services.
Smart Televisions Reducing the Need for Dedicated OTT Hardware
Smart television adoption reduces demand for basic streaming dongles and entry-level OTT set-top boxes. Native Android TV features are included in entry-level panels priced below USD 250, eliminating the need for a separate device when households replace their television. The lack of a Shield TV hardware refresh since 2019 shows the difficulty of selling a premium Android television box when a lower-priced smart television provides comparable operating system functions. The strongest standalone use cases remain whole-home IoT control, Dolby Vision at 60 frames per second, and premium sports aggregation that may require more capable processing and connectivity. Integrated television chipsets do not always prioritize these functions in mass-market panels. As a result, smart television substitution places the greatest pressure on mid-range devices rather than on premium operator equipment.
Other drivers and restraints analyzed in the detailed report include:
- Growth of FAST and Hybrid Live-TV Experiences
- 4K, HDR, Dolby Audio, and Premium Sports Streaming Upgrades
- Long Device Replacement Cycles and Retail Price Erosion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IP/OTT-only equipment accounted for 62.15% of the OTT set-top box market size in 2025 and is projected to grow at a 9.21% CAGR through 2031. It was both the largest and fastest-growing product category, suggesting faster full-IP migration in Western Europe and South America. Removing DVB-T2, DVB-S2, and ISDB-T tuners lets manufacturers direct silicon capacity toward AV1 decoding, hardware DRM, and Wi-Fi 6E. This design gives the OTT set-top box market a clearer way to compete with integrated television software at similar prices. It also reduces the need to maintain broadcast and IP functions in the same chassis for long periods.
Skyworth and Amlogic presented a 6 nm system-on-chip 4K Android TV Operator Tier device at IBC 2025 with edge AI and camera functions for gesture control and fitness applications. These functions fit an IP-only design more readily than a hybrid broadcast chassis. Hybrid devices remain relevant where terrestrial or satellite continuity is required, including rural North America, Southern Europe, and Brazil's TV 3.0 transition areas. Larger operators use cloud-managed IP devices that support over-the-air updates, while regional operators with limited cloud capacity retain hybrid equipment to maintain signal continuity. U.S. navigation rules support interoperable customer equipment and favor certified platforms over more closed legacy designs.
Complete Report Scope:
- By Product Type
- IP/OTT-Only Set-Top Boxes
- Hybrid Broadcast-OTT Set-Top Boxes
- By Operating System and Platform
- Android TV and Google TV
- RDK
- Proprietary Consumer Platforms
- Other Operating System and Platforms
- By Distribution Channel
- Retail
- Telecom, Broadband, and Pay-TV Operators
- Distributors and Systems Integrators
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounted for 43.58% of the global OTT set-top box market share in 2025, supported by higher selling prices, established streaming platforms, and a large cord-cutting population. Roku's 2025 annual report recorded USD 4.74 billion in revenue, USD 88.4 million in net income, and record free cash flow, showing that platform monetization rather than device margin drives leading regional platforms. Fox announced a proposed USD 22 billion acquisition of Roku in June 2026, subject to regulatory approval and expected to close in the first half of 2027. The proposal would combine Roku's connected television platform with Tubi and Fox content, increasing competition with Amazon Fire TV, Google TV, and Apple TV. Canada has a mature OTT base supported by broadband, while Mexico is shifting from direct-to-home satellite to IPTV and broadband services as fiber expands into secondary cities.
Asia-Pacific is projected to be the fastest-growing region, with a 9.06% CAGR through 2031. India's JioFiber expansion and Airtel Xstream bundles are moving households from legacy direct-to-home equipment toward IP-capable streaming devices, while the country's broadband subscriber base is projected to grow from 700 million in 2025 to more than 1.1 billion by 2030. China has the largest IPTV subscriber base and is projected to reach 500-550 million households by 2030, although MIIT certification and GB hardware standards steer demand toward domestic vendors and streaming services. Southeast Asia is a FAST growth area, and enforcement against MyIPTV4K in May 2026 indicates that certified devices can support anti-piracy efforts. These factors make Asia-Pacific an important expansion area for the OTT set-top box market.
Europe is modernizing through Android TV Operator Tier and RDK deployments, with Telenor's January 2026 T-We Boks III launch in Norway forming a basis for a Nordic service across Norway, Sweden, and Finland. South America is recording moderate volume growth as Brazil continues its digital transition, and ZTE and Claro launched the 4K Ultra HD IP STB Z4KW6 with Ultra HD video, voice control, Wi-Fi, and local streaming access in May 2026. Middle East and Africa remains smaller in value but is developing as Saudi Arabia expands fiber-to-the-home and operators deploy IPTV-ready equipment. The OTT set-top box market can gain in these regions where streaming subscriber growth requires a device that supports managed video delivery.
- Roku, Inc.
- Amazon.com, Inc.
- Apple Inc.
- Google LLC
- Samsung Electronics Co., Ltd.
- Vantiva SA
- SAGEMCOM Broadband SAS
- Skyworth Digital Technology Co., Ltd.
- Huawei Technologies Co., Ltd.
- ZTE Corporation
- Humax Co., Ltd.
- CommScope Holding Company, Inc.
- Kaonmedia Co., Ltd.
- Shenzhen SDMC Technology Co., Ltd.
- Xiaomi Corporation
- Comcast Corporation
- Netgem SA
- Vestel Elektronik Sanayi ve Ticaret A.S.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of The Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cord-Cutting and Migration to Flexible Streaming Aggregation
- 4.2.2 Fiber and 5G Fixed Wireless Expansion Enabling High-Quality OTT Delivery
- 4.2.3 Growth of FAST and Hybrid Live-TV Experiences
- 4.2.4 4K, HDR, Dolby Audio, and Premium Sports Streaming Upgrades
- 4.2.5 Operator Adoption of Android TV, RDK, and Cloud-Managed CPE
- 4.2.6 Smart-Home Hub Convergence Creating New Utility for the TV Screen
- 4.3 Market Restraints
- 4.3.1 Smart TVs Reducing the Need for Dedicated OTT Hardware
- 4.3.2 Long Device Replacement Cycles and Retail Price Erosion
- 4.3.3 Content Rights, DRM, and Certification Complexity Across Markets
- 4.3.4 Grey-Market IPTV Boxes and Cybersecurity-Driven Trust Deficits
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 IP/OTT-Only Set-Top Boxes
- 5.1.2 Hybrid Broadcast-OTT Set-Top Boxes
- 5.2 By Operating System and Platform
- 5.2.1 Android TV and Google TV
- 5.2.2 RDK
- 5.2.3 Proprietary Consumer Platforms
- 5.2.4 Other Operating System and Platforms
- 5.3 By Distribution Channel
- 5.3.1 Retail
- 5.3.2 Telecom, Broadband, and Pay-TV Operators
- 5.3.3 Distributors and Systems Integrators
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Vendor Positioning Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Roku, Inc.
- 6.4.2 Amazon.com, Inc.
- 6.4.3 Apple Inc.
- 6.4.4 Google LLC
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 Vantiva SA
- 6.4.7 SAGEMCOM Broadband SAS
- 6.4.8 Skyworth Digital Technology Co., Ltd.
- 6.4.9 Huawei Technologies Co., Ltd.
- 6.4.10 ZTE Corporation
- 6.4.11 Humax Co., Ltd.
- 6.4.12 CommScope Holding Company, Inc.
- 6.4.13 Kaonmedia Co., Ltd.
- 6.4.14 Shenzhen SDMC Technology Co., Ltd.
- 6.4.15 Xiaomi Corporation
- 6.4.16 Comcast Corporation
- 6.4.17 Netgem SA
- 6.4.18 Vestel Elektronik Sanayi ve Ticaret A.S.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 全球Over-The-Top服務市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 商業媒體服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)英國OTT:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)美國OTT:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031年)雲端OTT:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)中國OTT市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)印度OTT市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)德國OTT:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)OTT(Over The Top):市場佔有率分析、產業趨勢與統計數據、成長預測(2026-2031)北美OTT:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)