


 |
市場調查報告書
商品編碼
2116663
英國汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)United Kingdom Car Rentals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
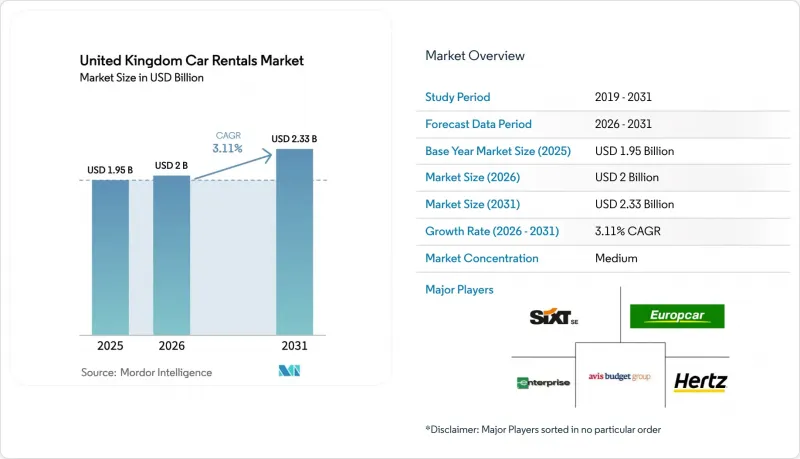
根據 Mordor Intelligence 預測,英國汽車租賃市場規模將從 2025 年的 19.5 億美元成長到 2026 年的 20 億美元,然後在 2031 年達到 23.3 億美元,2026 年至 2031 年的複合年成長率為 3.11%。
本報告按租賃期限(短期和長期)、預訂方式(線上和線下)、應用領域(休閒旅遊與商務)、車輛級別(經濟型、標準型、高階型和豪華型)、驅動方式(燃油車、混合動力車、純電動車)、最終用戶(個人用戶和其他用戶)、預訂管道(機場和其他管道)以及地區進行細分。市場預測以美元計價。
英國汽車租賃市場的趨勢與洞察
數位化優先的消費者體驗和行動預訂的激增
儘管網站流量有所下降,但旅行服務行動應用程式的下載量卻有所增加。這一趨勢促使汽車租賃業者優先投資開發原生應用程式,以維持品牌知名度。線上平台在英國汽車租賃市場佔據了相當大的佔有率,並且仍在穩步成長。然而,它們的影響力遠不止於促進交易。當日預訂的日益普及縮短了平均預訂前置作業時間,凸顯了即時車輛調度工具的重要性。位於機場外和城區的門市正受益於這一轉變,因為基於位置的搜尋現在更注重距離而非品牌忠誠度。獨立營運商正在利用到店客流,而全球連鎖企業則專注於類似於航空公司收益管理技術的演算法主導定價策略。這種策略轉變不僅推動了IT支出的成長,也透過提高車輛利用率提升了每輛車的收入。
政府獎勵支持電動車發展,並強制推行零排放車輛。
強制推行零排放車輛旨在未來幾年內顯著提升新車銷售中電池式電動車(電池式電動車)的佔比。儘管目前純電動車在租賃車隊總量中所佔比例較小,但它們在英國租賃汽車市場的成長速度最快。公共充電基礎設施已大幅擴展,快速充電樁的安裝也正在推進,以滿足日益成長的需求。然而,挑戰依然存在,許多業者指出,充電設施的可用性以及客戶對這項技術的不熟悉是阻礙純電動車廣泛普及的主要障礙。與汽車製造商(OEM)的合作正在幫助應對這些挑戰。例如,SIXT與Stellantis的合作確保了配備先進車載資訊系統的電池式電動車的穩定供應,並分擔了租賃車輛整個生命週期內的充電基礎設施相關成本。此外,政府將所有公務車輛逐步過渡到零排放車輛的政策也提供了一個穩定的政策環境,有助於降低私部門相關人員的不確定性。
由於新車供應緊張,車隊成本不斷上漲。
英國新車註冊量穩定成長,預計在不久的將來還會進一步成長。車隊和企業用車需求也顯著增加,導致市場供應緊張。半導體短缺情況有所緩解,但仍造成交貨延遲,迫使租車公司承擔額外成本以確保獲得配額。與量產經濟型轎車相比,高檔車型相對更容易獲得,這對專注於機場區域的營運商來說是一個優勢。然而,這種差異對依賴低利潤率和周轉率的獨立營運商構成了挑戰。隨著車輛老化,維護成本增加,客戶滿意度下降,限制了有效的價格調整。
細分市場分析
短期租賃佔了大部分收入,預計到2025年將達到73.30%,但隨著注重成本的旅客減少自由裁量權旅行,其成長速度正在放緩。長期租賃和訂閱式租賃的複合年成長率(CAGR)為12.67%,受到那些推遲購車並享受捆綁式保險和維護等優惠的駕駛員的青睞。英國汽車租賃市場的訂閱市場預計將從較低的基數快速成長,這主要得益於汽車製造商提供的融資方案降低了營運商的資本支出。訂閱車輛通常配備較新的車型和高級駕駛輔助系統(ADAS),這使其定價更高,並有助於提高企業的安全性和合規性指標。營運商透過適當分散資產來最大化車輛的殘值,將高里程的經濟型車輛輪換用於短期租賃管道,並將較新的車型保留給訂閱客戶。可預測的每月收入和較低的解約率率抵消了資本密集度的增加。
這種偏好的轉變反映了出行領域的結構性趨勢。都市區的年輕一代越來越傾向於按需使用而非擁有車輛,而企業則利用訂閱模式來滿足企劃為基礎需求,無需擴大自有車隊規模。因此,英國汽車租賃市場受惠於兩大需求促進因素,進而降低了業者的波動風險。營運商不斷最佳化定價演算法,以應對里程波動和可選服務,從而提升整個訂閱合約期間的利潤率。隨著汽車製造商擴大其直接面對消費者(D2C)的試點項目,汽車租賃公司憑藉其品牌知名度和覆蓋全國的服務網路,保持著競爭優勢。
預計到2025年,線上預訂將佔總收入的67.50%,年複合成長率達10.81%,並且隨著消費者優先考慮便利性和價格比較,線上通路的成長速度已超過線下通路。行動應用程式是數位成長的最大驅動力,其下載量年增6.3%。當日預訂的增加縮短了車輛規劃的前置作業時間,促使企業進一步投資於即時庫存管理。儘管線下方式在英國租車市場的佔有率持續下降,但它仍然佔據著重要地位,尤其是在機場和需要單獨結算的企業行程中。
聚合平台有助於提升中小企業的知名度,但同時也削弱了它們的定價權。同時,全球連鎖企業正引導忠實會員使用自家應用程式,以限制比價行為。機場外的門市受惠於較低的房地產成本,正利用這些節省下來的成本提供動態價格折扣,吸引對價格敏感的休閒旅客。預計到2030年,英國汽車租賃市場的線上通路規模將超過15億美元,這進一步提升了數位化能力的策略價值。儘管營運商正在推廣使用人工智慧聊天機器人的引導式預訂服務,但他們尚未實現讓客戶比較不同車型的視覺化介面。
預計到2025年,休閒產業將維持55.70%的收入佔有率,主要得益於國內旅遊和國際入境需求的支撐。然而,商務用車租賃業務成長更為迅猛,年複合成長率達9.63%,其成長動力主要來自對安全責任的履行以及鐵路網路中斷的影響。雇主認為,擁有一支專業管理的車隊對於追蹤里程、排放氣體和駕駛員行為至關重要。當行程超過100英里時,租車就更具成本效益,而100英里正是倫敦、曼徹斯特和伯明翰之間城際旅行的標準閾值。鐵路罷工加劇了這一趨勢,促使旅客轉向道路運輸。
休閒需求仍有明顯的季節性,在7月至8月的假期旺季達到高峰。Cornwall、斯諾登尼亞和高地地區吸引著許多傾向於短期租賃的國內遊客,這給營運商的車輛分配帶來了挑戰。英國汽車租賃市場受益於多元化的需求來源,從而降低了經濟波動風險。客戶細分使得精準行銷成為可能。數位宣傳活動為休閒遊客提供早鳥預訂折扣,而業務經理負責服務提前數月安排大量預訂的企業差旅部門。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 數位化優先的消費者體驗和行動預訂的激增
- 疫情後國內休閒旅遊激增
- 企業「安全責任」政策優先考慮租車而非公共運輸
- 政府獎勵支持電動車發展,並強制推行零排放車輛。
- 訂閱式「靈活租賃」模式的成長
- 由原始設備製造商 (OEM) 支援的專屬式租賃計劃旨在解決庫存過剩問題。
- 市場限制因素
- 由於新車供應緊張,車隊成本不斷上漲。
- 二手車價格波動導致殘值下降
- 全國公共充電網路的不平衡正在延緩電動車隊的部署。
- 加強跨境租賃業務的增值稅(VAT)合規性
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 租賃期
- 短期(30天或更短)
- 長期訂閱(超過 30 天)
- 按預訂類型
- 線上
- 離線
- 透過使用
- 休閒與旅遊
- 企業和公司
- 按車輛類別
- 低價
- 標準
- 頂級奢華
- 透過驅動系統
- 內燃機(ICE)
- 混合
- 電池式電動車(BEV)
- 最終用戶
- 個人
- 公司和組織
- 透過預訂管道
- 飛機場
- 機場外/市中心
- 鐵路和交通樞紐
- 按地區
- 英格蘭
- 蘇格蘭
- 威爾斯
- 北愛爾蘭
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Avis Budget Group
- Enterprise Holdings
- Europcar Mobility Group
- The Hertz Corporation
- SIXT SE
- Drivalia
- Green Motion
- Arnold Clark Car and Van Rental
- Easirent
- Practical Car and Van Rental
- U-Drive
- Virtuo
- Getaround(英國)
- Turo
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom car rental market size is expected to grow from USD 1.95 billion in 2025 to USD 2 billion in 2026 and is forecast to reach USD 2.33 billion by 2031 at a 3.11% CAGR over 2026-2031.
This report is Segmented by Rental Duration (Short-Term and Long-Term), Booking Type (Online and Offline), Application (Leisure/Tourism and Business/Corporate), Vehicle Class (Economy, Standard, and Premium / Luxury), Propulsion Type (ICE, Hybrid, and BEV), End-User (Individual and More), Booking Channel (Airport and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Car Rentals Market Trends and Insights
Digital-first Consumer Journey and Mobile Booking Boom
Mobile app downloads for travel services experienced growth, even as website traffic declined. This trend encouraged rental operators to prioritize investments in native apps to sustain their visibility. Online platforms hold a significant share of the UK's car rental market and continue to grow steadily. However, their influence extends beyond just facilitating transactions. Same-day reservations have become increasingly popular, reducing the average booking lead time and emphasizing the importance of real-time fleet allocation tools. Locations situated off-airport and in downtown areas benefit from this shift, as location-based searches now favor proximity over brand loyalty. Independent operators are capitalizing on walk-in demand, while global chains are focusing on algorithm-driven pricing strategies that resemble those used by airlines in yield management practices. This strategic shift is driving higher IT expenditures while simultaneously increasing revenue per available car through improved utilization.
EV-Friendly Government Incentives and Zero-Emission Fleet Mandates
The Zero Emission Vehicle mandate aims to significantly increase the adoption of battery-electric vehicles in new car sales over the coming years. Battery-electric vehicles, while currently a small portion of rental fleets, are experiencing the fastest growth within the United Kingdom's car rental market. Public charging infrastructure has seen substantial expansion, including the addition of rapid charging units to support the growing demand. However, challenges persist, as many operators identify charging availability and customer unfamiliarity with the technology as key obstacles to broader adoption. Collaborations with original equipment manufacturers are helping to address these issues. For example, a partnership between SIXT and Stellantis ensures a consistent supply of battery-electric models equipped with advanced telematics, while also sharing the costs associated with charging infrastructure throughout the rental lifecycle. Additionally, the government's commitment to transitioning all departmental fleets to zero-emission vehicles demonstrates a stable policy environment, which helps reduce uncertainties for private-sector stakeholders.
Tight New-car Supply Inflating Fleet Costs
New-car registrations in the United Kingdom have shown steady growth, with expectations of further increases in the near future . Fleet and business volumes have experienced a notable increase, contributing to a tighter market supply. Although semiconductor shortages have improved, they continue to cause delays in delivery times, prompting rental companies to incur additional costs for securing allocations. Premium vehicle models are more readily available compared to high-volume economy cars, which benefits operators focused on airport locations. However, independent operators, who depend on low-margin turnover, face challenges due to this disparity. As vehicle fleets age, maintenance expenses increase, and customer satisfaction declines, which limits the ability to adjust pricing effectively.
Other drivers and restraints analyzed in the detailed report include:
- Post-Pandemic Domestic Leisure Travel Surge
- Growth of Subscription-Based Flex-Rent Models
- Used-Car Price Volatility Depressing Residual Values
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Short-term hires dominated revenue, accounting for 73.30% in 2025, yet face slowing growth as cost-conscious travelers reduce discretionary trips. Long-term and subscription rentals, growing at a 12.67% CAGR, appeal to drivers who are delaying ownership while enjoying bundled insurance and maintenance. The United Kingdom car rental market size for subscriptions is projected to rise sharply from a modest base, driven by OEM financing that reduces operator capital expenditures. Subscription fleets feature newer cars with advanced driver-assistance systems that justify premium fees and enhance safety and compliance metrics for corporates. Operators split their asset pools accordingly, cycling high-mileage economy units through short-term channels and reserving late-model inventory for subscription customers to maximize residual values. Heightened capital intensity is offset by predictable monthly revenue and lower churn rates.
The preference shift reflects trends in structural mobility. Younger urban residents increasingly value on-demand access over ownership, and corporates use subscriptions to cover project-based assignments without expanding company fleets. The United Kingdom car rental market, therefore, benefits from dual demand drivers that mitigate volatility for operators. Providers continue to refine pricing algorithms to account for mileage variability and optional services, improving margin visibility across the subscription term. As OEMs expand direct-to-consumer pilots, rental companies leverage brand recognition and nationwide service footprints to maintain a competitive edge.
Online reservations accounted for 67.50% of 2025 revenue and are advancing at a 10.81% CAGR, outpacing offline channels as consumers prioritize convenience and price comparison. Mobile apps capture the largest share of digital growth, driven by a 6.3% year-over-year increase in downloads. Same-day bookings compress fleet-planning windows, prompting deeper investment in real-time inventory management. The United Kingdom car rental market share captured by offline methods continues to decline, yet remains significant, particularly at airports and for corporate itineraries that require bespoke billing arrangements.
Aggregators help smaller firms gain exposure but erode pricing control, whereas global chains funnel loyalty members into proprietary apps to limit comparison shopping. Off-airport sites, backed by lower real estate costs, channel savings into dynamic price discounts that attract cost-sensitive leisure travelers. The United Kingdom car rental market size allocated to online channels is projected to exceed USD 1.50 billion by 2030, magnifying the strategic value of digital capabilities. Operators experiment with AI chatbots for guided reservations, though uptake lags visual interfaces where customers compare vehicle classes.
Leisure retained 55.70% revenue share in 2025, fueled by domestic tourism and international inbound traffic. However, business rentals are growing faster at a 9.63% CAGR, driven by duty-of-care compliance and rail network disruption. Employers view professionally managed fleets as essential for tracking mileage, emissions, and driver behavior. Rentals become cost-effective beyond 100 miles, a standard threshold for inter-city trips between London, Manchester, and Birmingham. Rail strikes reinforce this preference, reallocating travelers to road-based modes.
Leisure demand remains seasonally influential, peaking during July-August holiday periods. Cornwall, Snowdonia, and the Highlands attract staycationers who prefer multi-day hires, creating vehicle allocation challenges for operators. The United Kingdom car rental market benefits from diversified demand streams that mitigate cyclical risk. Customer segmentation enables tailored marketing: digital campaigns target leisure users with early-booking discounts, while account managers service corporate travel departments that schedule block reservations months in advance.
Complete Report Scope:
- By Rental Duration
- Short-Term (Less than 30 days)
- Long-Term/Subscription (More than 30 days)
- By Booking Type
- Online
- Offline
- By Application
- Leisure / Tourism
- Business / Corporate
- By Vehicle Class
- Economy
- Standard
- Premium / Luxury
- By Propulsion Type
- Internal-Combustion Engine (ICE)
- Hybrid
- Battery Electric Vehicle (BEV)
- By End-User
- Individual
- Corporate and Institutional
- By Booking Channel
- Airport
- Off-Airport / Downtown
- Rail and Mobility Hubs
- By Geography
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- Avis Budget Group
- Enterprise Holdings
- Europcar Mobility Group
- The Hertz Corporation
- SIXT SE
- Drivalia
- Green Motion
- Arnold Clark Car and Van Rental
- Easirent
- Practical Car and Van Rental
- U-Drive
- Virtuo
- Getaround (UK)
- Turo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Digital-First Consumer Journey and Mobile Booking Boom
- 4.2.2 Post-Pandemic Domestic Leisure Travel Surge
- 4.2.3 Corporate Duty-Of-Care Policies Favoring Rentals Over Public Transport
- 4.2.4 EV-Friendly Government Incentives and Zero-Emission Fleet Mandates
- 4.2.5 Growth Of Subscription-Based "Flex-Rent" Models
- 4.2.6 OEM-Backed Captive Rental Programs Targeting Over-Supply Inventory
- 4.3 Market Restraints
- 4.3.1 Tight New-Car Supply Inflating Fleet Costs
- 4.3.2 Used-Car Price Volatility Depressing Residual Values
- 4.3.3 Patchy National Public-Charge Network Slowing EV Fleet Roll-Out
- 4.3.4 Stricter VAT Compliance on Cross-Border Rentals
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD Million)
- 5.1 By Rental Duration
- 5.1.1 Short-Term (Less than 30 days)
- 5.1.2 Long-Term/Subscription (More than 30 days)
- 5.2 By Booking Type
- 5.2.1 Online
- 5.2.2 Offline
- 5.3 By Application
- 5.3.1 Leisure / Tourism
- 5.3.2 Business / Corporate
- 5.4 By Vehicle Class
- 5.4.1 Economy
- 5.4.2 Standard
- 5.4.3 Premium / Luxury
- 5.5 By Propulsion Type
- 5.5.1 Internal-Combustion Engine (ICE)
- 5.5.2 Hybrid
- 5.5.3 Battery Electric Vehicle (BEV)
- 5.6 By End-User
- 5.6.1 Individual
- 5.6.2 Corporate and Institutional
- 5.7 By Booking Channel
- 5.7.1 Airport
- 5.7.2 Off-Airport / Downtown
- 5.7.3 Rail and Mobility Hubs
- 5.8 By Geography
- 5.8.1 England
- 5.8.2 Scotland
- 5.8.3 Wales
- 5.8.4 Northern Ireland
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Avis Budget Group
- 6.4.2 Enterprise Holdings
- 6.4.3 Europcar Mobility Group
- 6.4.4 The Hertz Corporation
- 6.4.5 SIXT SE
- 6.4.6 Drivalia
- 6.4.7 Green Motion
- 6.4.8 Arnold Clark Car and Van Rental
- 6.4.9 Easirent
- 6.4.10 Practical Car and Van Rental
- 6.4.11 U-Drive
- 6.4.12 Virtuo
- 6.4.13 Getaround (UK)
- 6.4.14 Turo
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 印度汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)印尼汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)新加坡汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)法國汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)泰國汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度電動自行車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)東協汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)