


 |
市場調查報告書
商品編碼
2116662
法國汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)France Car Rental - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,法國租車市場規模將從 2025 年的 67.8 億美元成長到 2026 年的 71.6 億美元,然後在 2031 年達到 93.8 億美元,2026 年至 2031 年的複合年成長率為 5.55%。
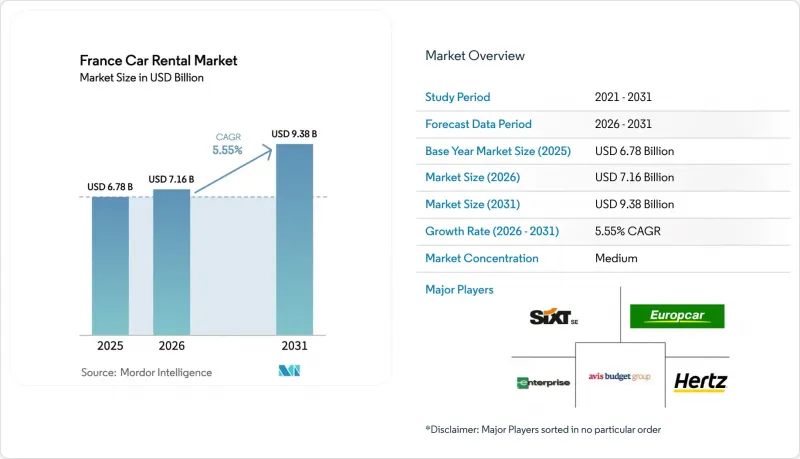
本報告按租賃期限(短期和長期)、預訂管道(線上和線下)、應用領域(休閒、旅遊及其他)、車輛類型(經濟型及其他)、驅動方式(內燃機及其他)、取車地點(機場及其他)和客戶類型(個人和企業車隊)進行細分。市場預測以貨幣價值(美元)和數量(輛)兩種形式呈現。
法國汽車租賃市場的趨勢與洞察
入境和國內旅遊增加
2024年,法國接待了1億國際遊客,旅遊收入達710億歐元,創下旅遊業復甦的新紀錄。 「法國目的地」計畫已投資19億歐元用於提升飯店服務水平,而橄欖球世界盃和2024-2025年奧運週期等賽事也進一步提升了法國的國際知名度。由於遊客擴大選擇租車前往酒莊、文化遺產地和滑雪勝地等地,公共運輸網路不發達的鄉村地區尤其受益。世界旅遊及旅遊理事會(WTTC)預測,到2034年,旅遊業對法國GDP的貢獻將增加至3,105億歐元,這顯示旅遊業的需求具有永續性。區域城市休閒租賃需求的穩定成長以及長期預訂量的成長也支撐了旅遊業的蓬勃發展。
按需應用程式預訂平台的激增
Free2move 的全新出行應用整合了汽車租賃、汽車共享和訂閱式車輛服務,在全球範圍內提供超過 50 萬輛汽車的選擇。 Getaround 獲得了 2000 萬美元的資金籌措,其全球應用全面升級,凸顯了行動優先設計的競爭優勢。整合的支付功能、一鍵式保險和即時車輛追蹤功能降低了獲客成本,提高了車輛運轉率。隨著 P2P 平台不斷提升車輛庫存透明度和社交評價,那些在使用者介面現代化方面落後的傳統機構將面臨客戶流失流失的風險。
叫車和共享汽車服務的出現加劇了競爭。
在人口密集的城市中心,叫車和共享汽車正在蠶食傳統租車的市場佔有率。 Turo 收購了 P2P 租車先驅 OuiCar,新增了數千輛私家車,每日租金低至 20 歐元,拓寬了價格和車型選擇範圍。 Getaround 專注於歐洲市場的重組,加上 Heetch 的夜間租車許可,進一步提升了千禧世代用戶對便利性的需求。這種競爭環境擠壓了機場租車櫃檯的利潤空間,迫使現有業者提供會員積分、代客泊車或捆綁式高級會員計劃,以支撐更高的日租金。
細分市場分析
2025年,短期租賃在法國汽車租賃市場仍佔73.78%的佔有率,反映出遊客需求佔高。然而,長期租賃和經營性租賃預計將以9.05%的複合年成長率成長,到2031年,法國合約汽車租賃市場規模將達到22.8億美元。這一成長主要得益於企業將車輛管理外包以及採用訂閱模式,從而規避了折舊免稅額風險。
長期合約對那些需要根據ESG目標管理排放並要求可預測月費的公司來說極具吸引力。 Mobilize Financial Services不斷擴大的業務組合清晰地反映了這一轉變,而休閒旅客仍然傾向於選擇按日租車,以便於短途出行。因此,法國汽車租賃市場在穩定的遊客流量和利潤豐厚的企業合約之間保持平衡。
預計到 2025 年,線上入口網站將佔法國汽車租賃市場佔有率的 64.10%,到 2031 年,這將進一步推動法國汽車租賃市場規模成長 16.2 億美元。在行動支付、生物識別和即時損壞記錄等技術的推動下,該通路預計將以 9.76% 的複合年成長率成長,從而減少櫃檯等待時間。
機場和火車站的線下櫃檯仍然吸引著不熟悉本地應用程式的顧客和旅客。然而,大多數成熟企業現在都在推行全通路策略,透過確保線上和線下零售通路的促銷代碼、積分和可選獎勵保持一致,來維護品牌形象。
預計到2025年,休閒旅遊將佔法國租車市場收入的58.10%,主要得益於遊客數量的強勁成長。同時,商務旅行的成長速度更快,年複合成長率達8.55%,預計到2031年將佔法國租車市場佔有率的近三分之一。
企業差旅政策正逐漸從按里程報銷差旅費用轉向按需租車補貼和共用訂閱車輛。整合式費用管理軟體和集中式計費系統正在縮短管理週期,並促進財務部門擺脫「灰色車隊」模式。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 入境和國內旅遊增加
- 按需應用程式預訂平台的激增
- 企業對靈活出行解決方案的需求
- 政府對租賃電動車的激勵措施
- 與鐵路和航空運營商合作的綜合多式聯運方案
- 以環境、社會和治理 (ESG) 為導向的企業車輛電氣化目標
- 市場限制因素
- 叫車和共享汽車服務的出現加劇了競爭。
- 高昂的營運成本和車輛折舊免稅額費用
- Z世代越來越傾向於過著不依賴汽車的城市生活。
- 關於內燃機車輛租賃的低排放氣體區(ZFE)法規
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 租賃期
- 短期(30天或更短)
- 長期經營租賃(超過30天)
- 透過預訂管道
- 線上
- 離線
- 透過使用
- 休閒與旅遊
- 企業和公司
- 按車輛類別
- 預算經濟
- 頂級奢華
- 透過驅動系統
- 內燃機
- 混合
- 電池式電動車
- 按取貨地點
- 飛機場
- 機場外(火車站、市中心、飯店等)
- 依客戶類型
- 個人
- 企業車隊
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Avis Budget Group Inc.
- Enterprise Holdings Inc.
- Europcar Mobility Group
- The Hertz Corporation
- Sixt SE
- Ada SA
- 租車(法國)
- Ubeeqo
- Keddy(Europcar)
- Getaround France
- Virtuo
- Drivy
- Free2Move Rent
- Renault Mobilize Share
- Leasys Rent
- Green Motion
- Goldcar
- National Car Rental
- Alamo
- Buchbinder
第7章 市場機會與未來展望
According to Mordor Intelligence, the France car rental market size is expected to grow from USD 6.78 billion in 2025 to USD 7.16 billion in 2026 and is forecast to reach USD 9.38 billion by 2031 at 5.55% CAGR over 2026-2031.
This report is Segmented by Rental Duration (Short Term, and Long Term), Booking Channel (Online, and Offline), Application (Leisure/Tourism, and More), and Vehicle Class (Budget/Economy, and More), Propulsion Type (Internal-Combustion Engine, and More), Pickup Location (Airport, and More), Client Type (Individual, and Corporate Fleet). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
France Car Rental Market Trends and Insights
Growth in inbound & domestic tourism flows
Tourism returned to record performance as France hosted 100 million overseas visitors in 2024, generating EUR 71 billion in receipts in the same year. The Destination France plan channels EUR 1.9 billion into hospitality upgrades, while events such as the Rugby World Cup and the 2024-25 Olympic cycle elevate global exposure. Rural regions that lack dense public transit particularly benefit as travelers secure cars for winery, heritage, and ski itineraries. The World Travel & Tourism Council projects sector GDP contribution to rise to EUR 310.5 billion by 2034, a signal of durable demand.This tourism momentum underpins consistent leisure rental volumes and lengthier bookings in secondary cities.
Surge in on-demand, app-based booking platforms
Free2move's new mobility app aggregates rental, car-sharing, and subscription vehicles, accessing more than 500,000 units worldwide. Getaround's global app overhaul, backed by USD 20 million financing, underscores the competitive edge of mobile-first design. Integrated payment, one-click insurance, and real-time vehicle tracking lower acquisition costs and improve fleet utilization. Traditional agencies lagging on user-interface upgrades risk customer churn as peer-to-peer platforms expand inventory transparency and social reviews.
Intensifying competition from ride-hailing & car-sharing
Ride-hailing apps and car-sharing fleets erode traditional rental share in dense urban cores. Turo's acquisition of peer-to-peer pioneer OuiCar added thousands of privately owned cars available from EUR 20 per day, widening price points and vehicle variety. Getaround's Europe-focused overhaul, combined with Heetch's licensed nighttime services, raises convenience expectations among millennial users. This competitive mix compresses margins at airport counters and forces incumbents to bundle loyalty perks, valet delivery, or premium subscription tiers that justify higher daily rates.
Other drivers and restraints analyzed in the detailed report include:
- Corporate demand for flexible mobility solutions
- Government incentives for electric-vehicle rentals
- High operating & fleet depreciation costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Short-term hire retained 73.78% share of the France car rental market in 2025, a reflection of tourist-heavy demand patterns. Nonetheless, long-term and operating leases are projected to expand at 9.05% CAGR and will lift the France car rental market size for contracted rentals to USD 2.28 billion by 2031. Adoption is driven by corporate fleet outsourcing and subscription programs that sidestep depreciation risk.
Long-term contracts appeal to businesses that track emissions under ESG targets and require predictable monthly charges. Mobilize Financial Services' portfolio growth demonstrates the shift, while leisure travelers continue to favor day-based rentals for quick getaways. The France car rental market therefore balances steady tourist volume with higher-margin corporate agreements.
Online portals delivered 64.10% of the France car rental market share in 2025 and will add another USD 1.62 billion to the France car rental market size by 2031. The channel's 9.76% CAGR is sustained by mobile payments, biometrics, and instant damage recording that cut counter wait times.
Offline counters at airports and train stations still attract walk-in customers and travelers unfamiliar with local apps. Yet most incumbents now pursue omnichannel strategies, ensuring that the same promotion codes, loyalty points, and optional coverages align across digital and physical points of sale, preserving brand consistency.
Leisure travel contributed 58.10% of France car rental market revenue in 2025, anchored by resilient tourism flows. Corporate travel, however, grows faster at an 8.55% CAGR and will nudge its share to nearly one-third of the France car rental market size by 2031.
Company travel policies increasingly substitute mileage reimbursement with on-demand rental allowances or pooled subscription vehicles. Integrated expense software and centralized billing shorten administration cycles and incentivize finance departments to switch from gray-fleet arrangements.
Complete Report Scope:
- By Rental Duration
- Short-Term (Less than or equal to 30 days)
- Long-Term / Operating Lease (More than 30 days)
- By Booking Channel
- Online
- Offline
- By Application
- Leisure / Tourism
- Business / Corporate
- By Vehicle Class
- Budget / Economy
- Premium / Luxury
- By Propulsion Type
- Internal-Combustion Engine
- Hybrid
- Battery-Electric
- By Pickup Location
- Airport
- Off-Airport (Rail-Station, Downtown, Hotel, etc.)
- By Client Type
- Individual
- Corporate Fleet
List of Companies Covered in this Report:
- Avis Budget Group Inc.
- Enterprise Holdings Inc.
- Europcar Mobility Group
- The Hertz Corporation
- Sixt SE
- Ada SA
- Rent A Car (France)
- Ubeeqo
- Keddy by Europcar
- Getaround France
- Virtuo
- Drivy
- Free2Move Rent
- Renault Mobilize Share
- Leasys Rent
- Green Motion
- Goldcar
- National Car Rental
- Alamo
- Buchbinder
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in inbound & domestic tourism flows
- 4.2.2 Surge in on-demand, app-based booking platforms
- 4.2.3 Corporate demand for flexible mobility solutions
- 4.2.4 Government incentives for electric-vehicle (EV) rentals
- 4.2.5 Multi-modal packages with rail & air operators
- 4.2.6 ESG-driven fleet electrification targets of corporates
- 4.3 Market Restraints
- 4.3.1 Intensifying competition from ride-hailing & car-sharing
- 4.3.2 High operating & fleet depreciation costs
- 4.3.3 Shifts toward car-free urban lifestyles among Gen-Z
- 4.3.4 Low-emission-zone (ZFE) restrictions on ICE rentals
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Rental Duration
- 5.1.1 Short-Term (Less than or equal to 30 days)
- 5.1.2 Long-Term / Operating Lease (More than 30 days)
- 5.2 By Booking Channel
- 5.2.1 Online
- 5.2.2 Offline
- 5.3 By Application
- 5.3.1 Leisure / Tourism
- 5.3.2 Business / Corporate
- 5.4 By Vehicle Class
- 5.4.1 Budget / Economy
- 5.4.2 Premium / Luxury
- 5.5 By Propulsion Type
- 5.5.1 Internal-Combustion Engine
- 5.5.2 Hybrid
- 5.5.3 Battery-Electric
- 5.6 By Pickup Location
- 5.6.1 Airport
- 5.6.2 Off-Airport (Rail-Station, Downtown, Hotel, etc.)
- 5.7 By Client Type
- 5.7.1 Individual
- 5.7.2 Corporate Fleet
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.4.1 Avis Budget Group Inc.
- 6.4.2 Enterprise Holdings Inc.
- 6.4.3 Europcar Mobility Group
- 6.4.4 The Hertz Corporation
- 6.4.5 Sixt SE
- 6.4.6 Ada SA
- 6.4.7 Rent A Car (France)
- 6.4.8 Ubeeqo
- 6.4.9 Keddy by Europcar
- 6.4.10 Getaround France
- 6.4.11 Virtuo
- 6.4.12 Drivy
- 6.4.13 Free2Move Rent
- 6.4.14 Renault Mobilize Share
- 6.4.15 Leasys Rent
- 6.4.16 Green Motion
- 6.4.17 Goldcar
- 6.4.18 National Car Rental
- 6.4.19 Alamo
- 6.4.20 Buchbinder
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 印度汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)印尼汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)新加坡汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)泰國汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)英國汽車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度電動自行車租賃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)東協汽車租賃市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)