


 |
市場調查報告書
商品編碼
2063778
馬來西亞折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Malaysia Folding Carton - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
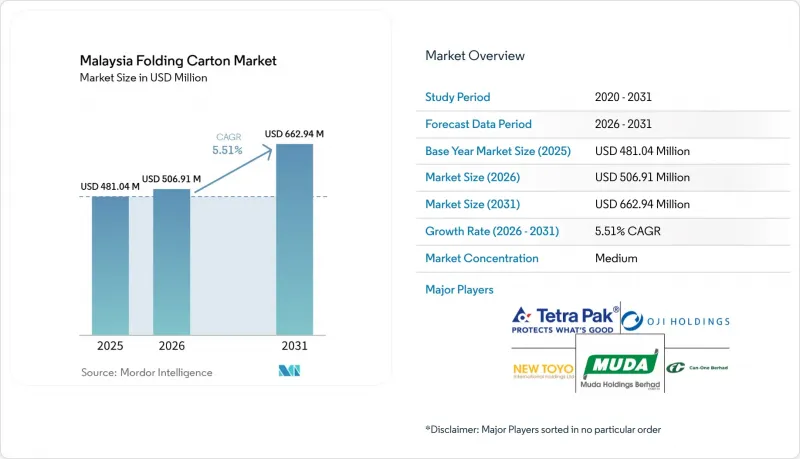
根據 Mordor Intelligence 預測,馬來西亞折疊式紙盒市場規模將從 2025 年的 4.8104 億美元和 2026 年的 5.0691 億美元成長到 2031 年的 6.6294 億美元,2026 年至 2031 年的複合年成長率為 5.51%。
本報告按材料類型(固態漂白硫酸漿、折疊式紙板、塗佈未漂白牛皮紙等)、印刷技術(膠印、柔版印刷、數位印刷、凹版印刷等)和終端用戶行業(食品飲料、醫療保健和製藥、個人護理和化妝品、電氣和電子設備等)進行細分。市場預測以美元計價。
馬來西亞折疊式紙盒市場的市場趨勢與洞察
高階包裝商品的日益普及
隨著高階化妝品、糖果甜點和保健品的需求不斷成長,品牌所有者越來越傾向於選擇能夠進行壓紋、金屬油墨和觸感清漆處理的瓦楞紙板,這重新定義了基材規格。雀巢馬來西亞的奇巧即飲飲料和攜帶式美極方便麵碗便是轉向耐油塗層的典型例子,即使在高速灌裝線上也能保持品牌形象。在調查受訪者中佔60-70%的都市區消費者,即使在價格敏感的環境下,也越來越青睞那些揭露可回收性資訊的品牌。因此,儘管成本面臨挑戰,但比折疊紙板貴15-20%的SBS(固態漂白硫酸紙漿紙板)仍在高階商品市場保持市場佔有率。馬來西亞內貿部2026年廣告法規強制要求清楚標註可回收性,將加速淘汰未經認證的加工商。高階定位和監管支援的結合,擴大了能夠在認證基材上印刷高清圖形的加工商可獲得的價值池,從而推動了馬來西亞折疊式紙盒市場的上升趨勢。
政府推廣永續包裝標準
馬來西亞的《2025-2035年循環經濟藍圖》將於2030年將生產者延伸責任制(EPR)從自願性轉變為強制性,要求加工商追蹤原料採購、能源消耗和回收績效。違規者每次將被處以5萬馬幣(約12,337美元)的罰款。 Lazada和Shopee進一步加大了監管力度,自2026年7月起對不合規包裝加收3%的附加費,立即提高了未認證供應商的准入門檻。 Box-Pak Malaysia積極應對這項監管變化,已在三個國家獲得其產銷監管鏈(CoC)體系的認證,使其在競標跨國日常消費品(FMCG)公司時擁有競爭優勢。 2025年《指定廢棄物條例》對油墨污泥的重新分類,進一步促進了對閉合迴路水處理的投資。這些措施加在一起,導致交易量集中在資金雄厚的大型公司手中,永續性正在成為馬來西亞瓦楞紙板市場一項既定的、不可協商的要求。
再生紙進口價格波動劇烈
2025年,混合等級紙張的交易價格在每噸180美元至260美元之間波動,價格差異高達44%,這將使按季度簽訂合約的加工商的利潤率下降3至5個百分點。由於國內造紙企業囤積纖維,美國對東南亞的紙張出貨量從2023年的180萬噸下降到2025年的120萬噸。 2025年第一季,OCC現貨價格飆升28%後回落,這使得以60天結算週期交易的加工商的庫存估值變得更加複雜。儘管京興新工廠的投產緩解了原生紙漿短缺的問題,但大部分白襯紙板仍依賴進口再生紙。在馬來西亞國內原料供應更加充足之前,價格波動將繼續抑制馬來西亞折疊式紙盒市場的價格上漲。
細分市場分析
預計到2025年,折疊式紙板在馬來西亞折疊紙盒市場將保持41.71%的佔有率,這主要得益於其剛性和在品牌食品、藥品和化妝品領域的高印刷適性。同時,由100%再生纖維製成的白瓦楞紙板預計將以6.41%的複合年成長率成長,因為注重成本的家居用品品牌和電商企業看重其20-25%的價格優勢。一旦Nextgreen IOI的棕櫚纖維漿配方符合ISO 22002-4:2025過渡標準,馬來西亞白瓦楞紙板市場預計將迅速擴張。對於高階化妝品而言,儘管由於依賴從斯堪地那維亞和北美進口而導致進口成本上升,但固態硫酸鹽漿仍然是首選的基材,並保持其高階地位。同時,未漂白塗佈牛皮紙因其天然棕色符合永續發展訊息,且能減輕高達10%的運輸重量,在常溫食品領域逐漸佔據市場佔有率。混合微瓦楞層壓板雖然仍屬於小眾市場,但在電子行業,其市場佔有率正在不斷成長,因為在電子行業,抗摔性比價格更為重要。
加工商正在將原生紙漿和再生紙漿混合使用,以平衡成本,同時滿足品牌對氣味、遷移物質和亮度的要求。 Lazada 2026 年的 FSC 認證規則將鞏固對再生材料的需求,同時淘汰未經產銷監管鏈 (CoC) 審核的造紙廠,並將需求集中於通過 ISO 14001 認證的公司。在預測期內,國內紙漿供應量的增加將縮小折疊紙板和白襯紙板之間的成本差距,削弱後者的價格優勢,而再生材料基材將鞏固其作為馬來西亞折疊式紙盒市場結構性成長引擎的地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 高階包裝商品的日益普及
- 政府致力於推行永續包裝標準
- 快速商業化導致雜貨宅配激增
- 國內造紙企業擴大產能
- 人工智慧驅動的品質檢測系統
- 消費品生產近岸外包
- 市場限制因素
- 再生紙進口價格波動劇烈
- 熟練印刷操作員短缺
- 飲料軟包裝袋日益普及
- 巴生港物流瓶頸
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 材料類型
- 固態漂白硫酸漿
- 折疊紙板
- 未漂白工藝外套
- 白線塑合板
- 其他材料類型
- 透過印刷技術
- 平版印刷
- 柔版印刷
- 數位印刷
- 凹版印刷
- 其他印刷技術
- 按最終用戶行業分類
- 食品/飲料
- 醫療保健/製藥
- 個人護理化妝品
- 電氣和電子設備
- 家用物品和工業產品
- 菸草
- 電子商務與零售包裝
- 其他終端用戶產業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Muda Holdings Berhad
- Oji Holdings Corporation
- Can-One Berhad
- Tetra Pak Malaysia Sdn Bhd
- New Toyo International Holdings Ltd
- Orient Press Sdn Bhd
- KYM Holdings Berhad
- Ornapaper Industry(M)Sdn Bhd
- Rengo Co., Ltd.
- Tat Seng Packaging Group Ltd
- Kian Joo Can Factory Berhad
- Box-Pak(Malaysia)Bhd
- Lamipak(Malaysia)Sdn Bhd
- Paper-Based Packaging Sdn Bhd
- Mondi plc
- SCG Packaging Public Company Limited
- Hexachase Packaging Sdn Bhd
- Printpack Asia Sdn Bhd
第7章 市場機會與未來展望
According to Mordor Intelligence, the malaysia folding carton market size is projected to expand from USD 481.04 million in 2025 and USD 506.91 million in 2026 to USD 662.94 million by 2031, registering a CAGR of 5.51% between 2026 to 2031.
This report is Segmented by Material Type (Solid Bleached Sulfate, Folding Boxboard, Coated Unbleached Kraft, and More), Printing Technology (Lithographic, Flexographic, Digital, Gravure, and More), End-User Industry (Food and Beverage, Healthcare/Pharmaceuticals, Personal Care and Cosmetics, Electrical and Electronics, and More). The Market Forecasts are Provided in Terms of Value (USD).
Malaysia Folding Carton Market Trends and Insights
Growing Adoption of Premium Packaged Goods
Demand for premium cosmetics, confectionery, and healthcare SKUs is reshaping substrate specifications as brand owners insist on cartons that accept embossing, metallic inks, and tactile varnishes. Nestle Malaysia's ready-to-drink KitKat beverages and portable Maggi bowls exemplify the shift toward grease-resistant coatings that preserve brand imagery under high-speed filling lines. Urban consumers, 60-70% of survey respondents, now favor brands that publish recyclability information, even when price sensitivity remains high. Solid bleached sulfate board, priced at a 15-20% premium to folding boxboard, is therefore holding share in luxury goods despite cost headwinds. The Ministry of Domestic Trade's 2026 advertising code compels clear labeling of recyclability, accelerating the exit of non-certified converters. Collectively, prestige positioning and regulatory nudges are expanding the value pool available to converters capable of delivering high-definition graphics on certified substrates, reinforcing upward momentum in the Malaysian folding carton market.
Government Push for Sustainable Packaging Standards
Malaysia's Circular Economy Blueprint 2025-2035 transitions from voluntary to mandatory extended producer responsibility by 2030, requiring converters to track sourcing, energy intensity, and recycling outcomes, or face MYR 50,000 (USD 12,337) in fines per violation. Lazada and Shopee magnified the pressure by levying a 3% surcharge on non-compliant packaging starting July 2026, instantly raising the entry bar for uncertified suppliers. Box-Pak Malaysia pre-empted the rule change by certifying chain-of-custody systems across three countries, giving the group pole position for multinational FMCG tenders. Ink sludge re-classification under the 2025 scheduled-waste rules is further motivating investments in closed-loop water treatment. In combination, these measures channel volume toward large, well-capitalized firms and cement sustainability as a non-negotiable qualifier within the Malaysian folding carton market.
Volatile Recovered Paper Import Prices
Mixed-paper grades traded between USD 180 and USD 260 per tonne in 2025, a 44% spread that erased 3-5 percentage-point margins for converters locked into quarterly contracts. U.S. shipments to Southeast Asia fell from 1.8 million tonnes in 2023 to 1.2 million tonnes in 2025 as domestic mills hoarded fiber. Spot OCC prices spiked 28% in Q1 2025 before retreating, complicating inventory valuation for converters on 60-day terms. While Jingxing's new mill eases virgin-fiber tightness, most white-lined chipboard still relies on imported recovered paper. Until additional domestic furnish arrives, price turbulence will continue to cap upside in the Malaysia folding carton market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Quick-Commerce Grocery Delivery
- Capacity Expansion by Domestic Paper Mills
- Shortage of Skilled Press Operators
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Folding boxboard retained 41.71% of Malaysia's folding carton market share in 2025 on the back of its stiffness and print fidelity for branded food, pharma, and cosmetic lines. Yet white-lined chipboard, built from 100% recycled fiber, is on track for a 6.41% CAGR as cost-conscious household-goods brands and e-commerce shippers embrace its 20-25% unit-price advantage. The Malaysian folding carton market for white-lined chipboard is poised to expand sharply once Nextgreen IOI's palm-fiber pulp is blended into grades that comply with ISO 22002-4:2025 migration norms. Solid bleached sulfate remains the substrate of choice for prestige cosmetics, sustaining premium positioning even though import dependency from Scandinavia and North America inflates landed cost. Coated unbleached kraft is capturing ambient grocery items where its natural brown look aligns with sustainability messaging and trims freight weight by up to 10%. Hybrid micro-flute laminates, although niche, are carving a share in electronics where drop resistance trumps price.
Converters are mixing virgin and recycled furnish to hit brand-mandated barriers on odor, migration, and brightness while juggling cost. Lazada's 2026 FSC-certification rule cements recycled-content demand but simultaneously weeds out mills lacking chain-of-custody audits, concentrating volume with ISO 14001 holders. Over the forecast window, domestic pulp additions should narrow the cost gap between folding boxboard and white-lined chipboard, softening the latter's price edge yet cementing recycled substrates as the structural growth engine of the Malaysian folding carton market.
List of Companies Covered in this Report:
- Muda Holdings Berhad
- Oji Holdings Corporation
- Can-One Berhad
- Tetra Pak Malaysia Sdn Bhd
- New Toyo International Holdings Ltd
- Orient Press Sdn Bhd
- KYM Holdings Berhad
- Ornapaper Industry (M) Sdn Bhd
- Rengo Co., Ltd.
- Tat Seng Packaging Group Ltd
- Kian Joo Can Factory Berhad
- Box-Pak (Malaysia) Bhd
- Lamipak (Malaysia) Sdn Bhd
- Paper-Based Packaging Sdn Bhd
- Mondi plc
- SCG Packaging Public Company Limited
- Hexachase Packaging Sdn Bhd
- Printpack Asia Sdn Bhd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Premium Packaged Goods
- 4.2.2 Government Push for Sustainable Packaging Standards
- 4.2.3 Surge in Quick-Commerce Grocery Delivery
- 4.2.4 Capacity Expansion by Domestic Paper Mills
- 4.2.5 AI-Enabled Quality Inspection Systems
- 4.2.6 Near-Shoring of Regional Consumer-Goods Production
- 4.3 Market Restraints
- 4.3.1 Volatile Recovered Paper Import Prices
- 4.3.2 Shortage of Skilled Press Operators
- 4.3.3 Rising Popularity of Flexible Pouches for Beverage
- 4.3.4 Logistic Bottlenecks at Port Klang
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Solid Bleached Sulfate
- 5.1.2 Folding Boxboard
- 5.1.3 Coated Unbleached Kraft
- 5.1.4 White Line Chipboard
- 5.1.5 Other Material Types
- 5.2 By Printing Technology
- 5.2.1 Lithographic Printing
- 5.2.2 Flexographic Printing
- 5.2.3 Digital Printing
- 5.2.4 Gravure Printing
- 5.2.5 Other Printing Technologies
- 5.3 By End-User Industry
- 5.3.1 Food and Beverage
- 5.3.2 Healthcare/Pharmaceuticals
- 5.3.3 Personal Care and Cosmetics
- 5.3.4 Electrical and Electronics
- 5.3.5 Household and Industrial Goods
- 5.3.6 Tobacco
- 5.3.7 E-Commerce and Retail-Ready Packaging
- 5.3.8 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Muda Holdings Berhad
- 6.4.2 Oji Holdings Corporation
- 6.4.3 Can-One Berhad
- 6.4.4 Tetra Pak Malaysia Sdn Bhd
- 6.4.5 New Toyo International Holdings Ltd
- 6.4.6 Orient Press Sdn Bhd
- 6.4.7 KYM Holdings Berhad
- 6.4.8 Ornapaper Industry (M) Sdn Bhd
- 6.4.9 Rengo Co., Ltd.
- 6.4.10 Tat Seng Packaging Group Ltd
- 6.4.11 Kian Joo Can Factory Berhad
- 6.4.12 Box-Pak (Malaysia) Bhd
- 6.4.13 Lamipak (Malaysia) Sdn Bhd
- 6.4.14 Paper-Based Packaging Sdn Bhd
- 6.4.15 Mondi plc
- 6.4.16 SCG Packaging Public Company Limited
- 6.4.17 Hexachase Packaging Sdn Bhd
- 6.4.18 Printpack Asia Sdn Bhd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 金屬化折疊式紙盒市場規模、佔有率和成長分析:按材料、金屬化類型、應用、最終用戶、印刷技術和地區分類 - 行業預測,2026-2033年
 西班牙折疊式紙盒市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)中國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)中東和非洲折疊式紙盒市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)越南折疊式紙盒市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)日本折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)法國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)義大利折疊式紙盒:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)英國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)