


 |
市場調查報告書
商品編碼
2063777
越南折疊式紙盒市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Vietnam Folding Carton - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,越南折疊式紙盒市場在 2025 年的價值為 6.2531 億美元,預計到 2031 年將達到 9.1645 億美元,而 2026 年為 6.6483 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 6.3%。
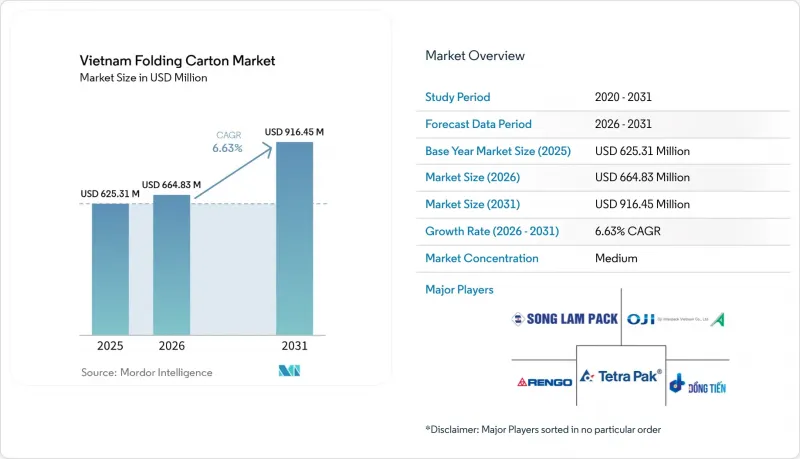
本報告按材料類型(固態漂白硫酸紙漿、折疊式紙板、塗佈未漂白牛皮紙、白線塑合板等)、印刷技術(膠印、柔版印刷、數位印刷等)和終端用戶行業(食品飲料、電子商務和零售包裝、煙草等)進行細分。市場預測以美元計價。
越南折疊式紙盒市場趨勢與洞察
來自電子商務領域的需求不斷成長
2023年,越南線上零售通路的包裝材料消耗量達33.2萬噸,其中折疊式紙盒約佔40%。該通路目前佔零售商品銷售額的12%,短短三年內成長了4個百分點。經銷商越來越傾向於選擇「即買即用」的包裝形式,這種形式可以減少高達20%的訂單履行工作量。這一趨勢也為能夠將防篡改技術與醒目圖案相結合的包裝加履約帶來了源源不斷的訂單。跨境電商平台如Lazada和Shopee已將FSC認證納入賣家入駐要求,這意味著所有透過平台網路運輸的瓦楞紙箱都必須立即接受標準規範的審查。因此,越南折疊式瓦楞紙箱市場正受惠於雙重優勢:銷售量絕對值的成長以及向高等級材料(利潤率更高)的轉變。
政府推動永續包裝的舉措
第110/2026號法令規定,生產商必須承擔廢舊產品收集和回收的成本,並設定了2028年紙張回收率達到30%的目標。同時,第05/2025號法令對都市區餐飲服務業的一次性塑膠製品進行了規範。這些法規共同促使快餐店、電子產品組裝和家居用品製造商轉向使用再生纖維的瓦楞紙板解決方案。違規者將被處以5,000萬越南盾(約2,100美元)至1億越南盾(約4,200美元)的罰款,因此,品牌所有者被鼓勵指定使用可折疊紙板或含有50%以上再生材料的未漂白塗佈牛皮紙。那些早期投資於脫墨和再生紙收集生產線,或與生產者責任組織合作的加工商,如今在越南折疊式紙盒市場的授權許可方面擁有明顯的優勢。
原生紙漿價格波動
2026年1月,歐洲漂白桉樹牛皮紙的價格為每噸1220至1250美元,北美漂白針葉樹牛皮紙的價格為每噸1600美元。在價格轉嫁條款設有上限的合約下,這使得加工商的利潤率最多下降了300個基點。由於70%的原生紙漿依賴進口,外匯波動和地緣政治因素會使裝貨價格每噸增加80至120美元。只有18%的加工商使用遠期合約,而且大多數加工商都容易受到季度價格調整的影響,這可能導致價格飆升10%至15%。這種壓力對於固體漂白硫酸鹽(SBS)紙漿來說最為嚴重,因為其白度穩定性限制了替代品的使用,並且正在拖累越南整個折疊紙盒市場的盈利能力。
細分市場分析
到2025年,漂白硫酸鹽紙將佔據越南折疊式紙盒市場33.42%的佔有率,鞏固其在化妝品、藥品和高階糖果甜點等高階應用領域的地位。品牌商選擇這種紙是因為其白度超過88 GE,且表面可印刷,適用於光刻工藝,從而增強了其在價格敏感但又對圖案要求較高的品類中的地位。由於快餐店和電履約中心採用250-300克/平方米的紙盒以降低運費,預計折疊紙盒的複合紙張重量將達到8.75%,成為所有基材中成長最快的。隨著第110/2026號法令鼓勵使用再生材料,塗佈未漂白牛皮紙在電子產品和家居用品包裝材料中的地位日益鞏固。同時,白面塑合板正被供應給注重成本的乾貨包裝商。
利樂公司計劃將其年產量擴大至300億個包裝,凸顯了阻隔塗層固態漂白硫酸紙漿在其無菌乳製品和果汁生產線中的核心地位。即使在紙漿價格飆升的情況下,這仍然是一個有利可圖的細分市場。隨著再生纖維含量基準值的提高,加工商正在將原生紙漿和再生紙漿混合,以在不超出成本目標的前提下保持抗張強度。線上紙張重量掃描儀、近紅外線水分控制設備和高濃度精磨機幫助大型造紙廠實現更嚴格的紙張重量公差。這對於將付款條件與統計流程控制指標掛鉤的跨國公司至關重要。缺乏資金進行此類投資的小型加工商則面臨被擠出利潤微薄的通用紙盒市場的風險。因此,越南折疊式紙盒市場的規模經濟往往集中在那些既擁有多種原料選擇,又具備資本密集品管系統的企業。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務領域的需求增加
- 政府推廣永續包裝
- 食品和飲料出口成長
- 可支配所得增加和都市化
- 高色域數位小批量印刷在中小企業中的興起。
- 國內精釀啤酒品牌對優質紙盒的需求
- 市場限制因素
- 原生光纖價格波動
- 來自軟包裝的競爭加劇
- 主要港口設施的物流瓶頸
- 缺乏先進的紙張回收能力
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 材料類型
- 固態漂白硫酸漿
- 折疊式紙板
- 未漂白工藝外套
- 白線塑合板
- 其他材料類型
- 透過印刷技術
- 平版印刷
- 柔版印刷
- 數位印刷
- 凹版印刷
- 其他印刷技術
- 按最終用戶行業分類
- 食品/飲料
- 醫療保健/製藥
- 個人護理化妝品
- 電氣和電子設備
- 家用物品和工業產品
- 菸草
- 電子商務與零售包裝
- 其他終端用戶產業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Dong Tien Packaging and Paper Co. Ltd.
- Oji Packaging(Vietnam)Co. Ltd.
- Rengo Co. Ltd.
- Marubeni-South East Asia Packaging Corp.
- Tetra Pak Vietnam JSC
- Song Lam Packaging JSC
- Siam Kraft Industry Co. Ltd.
- Lee & Man Paper Manufacturing Ltd.
- Thuan An Paper and Packaging JSC
- AnBinh Printing Carton Packaging Co. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the vietnam folding carton market size was valued at USD 625.31 million in 2025 and is estimated to grow from USD 664.83 million in 2026 to reach USD 916.45 million by 2031, at a CAGR of 6.63% during 2026-2031.
This report is Segmented by Material Type (Solid Bleached Sulfate, Folding Boxboard, Coated Unbleached Kraft, White Line Chipboard, and More), Printing Technology (Lithographic Printing, Flexographic Printing, Digital Printing, and More), and End-User Industry (Food and Beverage, E-Commerce and Retail-Ready Packaging, Tobacco, and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Folding Carton Market Trends and Insights
Rising Demand from the E-Commerce Sector
Vietnam's online retail channel consumed 332,000 tons of packaging materials in 2023, of which folding cartons supplied roughly 40% by volume. The channel now accounts for 12% of retail goods sales, having climbed 4% points in just 3 years. Merchants increasingly prefer shelf-ready formats that cut fulfillment labor by up to 20%, a dynamic that is funneling steady orders toward converters able to combine tamper-evident engineering with striking graphics. Cross-border platforms such as Lazada and Shopee embed FSC certification into seller eligibility, instantly redefining baseline specifications for every carton shipped through their networks. The Vietnam folding carton market, therefore, benefits twice: in higher absolute volumes and in the migration to premium substrates that command superior margins.
Government Push for Sustainable Packaging
Decree 110/2026 obliges producers to finance post-consumer collection and recycling, setting a 30% paper recovery target by 2028, while Decree 05/2025 restricts single-use plastics in urban food service. Together, the regulations are channeling quick-service restaurants, electronics assemblers, and household-goods makers toward recycled-fiber carton solutions. Penalties for non-compliance range from VND 50 million (USD 2,100) to VND 100 million (USD 4,200), spurring brand owners to specify Folding Boxboard and Coated Unbleached Kraft with at least 50% recycled content. Converters that invested early in de-inking and waste-paper aggregation lines, or that formed alliances with Producer Responsibility Organizations, now enjoy a distinct licensing edge in the Vietnamese folding carton market.
Volatility in Virgin Fiber Prices
January 2026 quotations moved European Bleached Eucalyptus Kraft to USD 1,220-1,250 per ton and Northern Bleached Softwood Kraft to USD 1,600, trimming converter margins by as much as 300 basis points under contracts that cap pass-through clauses. With 70% of virgin pulp imported, exchange-rate swings and geopolitical freight surcharges add USD 80-120 to every ton landed. Only 18% of converters use forward contracts, leaving most exposed to quarterly resets that can jump 10-15%. The squeeze is most acute for Solid Bleached Sulfate grades, where brightness consistency bars substitution, weighing on earnings across the Vietnam folding carton market.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Food and Beverage Exports
- Rising Disposable Income and Urbanization
- Intensifying Competition from Flexible Packaging
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solid Bleached Sulfate captured 33.42% of the Vietnam folding carton market share in 2025, firmly anchoring premium applications in cosmetics, pharmaceuticals, and high-end confectionery. Brand owners select the grade for brightness levels above 88 GE and print surfaces that enable photographic lithography, reinforcing its grip on price-sensitive but graphics-intensive categories. Folding Boxboard is expected to post an 8.75% CAGR, the fastest rate among substrates, as quick-service restaurants and e-commerce fulfillment centers adopt weights in the 250-300 gsm range to curb freight surcharges. Coated Unbleached Kraft is strengthening its foothold in electronics and household-goods shippers because Decree 110/2026 rewards recycled-content compliance, while White Line Chipboard supplies cost-conscious dry-food fillers.
Tetra Pak's expansion to 30 billion packs annually highlights the centrality of barrier-coated Solid Bleached Sulfate to aseptic dairy and juice lines, a niche that shields profits even amid pulp inflation. As recycled-content thresholds climb, converters are blending virgin and secondary fiber to safeguard tensile integrity without breaching cost targets. Inline basis-weight scanners, near-infrared moisture controls, and high-consistency refiners help large mills deliver tighter grammage tolerances, a precondition for multinationals that link payout terms to statistical process control metrics. Smaller converters unable to finance such upgrades risk relegation to low-margin commodity cartons. The Vietnam folding carton market size advantage therefore gravitates toward operators that couple substrate versatility with capital-intensive quality systems.
List of Companies Covered in this Report:
- Dong Tien Packaging and Paper Co. Ltd.
- Oji Packaging (Vietnam) Co. Ltd.
- Rengo Co. Ltd.
- Marubeni-South East Asia Packaging Corp.
- Tetra Pak Vietnam JSC
- Song Lam Packaging JSC
- Siam Kraft Industry Co. Ltd.
- Lee & Man Paper Manufacturing Ltd.
- Thuan An Paper and Packaging JSC
- AnBinh Printing Carton Packaging Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand From the E-Commerce Sector
- 4.2.2 Government Push for Sustainable Packaging
- 4.2.3 Growth in Food and Beverage Exports
- 4.2.4 Rising Disposable Income and Urbanization
- 4.2.5 Rise of High-Color Digital Short Runs for SMEs
- 4.2.6 Premium Carton Demand From Domestic Craft Beer Brands
- 4.3 Market Restraints
- 4.3.1 Volatility in Virgin Fiber Prices
- 4.3.2 Intensifying Competition From Flexible Packaging
- 4.3.3 Logistics Bottlenecks at Key Port Facilities
- 4.3.4 Limited Advanced Paper Recycling Capacity
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Solid Bleached Sulfate
- 5.1.2 Folding Boxboard
- 5.1.3 Coated Unbleached Kraft
- 5.1.4 White Line Chipboard
- 5.1.5 Other Material Types
- 5.2 By Printing Technology
- 5.2.1 Lithographic Printing
- 5.2.2 Flexographic Printing
- 5.2.3 Digital Printing
- 5.2.4 Gravure Printing
- 5.2.5 Other Printing Technologies
- 5.3 By End-User Industry
- 5.3.1 Food and Beverage
- 5.3.2 Healthcare/Pharmaceuticals
- 5.3.3 Personal Care and Cosmetics
- 5.3.4 Electrical and Electronics
- 5.3.5 Household and Industrial Goods
- 5.3.6 Tobacco
- 5.3.7 E-commerce and Retail-ready Packaging
- 5.3.8 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dong Tien Packaging and Paper Co. Ltd.
- 6.4.2 Oji Packaging (Vietnam) Co. Ltd.
- 6.4.3 Rengo Co. Ltd.
- 6.4.4 Marubeni-South East Asia Packaging Corp.
- 6.4.5 Tetra Pak Vietnam JSC
- 6.4.6 Song Lam Packaging JSC
- 6.4.7 Siam Kraft Industry Co. Ltd.
- 6.4.8 Lee & Man Paper Manufacturing Ltd.
- 6.4.9 Thuan An Paper and Packaging JSC
- 6.4.10 AnBinh Printing Carton Packaging Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 金屬化折疊式紙盒市場規模、佔有率和成長分析:按材料、金屬化類型、應用、最終用戶、印刷技術和地區分類 - 行業預測,2026-2033年
 西班牙折疊式紙盒市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)中國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)中東和非洲折疊式紙盒市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)馬來西亞折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)德國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)日本折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)法國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)義大利折疊式紙盒:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)英國折疊式紙盒市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)