


 |
市場調查報告書
商品編碼
2154289
泰國礦業機械:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Thailand Mining Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
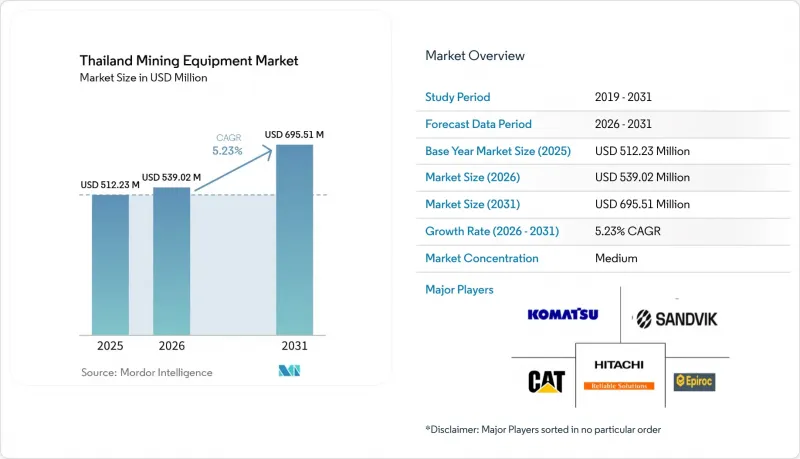
根據 Mordor Intelligence 預測,泰國礦業機械市場預計將從 2025 年的 5.1223 億美元成長到 2026 年的 5.3902 億美元,到 2031 年達到 6.9551 億美元,在預測期(2026-2031 年成長率為 5.23%。
泰國礦業機械市場趨勢與分析
擴大石灰石和採石業務,以滿足國內建築需求。
陸橋走廊和高速鐵路網等大型企劃推動了骨材需求的成長,促使暹羅水泥公司和南方集團在其設備中新增了36噸級挖土機、輪式裝載機和顎式破碎機。 ISO 14001標準的實施(該標準現已強制要求公部門競標進行環境管理系統認證)也加速了設備的升級換代。烏塔堡機場維修計畫於2026年4月發布的動工通知,確保了未來幾年穩定的材料供應。
泰國東北部卡利計畫投資激增。
在東協鉀肥、亞太鉀肥和泰國鉀肥礦區,由於年產量目標大幅提高,已下達大量連續採礦機、頂板錨桿機和輸送系統訂單,總金額預計達數億美元。上年度,政府批准向烏隆他尼府提供財政援助,併計劃於2024年下半年在猜也奔府簽訂大規模基礎設施分包契約,這些都為該項目的進展提供了進一步的支持。然而,由於仍在與當地居民進行磋商,關鍵路徑進度預計將繼續延長。
禁止開發金礦將抑制相關設備的需求。
繼2026年3月法院裁定查特利礦區業者對環境損害負有責任後,氰化物浸出製程的監管力度加大,對新的硬岩金礦床的探勘也受到限制。鑽機和破碎機供應商正在將資產重新分配給石灰石和鉀肥客戶,同時等待許可證指南的進一步明確。
細分市場分析
2025年,露天採礦機械佔泰國採礦機械總銷售額的43.48%,證實了泰國採礦機械市場以採石場為中心。隨著模組化破碎技術在中型採石場的普及,預計到2031年,裝載機的銷售額將以5.27%的複合年成長率成長。儘管在鉀礦隧道建設加速之前,地下採礦的需求有限,但連續採礦機和錨桿安裝機的訂單已與2027-2028年的交付計畫掛鉤。選礦生產線可同時處理花崗岩骨材和氯化鉀,原始設備製造商(OEM)提供符合ISO 14001粉塵排放標準的承包破碎和分選設備。
在泰國的礦業設備市場,儘管該國大多數鑽孔仍較淺,但能夠處理2000至4000公尺探勘深度的鑽孔機仍然很受歡迎。目前,OEM裝載機產品線包括功率為120至480千瓦的電池驅動型號,這些型號受到能夠連接電網的石灰石礦工的青睞。由於缺乏超大型露天礦,100噸以上的大型剛性卡車並不常見,但銷售團隊會備有演示樣機,以應對鉀礦產量擴大後可能需要的更大負載容量。
泰國擁有眾多小規模採石場,這些採石場僱用了大量熟練的操作人員,因此即使到了2025年,人工操作車輛仍將佔據主導地位,市場佔有率高達67.71%。由於偏遠地區安全法規日益嚴格以及人事費用不斷上漲,預計全自動車輛的普及率將以5.29%的複合年成長率成長。遠端遙控裝載機填補了這一空白,降低了在資訊通訊技術基礎設施不完善的狹窄礦坑中的風險。目前,泰國礦山機械市場至少有三個鉀肥礦坑試點項目,操作人員在地面控制室遠端操控裝載機。 DPIM(泰國礦山機械製造商協會)的持續標準化工作將增強人們對遠端操作協議的信心,並為自動駕駛轉型提供更廣泛的資金籌措。
半自動駕駛系統,可將石灰石採石場的生產效率提高 8% 至 12%。資金籌措模式包括按小時計費的訂閱計劃,降低了家庭式採石場的進入門檻。上市水泥製造商的 ESG(環境、社會和治理)報告也推動了自動駕駛系統的應用,因為這些系統能夠降低事故率,並成為投資者關注的重要風險指標。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大石灰石和採石業務,以滿足國內建築需求。
- 泰國東北部鉀肥計畫投資激增。
- 電子產品和電動車供應鏈對金屬礦石的需求增加。
- 引入半自動化運輸系統,以提高安全性並降低成本。
- 政府對電池驅動採礦機械的激勵措施
- 東協貿易一體化:降低資本財進口關稅
- 市場限制因素
- 禁止開採黃金抑制了對相關設備的需求。
- 動力煤價格波動劇烈,為該項目蒙上了一層陰影。
- 高昂的電網電價正在減緩偏遠煤礦的電氣化進程。
- 當地社區反對新的稀土元素探勘區
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 依設備類型
- 露天鑽井設備
- 地下採礦設備
- 礦物加工設備
- 鑽頭和破碎機
- 破碎、研磨、分類
- 裝載機
- 礦用卡車
- 按自動化級別
- 手動裝置
- 半自動自主設備
- 全自動設備
- 依動力傳動系統類型
- 內燃機車
- 電池式電動車
- 混合動力汽車
- 依輸出類型
- 低於500馬力
- 500~1,000 HP
- 1000馬力或以上
- 透過使用
- 金屬礦開採
- 礦產開採
- 採煤
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery
- Sandvik AB
- Epiroc AB
- Volvo Construction Equipment
- Liebherr-International AG
- Sany Heavy Equipment
- Doosan Infracore
- XCMG Group
- Terex Corporation
- Kobelco Construction Machinery
- DOVE Equipment & Machinery(Thailand)
- Thai Kobelco Construction Machinery
- Sumitomo Construction Machinery Co. Ltd.
- Wirtgen Group
- Astec Industries, Inc.
- Atlas Copco(Power Technique)
- Sany Heavy Industry Co., Ltd
- FLSmidth A/S
第7章 市場機會與未來展望
According to Mordor Intelligence, the Thailand mining equipment market is expected to grow from USD 512.23 million in 2025 to USD 539.02 million in 2026 and reach USD 695.51 million by 2031, at a CAGR of 5.23% during the forecast period (2026-2031).
Thailand Mining Equipment Market Trends and Insights
Expansion of Limestone and Quarry Operations for Domestic Construction
Megaprojects such as the land bridge corridor and high-speed rail network elevate aggregate demand, prompting Siam City Cement and Southern Group to add 36-tonne excavators, wheel loaders, and jaw crushers. Compliance with ISO 14001 accelerates fleet renewal because public-sector bids now require certified environmental management . Notice to Proceed for the U-Tapao Airport upgrade on April 2026 guarantees multi-year material off-take.
Surging Investment in Potash Projects in Northeast Thailand
With a significant annual output target, ASEAN Potash, Asia Pacific Potash, and Thai Kali concessions are placing substantial orders for continuous miners, roof bolters, and conveyor systems, with a total value estimated to be in the hundreds of millions of dollars. The pipeline is further validated by government-approved funding for Udon Thani in a previous year and a major subcontract for Chaiyaphum infrastructure scheduled for late 2024, even as community consultations continue to extend critical-path schedules.
Ban on Gold Mining Limiting Equipment Demand
A March 2026 court ruling that held Chatree operators liable for environmental damage heightened scrutiny on cyanide leach processes, curbing new hard-rock gold exploration. Drilling-rig and crusher suppliers are redeploying assets to limestone and potash clients while awaiting clearer permitting guidance.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Metal Ores from Electronics and EV Supply Chains
- Adoption of Semi-Autonomous Haulage for Safety & Cost Reduction
- Volatile Thermal-Coal Royalties Dampening Projects
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Surface machinery captured 43.48% of 2025 revenue, confirming the Thailand mining equipment market as quarry centric. Loaders are on pace for a 5.27% CAGR through 2031 as modular crushing spreads across mid-size pits. Underground demand remains limited until potash shafts reach full construction phases, yet purchase orders for continuous miners and roof bolters are tied to 2027-2028 delivery windows. Mineral-processing lines support both granite aggregate and potassium chloride beneficiation, with OEMs offering turnkey crusher-screen packages that comply with ISO 14001 dust-emission limits.
The Thailand mining equipment market continues to favor drill rigs rated for 2,000-4,000 m exploration depths, even though most domestic holes remain shallow. Loader OEM portfolios now include 120-480 kW battery-electric variants that appeal to limestone operators with grid access. Large rigid trucks above 100 tonnes are scarce, reflecting an absence of ultra-class open pits, yet sales teams keep demonstrator units on standby should potash ramp-ups warrant higher payload capacity.
Manual fleets still predominate with 67.71% share in 2025 because Thailand hosts numerous small quarries employing skilled operators. Fully autonomous adoption is forecast at a 5.29% CAGR as safety regulations tighten and labor costs climb in remote regions. Tele-remote loaders bridge the gap by lowering exposure in confined headings without full ICT infrastructure. The Thailand mining equipment market now counts at least three pilot potash headings where operators run loaders from surface control rooms. Ongoing standard-setting by DPIM will cement confidence in remote protocols and unlock broader financing for autonomy retrofits.
Semi-autonomous kits provide collision avoidance and operator-assist features that raise productivity 8-12% in limestone quarries. Financing models include per-hour subscription packages that lower entry barriers for family-owned pits. ESG reporting by publicly traded cement producers is also nudging adoption because autonomous systems cut incident rates, a material risk metric for investors.
Complete Report Scope:
- By Equipment Type
- Surface Mining Equipment
- Underground Mining Equipment
- Mineral Processing Equipment
- Drills & Breakers
- Crushing, Pulverizing & Screening
- Loaders
- Mining Trucks
- By Automation Level
- Manual Equipment
- Semi-Autonomous Equipment
- Fully Autonomous Equipment
- By Powertrain Type
- Internal-Combustion Engine Vehicles
- Battery-Electric Vehicles
- Hybrid Vehicles
- By Power Output
- Less than 500 HP
- 500 - 1,000 HP
- Above 1,000 HP
- By Application
- Metal Mining
- Mineral Mining
- Coal Mining
List of Companies Covered in this Report:
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery
- Sandvik AB
- Epiroc AB
- Volvo Construction Equipment
- Liebherr-International AG
- Sany Heavy Equipment
- Doosan Infracore
- XCMG Group
- Terex Corporation
- Kobelco Construction Machinery
- DOVE Equipment & Machinery (Thailand)
- Thai Kobelco Construction Machinery
- Sumitomo Construction Machinery Co. Ltd.
- Wirtgen Group
- Astec Industries, Inc.
- Atlas Copco (Power Technique)
- Sany Heavy Industry Co., Ltd
- FLSmidth A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion Of Limestone and Quarry Operations for Domestic Construction
- 4.2.2 Surging Investment in Potash Projects in Northeast Thailand
- 4.2.3 Rising Demand for Metal Ores From Electronics and EV Supply Chains
- 4.2.4 Adoption Of Semi-Autonomous Haulage for Safety & Cost Reduction
- 4.2.5 Government Incentives for Battery-Electric Mining Equipment
- 4.2.6 ASEAN Trade Integration: Reducing Import Duties On Capital Equipment
- 4.3 Market Restraints
- 4.3.1 Ban On Gold Mining Limiting Equipment Demand.
- 4.3.2 Volatile Thermal-Coal Royalties Dampening Projects
- 4.3.3 High Grid-Power Tariffs Slowing Electrification in Remote Pits.
- 4.3.4 Community Opposition to New Rare-Earth Exploration Blocks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Surface Mining Equipment
- 5.1.2 Underground Mining Equipment
- 5.1.3 Mineral Processing Equipment
- 5.1.4 Drills & Breakers
- 5.1.5 Crushing, Pulverizing & Screening
- 5.1.6 Loaders
- 5.1.7 Mining Trucks
- 5.2 By Automation Level
- 5.2.1 Manual Equipment
- 5.2.2 Semi-Autonomous Equipment
- 5.2.3 Fully Autonomous Equipment
- 5.3 By Powertrain Type
- 5.3.1 Internal-Combustion Engine Vehicles
- 5.3.2 Battery-Electric Vehicles
- 5.3.3 Hybrid Vehicles
- 5.4 By Power Output
- 5.4.1 Less than 500 HP
- 5.4.2 500 - 1,000 HP
- 5.4.3 Above 1,000 HP
- 5.5 By Application
- 5.5.1 Metal Mining
- 5.5.2 Mineral Mining
- 5.5.3 Coal Mining
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Hitachi Construction Machinery
- 6.4.4 Sandvik AB
- 6.4.5 Epiroc AB
- 6.4.6 Volvo Construction Equipment
- 6.4.7 Liebherr-International AG
- 6.4.8 Sany Heavy Equipment
- 6.4.9 Doosan Infracore
- 6.4.10 XCMG Group
- 6.4.11 Terex Corporation
- 6.4.12 Kobelco Construction Machinery
- 6.4.13 DOVE Equipment & Machinery (Thailand)
- 6.4.14 Thai Kobelco Construction Machinery
- 6.4.15 Sumitomo Construction Machinery Co. Ltd.
- 6.4.16 Wirtgen Group
- 6.4.17 Astec Industries, Inc.
- 6.4.18 Atlas Copco (Power Technique)
- 6.4.19 Sany Heavy Industry Co., Ltd
- 6.4.20 FLSmidth A/S
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 全球深海採礦設備市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 礦業水力旋流器市場:全球市場預測,2026-2032年
 美國礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)中國礦山機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)印度礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)非洲礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)馬來西亞礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)日本礦業機械:市場佔有率分析、產業趨勢及統計、成長預測(2026-2031)法國礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)