


 |
市場調查報告書
商品編碼
2125685
中東資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032 年)Middle East Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2032) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年中東資料中心建設市場價值為 52.4 億美元,預計到 2032 年將達到 238.6 億美元,而 2026 年為 65.1 億美元,預測期(2026-2032 年)的複合年成長率為 24.18%。
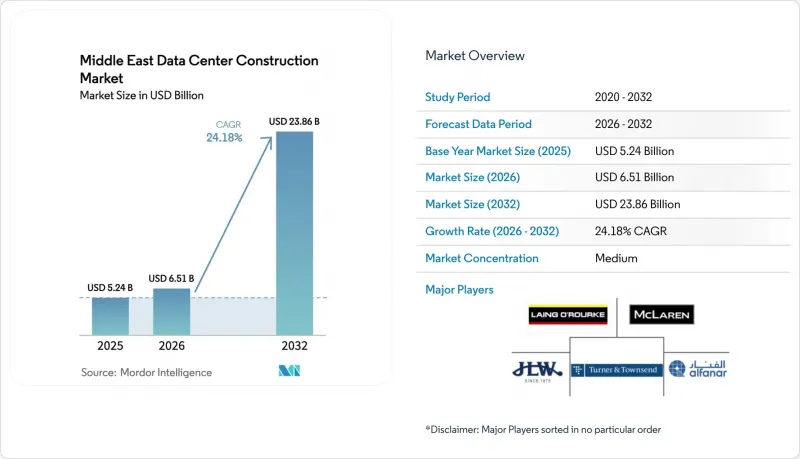
本報告按基礎設施(電力基礎設施、機械基礎設施、 IT基礎設施等)、等級(一級、二級、三級、四級)、資料中心類型(託管、超大規模/現場建設等)、終端用戶產業(銀行、金融服務和保險、IT及電信、政府及國防等)和地區進行細分。市場預測以美元計價。
中東資料中心建置市場趨勢與洞察
超大規模雲端和人工智慧的發展正在加速區域基礎設施轉型。
OpenAI 與 G42 在 5 GW「星際之門阿拉伯聯合大公國」園區的合作,已將每個機架的功率密度提升至 80 kW,液冷已成為標準設計。微軟的零水冷卻技術更增加了沙漠環境下的機械複雜性。這些部署正在推動對電氣子系統的需求,並將中東資料中心建置市場打造成為下一代高密度設計的試驗場。
政府的數位經濟和願景規劃正在推動國內主導的基礎設施發展。
沙烏地阿拉伯的「全球人工智慧中心法」草案包含「資料大使館」條款,這些大使館將在沙烏地阿拉伯境內優先建造。阿拉伯聯合大公國和阿曼也採取了類似舉措,將在地採購比例標準納入採購法規。由此產生的可預測需求趨勢將支撐長期資本投資,並鞏固中東資料中心建設市場作為數位政府戰略核心平台的地位。
電網瓶頸和柴油設備投資成本高昂限制了快速發展。
沙烏地阿拉伯成長走廊的電網升級未能跟上需求,導致該地區電力供應啟動時間延遲長達18個月。此外,鋼鐵和運輸成本的上漲使得柴油備用系統的成本比2024年上漲了35%至40%。這些因素正在減緩中東資料中心建置市場短期專案的啟動速度。
細分市場分析
受GPU叢集擴張的推動,電氣設備的銷售額正在成長,電氣子系統的複合年成長率高達27.84%。每個機架支援40-80千瓦功率的開關設備、配電單元(PDU)和不間斷電源(UPS)正在重新設計機房佈局並增加結構荷載。預計2032年,中東資料中心建置市場電氣系統市場規模將達67.2億美元。液冷泵的整合使設施電力消耗量增加了15-25%,模糊了機械設備和電氣設備之間的界線。因此,服務供應商正透過將設計、整合和可再生能源諮詢納入承包提案,進一步深化其在中東資料中心建立市場的專業知識。
在沙漠地區,強勁的冷卻需求至關重要,因此機械系統仍然是支出中佔比最大的部分。後門式熱交換器和直接送風迴路的快速普及將確保到2025年機械系統仍維持37.55%的市場佔有率。目前,工程設計增加了閒置頻段高度以容納歧管管道和更重的冷卻器,這推高了土木工程成本。因此,電氣和機械系統的協調配合決定了專案的關鍵路徑,並塑造了其在中東資料中心建立市場整體競爭地位。
三級資料中心(Tier III)兼顧99.982%的運轉率和成本控制,預計到2025年將佔據53.65%的市場佔有率。然而,隨著銀行和公共部門客戶採用雙活架構,四級資料中心(Tier IV)的採用率預計到2032年將以21.72%的複合年成長率成長。四級資料中心先進的氣密性和雙匯流排電纜佈線將使資本支出(CAPEX)增加25-30%,同時也使其能夠實現更高的定價。隨著監管和金融科技工作負載的成長,預計到2032年,四級資料中心在中東資料中心建設市場的佔有率將達到17.45%。
對於邊緣部署,通常優先選擇二級機房以加快部署速度。模組化供應商在工廠完成組件認證,執行時間將現場工作量減少一半,並實現 12 週內運作。 Uptime Institute 認證仍然是採購要求,迫使小規模的建築商與全球認證機構合作。然而,認證積壓凸顯了區域技能短缺問題,減緩了中東資料中心建置市場中一些三級機房升級的進程。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 超大規模雲端運算和人工智慧基礎設施的擴張正在加速。
- 政府關於數位經濟和願景的計劃
- 5G邊緣延遲要求正在加速本地站點的部署。
- 大規模太陽能和核能發電購電協議(PPA)降低了營運成本(OPEX)。
- 政府支持的資金可以為客製化項目提供資金籌措。
- 紅海和波斯灣海底電纜的鋪設大大減少了洲際傳輸的延誤。
- 市場限制因素
- 電網瓶頸和柴油發電設施的高昂資本投資成本。
- 冷卻水短缺及廢水處理成本
- 三級/四級認證技術人員短缺
- 與資料主權相關的在地採購要求和採購障礙
- 價值供應鏈分析
- 監理情勢
- 技術展望
第5章 市場規模與成長預測
- 透過基礎設施
- 電力基礎設施
- 配電解決方案
- 配電單元
- 切換裝置
- 其他
- 備用電源解決方案
- UPS
- 發電機
- 配電解決方案
- 機械基礎設施
- 冷卻系統
- 液冷
- 空氣冷卻
- 機架和機櫃
- 其他機械基礎設施
- 冷卻系統
- IT基礎設施
- 伺服器
- 貯存
- 其他IT基礎設施
- 一般建築
- 服務(設計和諮詢、整合、支援和維護)
- 電力基礎設施
- 層級特定
- 一級和二級
- Tier III
- Tier IV
- 依資料中心類型
- 搭配
- 超大規模/內部構建
- 企業/邊緣/模組化
- 按最終用戶行業分類
- 銀行業、金融服務業及保險業
- 資訊科技/通訊
- 政府/國防
- 衛生保健
- 其他最終用戶
- 按地區
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 科威特
- 其他中東國家
第6章 競爭情勢
- 市佔率分析
- 公司簡介
- Khazna Data Centers
- Center3(stc)
- e&(formerly Etisalat)
- Gulf Data Hub
- DataVolt
- Agility Data Centers
- Equinix Inc.
- Digital Realty
- Moro Hub(DEWA)
- Oman Data Park
- Al Ghazala Data Center(Mobily)
- SAPTCO/Quantum Switch Tamasuk
- Huawei Digital Power
- Schneider Electric
- ABB Ltd.
- ALEC Engineering & Contracting
- Nesma & Partners
- Orascom Construction
- Larsen & Toubro ME
- China State Construction ME
- Trojan Group
- AtkinsRealis(SNC-Lavalin)
- Turner Construction International
- AECOM Middle East
第7章 市場機會與未來展望
According to Mordor Intelligence, the Middle East data center construction market size was valued at USD 5.24 billion in 2025 and estimated to grow from USD 6.51 billion in 2026 to reach USD 23.86 billion by 2032, at a CAGR of 24.18% during the forecast period (2026-2032).
This report is Segmented by Infrastructure (Electrical Infrastructure, Mechanical Infrastructure, IT Infrastructure, and More), Tier Type (Tier I and Tier II, Tier III, Tier IV), Data Center Type (Colocation, Hyperscale/Self-built, and More), End-User Industry (BFSI, IT and Telecommunications, Government and Defense, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Middle East Data Center Construction Market Trends and Insights
Hyperscale Cloud and AI Build-outs Accelerate Regional Infrastructure Transformation
OpenAI's partnership with G42 on the 5 GW "Stargate UAE" campus pushes rack power densities toward 80 kW and makes liquid cooling a baseline design. Microsoft's zero-water technologies further widen mechanical complexity in desert settings . These deployments raise electrical subsystem demand and anchor the Middle East data center construction market as a testbed for next-generation high-density designs.
Government Digital-Economy and Vision Programs Drive Sovereign Infrastructure Development
Saudi Arabia's draft Global AI Hub Law introduces data-embassy provisions favoring in-country build-outs . Parallel moves in the UAE and Oman embed local-content thresholds in procurement rules. The resulting predictable demand stream underwrites long-horizon capital spending and cements the Middle East data center construction market as the core platform for digital-government strategies.
Grid-Power Bottlenecks and Diesel Capex Inflation Constrain Rapid Deployment
Transmission upgrades trail demand, postponing energization by up to 18 months in Saudi growth corridors. Diesel backup systems cost 35-40% more than in 2024 due to steel and transport premiums . These factors slow near-term project starts inside the Middle East data center construction market.
Other drivers and restraints analyzed in the detailed report include:
- 5G-Edge Latency Requirements Spur Distributed Site Development
- Utility-Scale Solar and Nuclear PPAs Transform Energy Economics
- Cooling-Water Scarcity and Wastewater Fees Drive Innovation Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electrical equipment revenue rose behind growing GPU clusters, and electrical subsystems are on pace for a 27.84% CAGR. Switchgear, PDUs, and UPS units capable of 40-80 kW per rack reshape room layouts and lift structural loads. The Middle East data center construction market size for electrical systems is projected to reach USD 6.72 billion by 2032. Integration of liquid cooling pumps raises facility electrical consumption by 15-25%, blurring boundaries between mechanical and electrical trades. Service providers therefore bundle design, integration, and renewable-energy consulting into turnkey offers, deepening specialization inside the Middle East data center construction market.
Mechanical systems still absorb the largest spend because desert locations demand robust cooling. Rapid adoption of rear-door heat exchangers and direct-to-chip loops keeps mechanical share at 37.55% in 2025. Project designs now allocate extra white-space height for manifold routing and heavier chillers, increasing civil costs. Electrical and mechanical coordination thus defines project critical path and shapes competitive positioning throughout the Middle East data center construction market.
Tier III accounted for a 53.65% stake in 2025 by balancing 99.982% uptime with cost control. Banking and public-sector clients, however, push Tier IV uptake to a 21.72% CAGR to 2032 as they adopt active-active architectures. Tier IV's higher sealing and dual-bus electrical schemes uplift capex by 25-30% yet unlock premium pricing. The Middle East data center construction market share for Tier IV is poised to hit 17.45% by 2032 as regulatory and fintech workloads climb.
Edge deployments generally favor Tier II shells to speed roll-out. Modular vendors certify components in-factory, cutting site work by half and enabling 12-week go-live cycles. Uptime Institute certificates remain a procurement prerequisite, compelling smaller builders to partner with global assessors. Certification backlogs, however, accentuate the regional skills deficit and slow some Tier III upgrades inside the Middle East data center construction market.
Complete Report Scope:
- By Infrastructure
- Electrical Infrastructure
- Power Distribution Solutions
- Power Distribution Units
- Switchgears
- Others
- Power Backup Solutions
- UPS
- Generators
- Power Distribution Solutions
- Mechanical Infrastructure
- Cooling Systems
- Liquid-based Cooling
- Air-based Cooling
- Racks and Cabinets
- Other Mechanical Infrastructure
- Cooling Systems
- IT Infrastructure
- Servers
- Storage
- Other IT Infrastructure
- General Construction
- Services (Design and Consulting, Integration, Support and Maintenance)
- Electrical Infrastructure
- By Tier Type
- Tier I and Tier II
- Tier III
- Tier IV
- By Data Center Type
- Colocation
- Hyperscale / Self-built
- Enterprise / Edge / Modular
- By End-User Industry
- Banking, Financial Services and Insurance
- IT and Telecommunications
- Government and Defense
- Healthcare
- Other End Users
- By Geography
- United Arab Emirates
- Saudi Arabia
- Qatar
- Kuwait
- Rest of Middle East
List of Companies Covered in this Report:
- Khazna Data Centers
- Center3 (stc)
- e& (formerly Etisalat)
- Gulf Data Hub
- DataVolt
- Agility Data Centers
- Equinix Inc.
- Digital Realty
- Moro Hub (DEWA)
- Oman Data Park
- Al Ghazala Data Center (Mobily)
- SAPTCO / Quantum Switch Tamasuk
- Huawei Digital Power
- Schneider Electric
- ABB Ltd.
- ALEC Engineering & Contracting
- Nesma & Partners
- Orascom Construction
- Larsen & Toubro ME
- China State Construction ME
- Trojan Group
- AtkinsRealis (SNC-Lavalin)
- Turner Construction International
- AECOM Middle East
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hyperscale cloud and AI build-outs accelerate
- 4.2.2 Government digital-economy and Vision programmes
- 4.2.3 5G-edge latency requirements spur local sites
- 4.2.4 Utility-scale solar and nuclear PPAs cut OPEX
- 4.2.5 Sovereign-wealth capital enabling build-to-suit funding
- 4.2.6 Red Sea/Gulf cable landings slash inter-continental latency
- 4.3 Market Restraints
- 4.3.1 Grid-power bottlenecks and diesel capex inflation
- 4.3.2 Cooling-water scarcity and wastewater fees
- 4.3.3 Shortfall of Tier III/IV certified technicians
- 4.3.4 Local-content and data-sovereignty procurement hurdles
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Infrastructure
- 5.1.1 Electrical Infrastructure
- 5.1.1.1 Power Distribution Solutions
- 5.1.1.1.1 Power Distribution Units
- 5.1.1.1.2 Switchgears
- 5.1.1.1.3 Others
- 5.1.1.2 Power Backup Solutions
- 5.1.1.2.1 UPS
- 5.1.1.2.2 Generators
- 5.1.1.1 Power Distribution Solutions
- 5.1.2 Mechanical Infrastructure
- 5.1.2.1 Cooling Systems
- 5.1.2.1.1 Liquid-based Cooling
- 5.1.2.1.2 Air-based Cooling
- 5.1.2.2 Racks and Cabinets
- 5.1.2.3 Other Mechanical Infrastructure
- 5.1.2.1 Cooling Systems
- 5.1.3 IT Infrastructure
- 5.1.3.1 Servers
- 5.1.3.2 Storage
- 5.1.3.3 Other IT Infrastructure
- 5.1.4 General Construction
- 5.1.5 Services (Design and Consulting, Integration, Support and Maintenance)
- 5.1.1 Electrical Infrastructure
- 5.2 By Tier Type
- 5.2.1 Tier I and Tier II
- 5.2.2 Tier III
- 5.2.3 Tier IV
- 5.3 By Data Center Type
- 5.3.1 Colocation
- 5.3.2 Hyperscale / Self-built
- 5.3.3 Enterprise / Edge / Modular
- 5.4 By End-User Industry
- 5.4.1 Banking, Financial Services and Insurance
- 5.4.2 IT and Telecommunications
- 5.4.3 Government and Defense
- 5.4.4 Healthcare
- 5.4.5 Other End Users
- 5.5 By Geography
- 5.5.1 United Arab Emirates
- 5.5.2 Saudi Arabia
- 5.5.3 Qatar
- 5.5.4 Kuwait
- 5.5.5 Rest of Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Share Analysis
- 6.2 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.2.1 Khazna Data Centers
- 6.2.2 Center3 (stc)
- 6.2.3 e& (formerly Etisalat)
- 6.2.4 Gulf Data Hub
- 6.2.5 DataVolt
- 6.2.6 Agility Data Centers
- 6.2.7 Equinix Inc.
- 6.2.8 Digital Realty
- 6.2.9 Moro Hub (DEWA)
- 6.2.10 Oman Data Park
- 6.2.11 Al Ghazala Data Center (Mobily)
- 6.2.12 SAPTCO / Quantum Switch Tamasuk
- 6.2.13 Huawei Digital Power
- 6.2.14 Schneider Electric
- 6.2.15 ABB Ltd.
- 6.2.16 ALEC Engineering & Contracting
- 6.2.17 Nesma & Partners
- 6.2.18 Orascom Construction
- 6.2.19 Larsen & Toubro ME
- 6.2.20 China State Construction ME
- 6.2.21 Trojan Group
- 6.2.22 AtkinsRealis (SNC-Lavalin)
- 6.2.23 Turner Construction International
- 6.2.24 AECOM Middle East
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 亞太地區資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)南美洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)日本資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032)歐洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)法國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)義大利資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)英國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)越南資料中心建設:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)