


 |
市場調查報告書
商品編碼
2119659
義大利資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Italy Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,義大利資料中心建設市場預計到 2026 年價值 43.8 億美元,高於 2025 年的 38.2 億美元,預計到 2031 年將達到 86.3 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 14.55%。
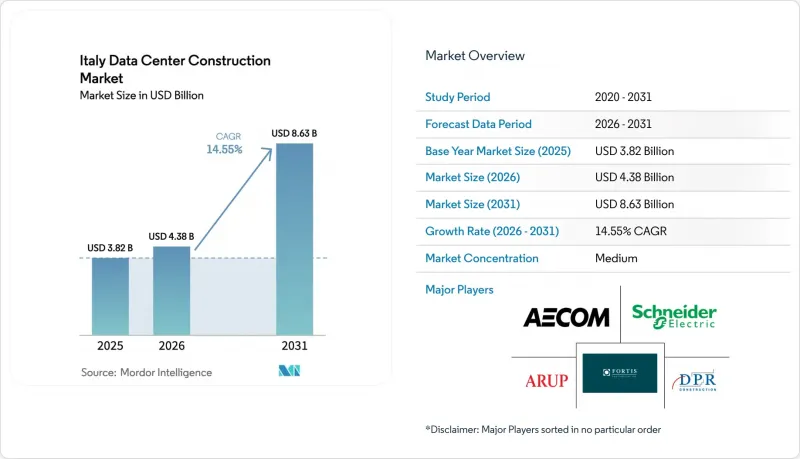
本報告按層級(一級和二級、三級、四級)、資料中心類型(託管、超大規模雲端超大規模資料中心業者(CSP) 的現場建設、企業級、邊緣運算)和基礎設施(電力基礎設施、機械基礎設施、一般建設等)對產業進行分類。市場預測以美元計價。
義大利資料中心建設市場趨勢與洞察
5G部署加速了邊緣網路和核心網路的建置。
WindTre斥資4.85億歐元收購OpNet的獨立5G資產,使得覆蓋義大利75%人口的3000個基地台投入使用,這立即加速了對微型邊緣站點的需求,以增強現有核心網路。義大利電信(TIM)的2024-2026年計畫包括新建16個資料中心,以配合全國的5G部署。此外,鳳凰鐵塔國際公司(Phoenix Tower International)計劃部署1900個站點,進一步凸顯了對低延遲容量的需求。在5G時代,工作負載分佈在無線接入網、邊緣網路和核心網路,因此,設施負責人現在優先考慮在人口密集區附近建設緊湊型站點,採用先進的液冷技術,並鋪設容錯佈線,以滿足嚴格的延遲目標。
對雲端運算和超大規模服務的需求迅速成長
谷歌雲端、微軟、AWS 和甲骨文持續投入數十億歐元,透過與義大利電信 (TIM) 及其他當地電信營運商的合作,拓展其在義大利的業務。米蘭-都靈走廊仍是此次擴張的核心,但隨著主要位置的擁塞日益加劇,區域性城市的計畫也正迅速發展。超大規模投資不僅擴大了義大利的資料中心建設市場,也促進了當地就業。都靈大學的一項研究預測,光是谷歌的生態系統到 2025 年就將創造 6.5 萬個就業機會。夥伴關係將縮短授權期限,確保符合數位主權法規,並使營運商能夠交叉銷售邊緣服務。
電網電力短缺和能源價格波動
2025年3月,電力連接需求超過42吉瓦,幾乎是可用容量的三倍,迫使營運商等待長達三年才能獲得新的輸電線路。 Terna公司投資230億歐元的電網專案可望緩解堵塞,但其效果預計要到2020年代末才能顯現。同時,一些超大規模資料中心業者正在從Enel收購退役的電力資產,以避免延誤。現貨價格上漲使得預算編制更加困難,自疫情爆發以來,建設成本指數已上漲20%,給義大利資料中心建設市場的開發商利潤率帶來了壓力。
細分市場分析
到2025年,三級資料中心將佔義大利資料中心建設市場佔有率的53.86%,反映出企業在運作和成本之間尋求平衡。然而,滿足金融、政府和人工智慧工作負載需求的四級資料中心正以每年17.48%的速度成長,預計到2031年將持續成長。由於雙電源路徑、並行維護和增強抗震性能等特性,該細分市場需要更高的資本支出(CAPEX)。 Vertiv的「CoolLoop Trim Cooler」符合即將實施的歐盟F-GAS法規,可將冷卻能耗降低70%,對於尋求合規性和降低成本的四級資料中心建造者而言,這是一款極具吸引力的產品。 Aruba位於羅馬的「IT4」資料中心擁有五棟冗餘建築、30兆瓦的IT負載以及可再生能源,正是這一趨勢的典型例證。
這種成長勢頭正蔓延至一級和二級項目,尤其是在邊緣運算和成本敏感型項目中。然而,隨著業務永續營運在經營團隊議程上的重要性日益凸顯,這些較低層級的專案正朝著容錯設計方向發展。因此,義大利資料中心建設市場正明顯轉向高可靠性,營運商沿著抗震線部署模組化的四級容量,以最大限度地降低中斷風險。
儘管到2025年託管服務將佔據55.94%的市場佔有率,但超大規模資料中心業者營運商的自建項目正以每年18.98%的速度成長。微軟在義大利北部投資43億歐元部署人工智慧架構,正是這項轉變的象徵。谷歌雲端透過在米蘭和都靈租賃TIM公司的空間,將自建與外包結合,展現了兼顧速度和合規性的混合模式。預計到2031年,此一趨勢將推動義大利超大規模資料中心建設市場規模成長至約23.9億美元,佔總價值的27.65%。
儘管邊緣運算和企業級資料中心的建設正經歷溫和成長,但它仍然是實現地域多角化的基礎。 「先建後租」模式減輕了超大規模超大規模資料中心業者的資本密集負擔。例如, Oracle的都靈資料中心位於 TIM 園區內,無需直接擁有土地即可實現運轉率和資料主權目標。退休基金和基礎設施基金正成為積極的房地產所有者,透過將可預測的 20 年超大規模資料中心業者資料中心營運商租賃協議轉化為類似債券的回報,為義大利資料中心建設產業注入新的資金。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 5G 的部署正在加速邊緣網路和核心網路的建置。
- 對雲端運算和超大規模雲端的需求激增
- 政府為「Piano Nazionale di Ripresa e Resilienza (PNRR)」提供的數位津貼
- 加強永續發展法規和綠色能源採購
- 一條新的海底電纜的鋪設,鞏固了義大利作為互聯互通樞紐的地位。
- 超大規模資料中心業者更傾向於採用「先建後租」模式,以避免授權流程的延誤。
- 市場限制因素
- 電網電力短缺和能源價格波動
- 資料中心建置專業人員短缺
- 地震多發地區的建築成本推高了資本投資。
- 高層冷卻系統中再生水的應用受到限制。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 資料中心關鍵統計數據
- 義大利資料中心營運商列表(按兆瓦計)
- 義大利即將建置的主要資料中心專案清單(2025-2030 年)
- 義大利資料中心建設中的資本支出和營運支出
- 2023 年和 2024 年義大利主要城市的資料中心電力消耗量(單位:兆瓦)。
第6章:人工智慧(AI)在義大利資料中心建置的應用
第7章 監理與合規框架
第8章 市場規模與成長預測
- 層級特定
- 一級和二級
- 三級
- 第四級
- 依資料中心類型
- 搭配
- 自主研發的超大規模資料中心業者(CSP)
- 企業和邊緣運算
- 透過基礎設施
- 透過電力基礎設施
- 配電解決方案
- 備用電源解決方案
- 透過機械基礎設施
- 冷卻系統
- 機架和機櫃
- 伺服器和儲存
- 其他機械基礎設施
- 一般建築
- 服務 - 設計與諮詢、整合、支援與維護
- 透過電力基礎設施
第9章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- Data Center Infrastructure Investment Based on Megawatt(MW)Capacity, 2024 vs 2030
- Data Center Construction Landscape(Key Vendors Listings)
- 公司簡介
- AECOM Srl
- Arup Group Limited
- DPR Construction, Inc.
- Schneider Electric SE
- Fortis Construction, Inc.
- IBM Italia SpA
- Airedale International Air Conditioning Ltd.
- Legrand SpA
- Datacentre UK Ltd.
- Castrol Limited
- Honeywell International Inc.
- Johnson Controls International plc
- Datadome Group Srl
- STULZ GmbH
- Daikin Industries Ltd.
- List of Data Center Construction Companies
第10章 市場機會與未來展望
- 評估未開發的領域和未滿足的需求
According to Mordor Intelligence, Italy data center construction market size in 2026 is estimated at USD 4.38 billion, growing from 2025 value of USD 3.82 billion with 2031 projections showing USD 8.63 billion, growing at 14.55% CAGR over 2026-2031.
This report Segments the Industry Into Tier Type (Tier 1 and 2, Tier 3, Tier 4), Data Center Type (Colocation, Self-Build Hyperscalers (CSPs), Enterprise and Edge), Infrastructure (Electrical Infrastructure, Mechanical Infrastructure, General Construction, and More). The Market Forecasts are Provided in Terms of Value (USD).
Italy Data Center Construction Market Trends and Insights
5G rollout accelerating edge and core builds
WindTre's EUR 485 million purchase of OpNet's standalone 5G assets unlocked 3,000 base stations serving 75% of Italy's population, spurring immediate demand for micro-edge sites that reinforce traditional cores. TIM's 2024-2026 plan maps 16 new data centers that dovetail with this national 5G push, and Phoenix Tower International's 1,900-site program further underlines the need for low-latency capacity. Because 5G splits workloads between radio, edge, and core, facility planners now prioritize smaller footprints near population clusters, advanced liquid-assisted cooling, and resilient distribution paths to meet stringent latency targets.
Surging cloud and hyperscale demand
Google Cloud, Microsoft, AWS, and Oracle continue to earmark multi-billion-euro budgets for Italian expansion, often in partnership with TIM or other local carriers. The Milan-Turin corridor has become the epicenter, yet secondary cities are quickly absorbing projects as prime sites tighten. Hyperscale investment not only enlarges the Italy data center construction market but also boosts local employment, with University of Turin research projecting 65,000 jobs by 2025 from the Google ecosystem alone. Partnerships shorten permitting cycles, ensure compliance with digital-sovereignty rules, and allow carriers to cross-sell edge services.
Grid-power scarcity and volatile energy prices
Connection requests topped 42 GW in March 2025-almost triple available headroom-forcing operators to queue as long as three years for new feeds. Terna's EUR 23 billion grid plan will ease congestion but not before late decade. Meanwhile, some hyperscalers buy retired Enel power assets to avoid delays. Rising spot prices complicate budgeting, and construction cost indices have risen 20% since the pandemic, squeezing margins for developers across the Italy data center construction market.
Other drivers and restraints analyzed in the detailed report include:
- Government "PNRR" digital grants
- Rising sustainability mandates and green energy sourcing
- Shortage of specialised data-center construction labour
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 facilities controlled 53.86% of the Italy data center construction market share in 2025 as enterprises sought balanced uptime and cost. Nevertheless Tier 4 sites, required by finance, government, and AI workloads, expand 17.48% each year to 2031. This segment commands higher CAPEX due to dual power paths, concurrent maintainability, and seismic hardening. Vertiv's CoolLoop Trim Cooler, compliant with impending EU F-GAS rules, cuts cooling energy 70%, making it attractive to Tier 4 builders seeking compliance and savings. Aruba's IT4 in Rome exemplifies this trend with five duplicate buildings, 30 MW IT load, and renewable power.
Growth momentum also ripples down to Tier 1 and Tier 2 for edge or cost-sensitive projects. Yet as business continuity rises on boardroom agendas, these lower tiers are yielding share to fault-tolerant designs. The Italy data center construction market therefore shows a clear shift toward premium reliability, with operators positioning modular Tier 4 capacity along seismic lines to minimize disruption risk.
Despite colocation's 55.94% 2025 base, self-build hyperscaler projects rise 18.98% per year. Microsoft's EUR 4.3 billion investment in Northern Italy, paired with AI-ready architecture, typifies this pivot. Google Cloud blends self-build and outsource by leasing space from TIM in Milan and Turin, illustrating hybrid forms that optimize speed and compliance. This wave enlarges the Italy data center construction market size for hyperscale to an estimated USD 2.39 billion by 2031, equal to 27.65% of total value.
Edge and enterprise builds grow moderately but still anchor regional diversification. The build-to-lease model lowers capital-heavy lifting for hyperscalers: Oracle's Turin region runs inside a TIM campus, meeting uptime and sovereignty goals without direct land ownership. Pension and infrastructure funds are eager landlords, turning predictable 20-year hyperscale leases into bond-like returns, and thereby injecting new capital into the Italy data center construction industry.
Complete Report Scope:
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
List of Companies Covered in this Report:
- AECOM S.r.l.
- Arup Group Limited
- DPR Construction, Inc.
- Schneider Electric SE
- Fortis Construction, Inc.
- IBM Italia S.p.A.
- Airedale International Air Conditioning Ltd.
- Legrand S.p.A.
- Datacentre UK Ltd.
- Castrol Limited
- Honeywell International Inc.
- Johnson Controls International plc
- Datadome Group S.r.l.
- STULZ GmbH
- Daikin Industries Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G rollout accelerating edge and core builds
- 4.2.2 Surging cloud and hyperscale demand
- 4.2.3 Government "Piano Nazionale di Ripresa e Resilienza (PNRR)" digital grants
- 4.2.4 Rising sustainability mandates and green energy sourcing
- 4.2.5 New subsea cable landings boosting Italy's connectivity hub status
- 4.2.6 Build-to-lease model favoured by hyperscalers to bypass permitting delays
- 4.3 Market Restraints
- 4.3.1 Grid-power scarcity and volatile energy prices
- 4.3.2 Shortage of specialised data-center construction labour
- 4.3.3 Seismic-zone engineering costs raising capex
- 4.3.4 Limited reclaimed-water access for advanced cooling
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 KEY DATA CENTER STATISTICS
- 5.1 Exhaustive Data Center Operators in Italy (in MW)
- 5.2 List of Major Upcoming Data Center Projects in Italy (2025-2030)
- 5.3 CAPEX and OPEX For Italy Data Center Construction
- 5.4 Data Center Power Capacity Absorption In MW, Selected Cities, Italy, 2023 and 2024
6 ARTIFICIAL INTELLIGENCE (AI) INCLUSION IN DATA CENTER CONSTRUCTION IN ITALY
7 REGULATORY and COMPLIANCE FRAMEWORK
8 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 8.1 By Tier Type
- 8.1.1 Tier 1 and 2
- 8.1.2 Tier 3
- 8.1.3 Tier 4
- 8.2 By Data Center Type
- 8.2.1 Colocation
- 8.2.2 Self-build Hyperscalers (CSPs)
- 8.2.3 Enterprise and Edge
- 8.3 By Infrastructure
- 8.3.1 By Electrical Infrastructure
- 8.3.1.1 Power Distribution Solution
- 8.3.1.2 Power Backup Solutions
- 8.3.2 By Mechanical Infrastructure
- 8.3.2.1 Cooling Systems
- 8.3.2.2 Racks and Cabinets
- 8.3.2.3 Servers and Storage
- 8.3.2.4 Other Mechanical Infrastructure
- 8.3.3 General Construction
- 8.3.4 Service - Design and Consulting, Integration, Support and Maintenance
- 8.3.1 By Electrical Infrastructure
9 COMPETITIVE LANDSCAPE
- 9.1 Market Concentration
- 9.2 Strategic Moves
- 9.3 Market Share Analysis
- 9.4 Data Center Infrastructure Investment Based on Megawatt (MW) Capacity, 2024 vs 2030
- 9.5 Data Center Construction Landscape (Key Vendors Listings)
- 9.6 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 9.6.1 AECOM S.r.l.
- 9.6.2 Arup Group Limited
- 9.6.3 DPR Construction, Inc.
- 9.6.4 Schneider Electric SE
- 9.6.5 Fortis Construction, Inc.
- 9.6.6 IBM Italia S.p.A.
- 9.6.7 Airedale International Air Conditioning Ltd.
- 9.6.8 Legrand S.p.A.
- 9.6.9 Datacentre UK Ltd.
- 9.6.10 Castrol Limited
- 9.6.11 Honeywell International Inc.
- 9.6.12 Johnson Controls International plc
- 9.6.13 Datadome Group S.r.l.
- 9.6.14 STULZ GmbH
- 9.6.15 Daikin Industries Ltd.
- 9.7 List of Data Center Construction Companies
10 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 10.1 White-space and Unmet-Need Assessment

 中東資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032 年)亞太地區資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)南美洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)日本資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032)歐洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)法國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)英國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)越南資料中心建設:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)