

 |
市場調查報告書
商品編碼
2124694
新加坡金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Singapore Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,新加坡金融科技市場在 2026 年的價值將達到 139.7 億美元,高於 2025 年的 120.5 億美元,預計到 2031 年將達到 292.2 億美元。
預計 2026 年至 2031 年的複合年成長率為 15.9%。
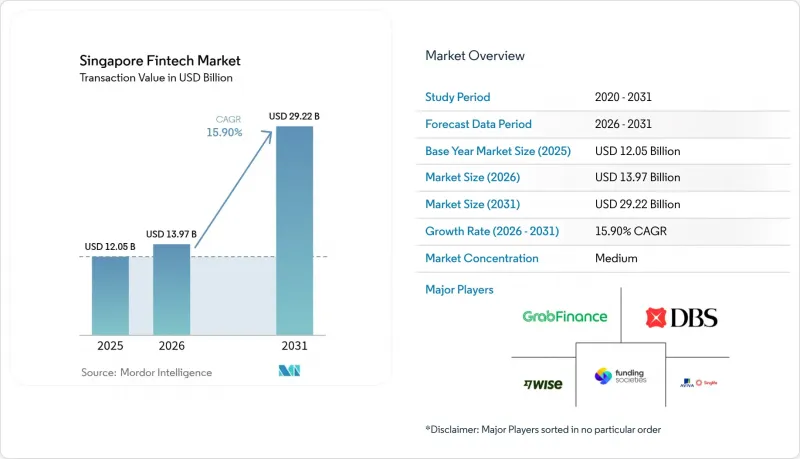
本報告按服務領域(數位支付、數位借貸和資金籌措、數位投資、保險科技、新型銀行)、最終用戶(個人、企業)、用戶介面(行動應用、網頁/瀏覽器、POS/物聯網設備)和地區(中部地區、東部地區、北部地區、東北部地區、西部地區)細分。市場預測以美元計價。
新加坡金融科技市場趨勢與洞察
即時支付網路正在改變支付的經濟格局。
「Nexus專案」計畫於2026年前連接新加坡、馬來西亞、泰國、菲律賓和印度的支付網路,屆時將不再需要代理行帳戶,結算時間也將從T+2縮短至即時結算。這項轉變預計將釋放約1,200億美元的閒置流動性,並降低跨境交易費用,進而為商家和中小企業節省成本。率先整合的金融科技公司可望擴大其在B2B貿易融資領域的市場佔有率,即時結算將使與貨物運輸里程碑掛鉤的營運資金產品成為可能。 PayNow與PromptPay和DuitNow建立的雙邊合作關係在2024年處理了超過250萬筆交易,顯示該地區客戶對即時結算的需求旺盛。隨著支付基礎設施的整合,傳統銀行必須對其遺留API進行現代化改造,否則將面臨將利潤豐厚的交易領域拱手讓給敏捷型新興企業的風險。這項新的基礎設施還支持小額支付和微額保險,從而拓展了其在東南亞地區的應用場景。
為抗量子創新提供資金可以加速競爭差異化。
透過 FSTI 3.0 計劃,新加坡金融管理局 (MAS) 將為實施抗量子加密和人工智慧風險分析的專案提供高達 50% 的共同資助。這項津貼降低了中型金融科技公司的資本投資門檻,使它們能夠在監管要求訂定之前加強網路安全態勢。網路技術韌性專家 (CTREX) 小組的合作確保了來自微軟、亞馬遜和谷歌雲端的知識轉移,使國家標準與全球最佳實踐保持一致。領先企業已經在測試能夠抵禦 Shor 演算法攻擊的抗量子支付協議,為後量子加密成為強制性要求時滿足合規性要求做好準備。採用抗量子金鑰交換的銀行正在保護高價值資金轉移,鞏固了新加坡在「安全港」金融託管領域的先鋒優勢。從長遠來看,利用量子技術的最佳化可以簡化信用風險建模和投資組合再平衡,從而有可能提高整個產業的生產力。
客戶獲取成本是金融科技公司盈利模式的一大負擔。
隨著智慧型手機普及率接近100%,目標基本客群已趨於飽和,獲取新客戶的邊際成本飆升。預計到2024年,新電子錢包註冊的獎勵預算將增加40%至60%,這將導致小規模金融科技公司的投資回收期超過30個月。此外,隨著消費者越來越傾向於使用Grab等集網約車、外帶和支付功能於一體的多功能超級應用,應用疲勞進一步降低了行銷投資報酬率。這一趨勢迫使獨立供應商轉向嵌入式金融夥伴關係,將其服務整合到商家和平台生態系統中,並分攤客戶以獲取成本。 B2B2C分銷模式也有助於提高單位經濟效益。例如,中小企業的軟體供應商可以透過引入與發票掛鉤的信用額度,將行銷成本分攤到多個收入來源。因此,飆升的客戶獲取成本起到了一種選擇機制的作用,它獎勵那些擁有強大生態系統和差異化知識產權的金融科技公司,同時迫使實力較弱的新創公司進行合併或退出市場。
細分市場分析
到2025年,數位支付將佔新加坡金融科技市場規模的26.20%,這反映了其在日常商業活動中的核心地位。預計到2031年,該領域將以16.95%的複合年成長率成長,主要得益於SGQR+互通性、商家對SoftPOS的採用以及PayNow的區域連結性。繞過卡片付款網路的帳戶間轉帳正在降低交換費,並鼓勵商家優先考慮QR CODE支付和即時支付。同時,數位借貸領域的替代信用評分繼續為零工經濟從業者提供快速核准和發放的小額貸款,儘管其成長速度低於支付領域。保險科技公司正在將小額保險整合到叫車和外帶應用程式中,在無需客戶購買單獨保險的情況下擴大了服務範圍。像StashAway這樣的財富科技平台正在利用低成本的ETF投資組合擴大規模,挑戰私人銀行在大眾資產領域的地位。新加坡金融管理局(MAS)的監理沙盒支援對支付、貸款和保險進行整合試驗,以促進提供全面的金融服務。預計到2030年,整合平台將佔該國零售交易額的40%以上,從而鞏固支付作為更廣泛的金融科技生態系統基石的地位。
隨著數位錢包供應商不斷擴大信用額度並推出基於保險的附加服務,傳統細分市場之間的界線日益模糊,競爭也愈發激烈。超級應用程式正利用自身用戶資料最佳化信用評估,而老牌公司則開放API介面,以維持其在商家支付流程中的地位。因此,新加坡的金融科技市場仍青睞那些能夠掌控銷售點(POS)並為高頻支付場景提供高利潤附加服務的供應商。監管機構對代幣化存款和網路代幣化的支持,進一步提升了安全性和交易效率。隨著即時支付基礎設施的日趨成熟,支付收入將越來越多來自增值數據分析、忠誠度計畫和支付服務,而不是單筆交易手續費。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 即時支付系統(PayNow、Project Nexus)的快速普及
- 新加坡金融管理局的津貼正在推動人工智慧和量子技術在金融科技領域的創新。
- 跨境電子商務正在推動多幣種錢包的普及。
- 純數位銀行牌照開闢了新的細分市場。
- ESG(環境、社會和治理)和綠色金融需求正在為金融科技創造新的收入來源。
- 中小企業信貸缺口正在推動另類貸款平台的發展。
- 市場限制因素
- 由於應用程式之間的激烈競爭,獲客成本很高。
- 加強新加坡金融管理局關於加密貨幣和先買後付的消費者保護條例
- 人工智慧和網路安全領域的人才短缺正在推高營運成本(OPEX)。
- 與傳統核心銀行系統互通性和整合方面的挑戰
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 服務方案
- 數位支付
- 數位借貸金融
- 數位投資
- 保險科技
- 新銀行
- 最終用戶
- 零售
- 公司
- 透過使用者介面
- 行動應用
- 網頁/瀏覽器
- POS/物聯網設備
- 按地區
- 日本中部
- 東部地區
- 北部地區
- 東北部地區
- 西部地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Grab Financial Group
- DBS Bank
- OCBC Bank
- UOB Bank
- PayPal Singapore
- Wise
- Stripe Singapore
- Adyen Singapore
- Nium
- Thunes
- FOMO Pay
- Funding Societies
- Validus
- StashAway
- Endowus
- Singlife with Aviva
- Bolttech
- GXS Bank
- Trust Bank
- ANEXT Bank
- Revolut Singapore
第7章 市場機會與未來展望
According to Mordor Intelligence, Singapore fintech market size in 2026 is estimated at USD 13.97 billion, growing from 2025 value of USD 12.05 billion with 2031 projections showing USD 29.22 billion, growing at 15.9% CAGR over 2026-2031.
This report is Segmented by Service Proposition (Digital Payments, Digital Lending & Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), and Geography (Central Region, East Region, North Region, North-East Region, West Region). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Fintech Market Trends and Insights
Real-Time Payment Rails Transform Settlement Economics
Project Nexus will connect payment rails in Singapore, Malaysia, Thailand, the Philippines, and India by 2026, eliminating the need for nostro accounts and cutting settlement from T+2 to real-time . The shift frees up an estimated USD 120 billion in trapped liquidity and reduces cross-border transaction fees, generating immediate cost savings for merchants and SMEs. Early integrating fintech firms will gain share in B2B trade finance, where real-time settlement unlocks working-capital products tied to shipment milestones. PayNow's bilateral links with PromptPay and DuitNow processed more than 2.5 million transactions in 2024, demonstrating proven customer appetite for instant regional payments. As rails converge, traditional banks must overhaul legacy APIs or risk ceding high-margin corridors to nimble challengers. The new infrastructure also supports micropayments and micro-insurance, widening addressable use cases across Southeast Asia.
Quantum-Ready Innovation Funding Accelerates Competitive Differentiation
Through FSTI 3.0, MAS co-funds up to 50% of projects deploying quantum-resistant encryption and AI-powered risk analytics. The subsidy lowers capex barriers for mid-tier fintechs, enabling them to harden cybersecurity stacks ahead of regulatory mandates. Collaboration inside the Cyber and Technology Resilience Experts (CTREX) panel ensures knowledge transfer from Microsoft, Amazon, and Google Cloud, aligning domestic standards with global best practices. Early movers already test quantum-safe payment protocols that withstand Shor-algorithm attacks, positioning them for compliance once post-quantum cryptography becomes compulsory. Banks adopting quantum-secure key exchange safeguard high-value treasury flows, giving Singapore a first-mover lead in safe-harbor financial hosting. Over the long term, quantum-enhanced optimization may also streamline credit-risk modelling and portfolio rebalancing, boosting sector productivity.
Customer Acquisition Costs Strain Fintech Profitability Models
Nearly universal smartphone ownership produces a saturated addressable base, making marginal customer wins increasingly expensive. Incentive budgets for e-wallet sign-ups ballooned by 40-60% in 2024, pushing payback periods for small fintechs beyond 30 months. App fatigue further erodes return on marketing spend because consumers prefer multifunction super-apps such as Grab, which bundle ride-hailing, food delivery, and payments. The trend forces standalone providers to pivot toward embedded-finance partnerships, integrating services into merchant or platform ecosystems to share acquisition costs. B2B2C distribution also improves unit economics; SME software vendors, for example, can embed invoicing-linked credit lines, spreading marketing costs across multiple revenue streams. Elevated acquisition costs therefore act as a filtering mechanism, rewarding fintechs with strong ecosystems or differentiated IP, while pushing under-capitalized startups to consolidate or exit.
Other drivers and restraints analyzed in the detailed report include:
- Cross-Border E-Commerce Growth Drives Multi-Currency Innovation
- Digital Banking Licenses Create Niche Market Opportunities
- Regulatory Tightening Constrains High-Growth Fintech Segments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, digital payments accounted for 26.20% of the Singapore fintech market size, reflecting their central role in day-to-day commerce. The segment is on track to expand at a 16.95% CAGR through 2031, propelled by SGQR+ interoperability, merchant SoftPOS adoption, and PayNow's regional links. Card-rail bypass via account-to-account transfers reduces interchange fees, encouraging merchants to prioritize QR and instant payments. Meanwhile, alternative credit scoring in digital lending continues to unlock quick-turnaround microloans for gig workers, albeit at a slower growth than payments. Insurtech firms embed bite-sized coverage within ride-hailing and delivery apps, widening reach without requiring stand-alone policy purchases. Wealth-tech platforms such as StashAway scale on low-cost ETF portfolios, challenging private banks for mass-affluent assets. MAS's regulatory sandbox supports experiments that bundle payments, lending, and insurance, fostering holistic financial offerings. By 2030, integrated platforms are expected to direct more than 40% of domestic retail transaction value, cementing payments as the linchpin of broader fintech ecosystems.
Competition intensifies as digital-wallet providers extend credit lines and insurance add-ons, blurring traditional segment boundaries. Super-apps leverage first-party consumption data to refine underwriting, while incumbents open APIs to retain relevance within merchant checkout flows. The Singapore fintech market, therefore, continues to reward providers that control the point of sale and can layer higher-margin, add-on services onto high-frequency payment use cases. Regulatory support for tokenized deposits and network tokenization further improves security and interchange economics. As real-time rails mature, payments revenue will increasingly derive from value-added data analytics, loyalty, and payment services rather than per-transaction fees.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending & Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
- By Geography
- Central Region
- East Region
- North Region
- North-East Region
- West Region
List of Companies Covered in this Report:
- Grab Financial Group
- DBS Bank
- OCBC Bank
- UOB Bank
- PayPal Singapore
- Wise
- Stripe Singapore
- Adyen Singapore
- Nium
- Thunes
- FOMO Pay
- Funding Societies
- Validus
- StashAway
- Endowus
- Singlife with Aviva
- Bolttech
- GXS Bank
- Trust Bank
- ANEXT Bank
- Revolut Singapore
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid real-time payment rail adoption (PayNow, Project Nexus)
- 4.2.2 MAS grants spurring AI & quantum-ready fintech innovation
- 4.2.3 Cross-border e-commerce fueling multi-currency wallets
- 4.2.4 Digital-only banking licences opening new niches
- 4.2.5 ESG & green-finance mandates creating new fintech revenue pools
- 4.2.6 SME credit gap boosting alternative lending platforms
- 4.3 Market Restraints
- 4.3.1 High customer-acquisition costs amid intense app competition
- 4.3.2 Tightened MAS consumer-protection rules on crypto & BNPL
- 4.3.3 Talent shortages in AI / cybersecurity raising OPEX
- 4.3.4 Interoperability & legacy core-bank integration hurdles
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending & Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
- 5.4 By Geography
- 5.4.1 Central Region
- 5.4.2 East Region
- 5.4.3 North Region
- 5.4.4 North-East Region
- 5.4.5 West Region
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Grab Financial Group
- 6.4.2 DBS Bank
- 6.4.3 OCBC Bank
- 6.4.4 UOB Bank
- 6.4.5 PayPal Singapore
- 6.4.6 Wise
- 6.4.7 Stripe Singapore
- 6.4.8 Adyen Singapore
- 6.4.9 Nium
- 6.4.10 Thunes
- 6.4.11 FOMO Pay
- 6.4.12 Funding Societies
- 6.4.13 Validus
- 6.4.14 StashAway
- 6.4.15 Endowus
- 6.4.16 Singlife with Aviva
- 6.4.17 Bolttech
- 6.4.18 GXS Bank
- 6.4.19 Trust Bank
- 6.4.20 ANEXT Bank
- 6.4.21 Revolut Singapore
7 Market Opportunities & Future Outlook
- 7.1 Embedded finance in non-financial super-apps
- 7.2 Green fintech solutions for carbon-credit trading

 中東和北非金融科技:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)亞太地區金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美金融科技:市佔率分析、產業趨勢與統計及成長預測(2026-2031)德國金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)歐洲金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)越南金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)金融科技:市場佔有率分析、產業趨勢與統計、成長預測(2025-2030)印度金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 金融科技即服務 (FaaS) 市場 - 全球市場預測 2026-2032