

 |
市場調查報告書
商品編碼
2124689
中東和北非金融科技:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)MENA Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,中東和北非的金融科技市場規模預計在 2026 年達到 63.5 億美元,高於 2025 年的 56.5 億美元,預計到 2031 年將達到 114.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 12.52%。
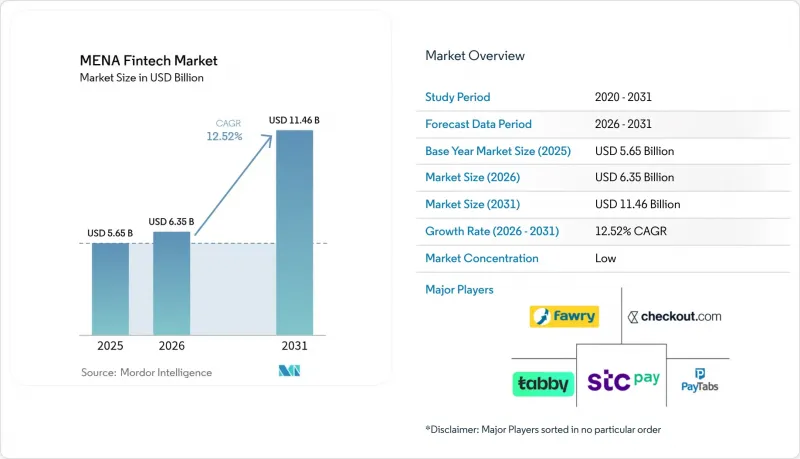
本報告按服務類型(數位支付、數位借貸和資金籌措、數位投資、保險科技、新銀行)、最終用戶(個人、企業)、用戶介面(行動應用程式、網頁/瀏覽器、POS/物聯網設備)和地區(海灣合作理事會、北非、黎凡特)進行細分。市場預測以美元計價。
中東及北非金融科技市場趨勢及洞察
政府推行無現金社會和普惠金融的措施正在加速對金融科技的需求。
沙烏地阿拉伯的目標是到2030年實現70%的交易無現金化,埃及的目標是到2025年實現50%的成年人擁有銀行帳戶。阿拉伯聯合大公國也於2024年簡化了其牌照發放程序。這些目標清楚地顯示了金融科技的普及程度,並降低了私人企業進入市場的門檻。約旦的監管沙盒機制進一步降低了監管風險,並幫助新創公司在無需承擔過高遵循成本的情況下拓展業務。隨著各國政府推動工資和福利支付的數位化,消費者對電子錢包的熟悉度日益提高,獲客成本也不斷降低。這些政策也激勵獎勵採用非接觸式支付,進而擴展支付網路。這些政策共同作用,形成良性循環,推動了中東和北非金融科技市場的發展。
行動和網路普及率的快速成長,使得行動優先的資金取得成為可能。
在海灣合作理事會(GCC)國家,智慧型手機普及率超過80%,行動端已成為銀行交易的預設管道。在阿拉伯聯合大公國,數位錢包已佔POS消費的18%,預計2027年將達到33%。埃及和摩洛哥正透過基於電信的代理模式擴大服務覆蓋範圍,無需分店基礎設施,從而降低營運成本。 Z世代用戶透過數位錢包消費佔當地電子商務消費的23%,正在養成永續的支付習慣。北非農村地區4G/5G網路覆蓋範圍的擴展,使得遠端KYC(了解你的客戶)帳戶開立成為可能,從而催生了新的客戶群。因此,「行動優先」模式正在推動所有消費群體市場佔有率的快速成長。
不同司法管轄區的法規差異增加了合規負擔。
19種不同的許可證制度要求金融科技公司在每個市場設立獨立的營業單位,與統一的框架相比,這會使營運成本增加15%至25%。資本監管和數據本地化規則的差異阻礙了通行證制度的使用,並減緩了區域擴張。雖然大型成熟公司能夠承擔這些成本,但新創公司卻面臨資源限制和創新多樣性不足的問題。缺乏相互認可也阻礙了跨國開放API的整合,造成了整合「死角」。投資人正在將這些風險納入公司估值,並推動產業整合,以此作為跨國擴張的變通方案。
細分市場分析
到2025年,數位支付在中東和北非金融科技市場中將佔據54.12%的佔有率。這得歸功於智慧型手機錢包的普及以及為吸引商家而採取的積極獎勵。在這一細分領域,QR碼和代幣化錢包支付等新型支付方式的出現,進一步提高了用戶留存率。數位借貸雖然規模較小,但憑藉其利用即時替代數據進行評分的優勢,正以17.74%的複合年成長率快速成長。 Fawry預計到2025年貸款發放將達到10億英鎊,這表明支付和信貸之間存在著密切的聯繫。
智慧投顧和保險科技服務正透過API優先的分銷模式不斷擴張,而像STC銀行這樣的新型銀行則正將其電子錢包用戶群轉化為全方位服務帳戶用戶。監理沙盒允許推出參數型和基於使用量的保險產品,促進了實驗性措施的發展。支付品牌透過在同一應用程式中加入信貸、投資和保險標籤,創造交叉銷售綜效,提升用戶終身價值。這種多元化趨勢表明,平台融合正在中東和北非整個金融科技市場加速發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府的政策旨在促進無現金社會和普惠金融。
- 行動和網路普及率的快速成長
- 創業投資與沙盒模式的資金籌措勢頭
- 央行數位貨幣跨境支付試點項目
- 電子商務與零工平台對嵌入式金融的需求
- 即時結算網路能夠使用替代貸款資料。
- 市場限制因素
- 不同司法管轄區的法規有差異
- 在北非,以現金為中心的文化正在推高 CAC(普通事故賠償)。
- 缺乏用於人工智慧/機器學習風險評分的阿拉伯語資料集
- 傳統核心銀行體系的IT瓶頸
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 服務方案
- 數位支付
- 數位借貸金融
- 數位投資
- 保險科技
- 新銀行
- 最終用戶
- 零售
- 公司
- 透過使用者介面
- 行動應用
- 網頁/瀏覽器
- POS/物聯網設備
- 按地區
- GCC
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 巴林
- 科威特
- 阿曼
- 北非
- 埃及
- 摩洛哥
- 阿爾及利亞
- 突尼西亞
- 黎凡特
- 約旦
- 黎巴嫩
- GCC
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Fawry
- PayTabs
- Checkout.com
- Tabby
- Tamara
- STC Pay
- Paymob
- MNT-Halan
- Geidea
- Network International
- BenefitPay
- Careem Pay
- Lean Technologies
- HyperPay
- YAP
- Telda
- NymCard
- Sarwa
- OPay
第7章 市場機會與未來展望
According to Mordor Intelligence, MENA fintech market size in 2026 is estimated at USD 6.35 billion, growing from 2025 value of USD 5.65 billion with 2031 projections showing USD 11.46 billion, growing at 12.52% CAGR over 2026-2031.
This report is Segmented by Service Proposition (Digital Payments, Digital Lending & Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), and Geography (GCC, North Africa, Levant). The Market Forecasts are Provided in Terms of Value (USD).
MENA Fintech Market Trends and Insights
Government Cash-Lite & Financial-Inclusion Mandates Accelerate Fintech Demand
Saudi Arabia targets 70% cashless transactions by 2030, Egypt aims to bank 50% of adults by 2025, and the UAE streamlined licensing in 2024. These targets provide clear metrics for adoption and reduce go-to-market friction for private players. Sandboxes in Jordan further cut regulatory risk, helping startups scale without prohibitive compliance spend. As governments digitize payroll and welfare transfers, consumer familiarity with e-wallets rises, lowering acquisition costs. The policy push also incentivizes retailers to deploy contactless acceptance, enlarging acceptance networks. Collectively, mandates create a virtuous circle that widens the MENA fintech market.
Mobile & Internet Penetration Surge Enables Mobile-First Financial Access
Smartphone penetration tops 80% in GCC states, turning mobiles into the default banking channel. The UAE already sees digital wallets covering 18% of POS spend, on track for 33% by 2027. Egypt and Morocco extend reach through telco-based agent models, bypassing branch infrastructure and shrinking operating costs. Gen Z users account for 23% of regional e-commerce spend via digital wallets, establishing lasting payment habits. Growing 4G/5G coverage in rural North Africa enables remote KYC onboarding, unlocking new customer pools. The mobile-first model thus propels rapid share gains across consumer cohorts.
Regulatory Fragmentation Across Jurisdictions Increases Compliance Burden
Nineteen different licensing regimes require fintechs to form market-specific entities, adding 15-25% to overheads versus unified frameworks. Disparate capital and data-localization rules hinder passporting and delay regional scaling. Larger incumbents absorb the cost but startups face resource strain, limiting innovation diversity. Lack of mutual recognition also hampers cross-border open-API linkage, creating integration dead-zones. Investors price the risk into valuations, nudging consolidation as a workaround for multi-country reach.
Other drivers and restraints analyzed in the detailed report include:
- VC Funding & Sandbox Momentum Fuel Startup Formation
- CBDC Pilots Enabling Cross-Border Rails Create Common API Infrastructure
- Cash-Centric Habits Inflate Customer-Acquisition Costs in North Africa
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Digital payments controlled 54.12% of MENA fintech market share in 2025, underpinned by near-ubiquitous smartphone wallets and aggressive merchant-acquiring incentives. The sub-segment added new rails such as QR and tokenized wallet checkout, further cementing stickiness. Digital lending, though smaller, is growing at an 17.74% CAGR on the strength of real-time alternative-data scoring. Fawry's EGP 1 billion disbursement surge in 2025 illustrates payments-to-credit adjacency.
Robo-advisory and insurtech expand via API-first distribution, while neobanks like STC Bank convert wallet bases into full-service accounts. Regulatory sandboxes allow parametric and usage-based policies, fostering experimentation. Cross-sell synergies emerge as payments brands add credit, investment, and insurance tabs within the same app, stretching user lifetime value. The diversification push points to escalating platform convergence across the MENA fintech market.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending & Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
- By Geography
- GCC
- Saudi Arabia
- United Arab Emirates
- Qatar
- Bahrain
- Kuwait
- Oman
- North Africa
- Egypt
- Morocco
- Algeria
- Tunisia
- Levant
- Jordan
- Lebanon
- GCC
List of Companies Covered in this Report:
- Fawry
- PayTabs
- Checkout.com
- Tabby
- Tamara
- STC Pay
- Paymob
- MNT-Halan
- Geidea
- Network International
- BenefitPay
- Careem Pay
- Lean Technologies
- HyperPay
- YAP
- Telda
- NymCard
- Sarwa
- OPay
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Govt cash-lite and financial-inclusion mandates
- 4.2.2 Mobile & internet penetration surge
- 4.2.3 VC funding & sandbox momentum
- 4.2.4 CBDC pilots enabling cross-border rails
- 4.2.5 Embedded-finance demand from e-commerce and gig platforms
- 4.2.6 Instant-payment rails unlocking alternative lending data
- 4.3 Market Restraints
- 4.3.1 Regulatory fragmentation across jurisdictions
- 4.3.2 Cash-centric habits inflating CAC in North Africa
- 4.3.3 Scarcity of Arabic AI/ML risk-scoring datasets
- 4.3.4 Legacy core-bank IT bottlenecks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending & Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
- 5.4 By Geography
- 5.4.1 GCC
- 5.4.1.1 Saudi Arabia
- 5.4.1.2 United Arab Emirates
- 5.4.1.3 Qatar
- 5.4.1.4 Bahrain
- 5.4.1.5 Kuwait
- 5.4.1.6 Oman
- 5.4.2 North Africa
- 5.4.2.1 Egypt
- 5.4.2.2 Morocco
- 5.4.2.3 Algeria
- 5.4.2.4 Tunisia
- 5.4.3 Levant
- 5.4.3.1 Jordan
- 5.4.3.2 Lebanon
- 5.4.1 GCC
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Fawry
- 6.4.2 PayTabs
- 6.4.3 Checkout.com
- 6.4.4 Tabby
- 6.4.5 Tamara
- 6.4.6 STC Pay
- 6.4.7 Paymob
- 6.4.8 MNT-Halan
- 6.4.9 Geidea
- 6.4.10 Network International
- 6.4.11 BenefitPay
- 6.4.12 Careem Pay
- 6.4.13 Lean Technologies
- 6.4.14 HyperPay
- 6.4.15 YAP
- 6.4.16 Telda
- 6.4.17 NymCard
- 6.4.18 Sarwa
- 6.4.19 OPay
7 Market Opportunities & Future Outlook
- 7.1 Cross-border GCC-North Africa remittance corridors via tokenized wallets
- 7.2 Green Islamic fintech products aligned with ESG & Sharia mandates

 亞太地區金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美金融科技:市佔率分析、產業趨勢與統計及成長預測(2026-2031)德國金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)新加坡金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)歐洲金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)越南金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)金融科技:市場佔有率分析、產業趨勢與統計、成長預測(2025-2030)印度金融科技:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 金融科技即服務 (FaaS) 市場 - 全球市場預測 2026-2032