


 |
市場調查報告書
商品編碼
2124478
拉丁美洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Latin America Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,拉丁美洲資料中心建設市場規模將從 2025 年的 55.9 億美元成長到 2026 年的 60.5 億美元,然後在 2031 年達到 89.6 億美元,2026 年至 2031 年的複合年成長率為 8.19%。
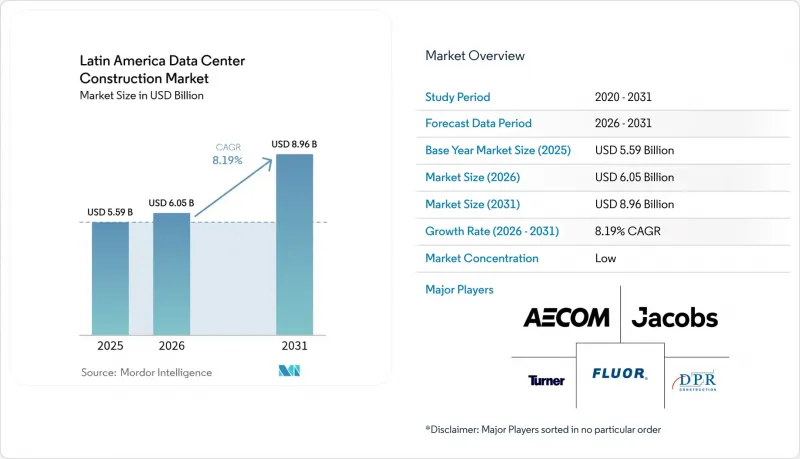
本報告按基礎設施(電力基礎設施、機械基礎設施等)、等級標準(一級、二級、三級等)、最終用戶(銀行、金融服務、保險、IT、電信等)、資料中心類型(託管、超大規模等)和地區(巴西、墨西哥等)分類。預測值以美元計。
拉丁美洲資料中心建設市場趨勢與洞察
加速雲端運算、人工智慧和巨量資料工作負載
人工智慧 (AI) 應用目前所需的功率密度是傳統運算的 3 到 5 倍,迫使營運商重新設計散熱架構和電氣拓撲結構。微軟在巴西投資 27 億美元,Scala 公司斥資 500 億美元打造“AI 城市”,這些都清晰地展現了這些新需求的規模。液冷技術的應用正在加速,本地生產的 Delta Cube 系統正在降低 ODATA 站點的能耗。區域政策制定者正將 AI 基礎設施定位為提升數位競爭力的支柱,推動簡化許可流程並提供有針對性的稅收優惠。承包商報告稱,高密度機電工程 (MEP) 項目的競標數量激增,母線槽、泵浦和板式熱交換器的供應商正在擴大其在該地區的生產基地。
美國一家大型雲端公司正在建造一個超大規模園區。
亞馬遜網路服務 (AWS)、微軟 Azure 和谷歌雲端計畫到 2030 年在拉丁美洲總合投資超過 100 億美元。將在聖保羅、克雷塔羅和波哥大建設的多吉瓦級園區需要冗餘的 400 千伏電源、先進的消防系統和預製配電室,以將試運行週期縮短至 12-18 個月。該地區領先的光纖供應商 V.tal 已累計10 億美元,用於在巴西建造超大規模的預製設施。這種「客製化建造」模式有利於擁有整合設計和施工專業知識的 EPC(工程、採購和施工)公司,隨著主要大都市地區的電力供應日益緊張,需求正向二線城市蔓延。
電網瓶頸和電費飆漲
在墨西哥,開發商面臨長達18個月的併網延誤,迫使他們購買柴油發電設備。這導致專案資本支出(CAPEX)增加高達25%,營運成本也隨之上升。在阿根廷,宏觀經濟波動加劇了價格風險,而聖保羅局部的電網擁塞迫使開發商將業務拓展至坎皮納斯和阿雷格里港。人工智慧工作負載使電力密度翻倍,給原本為商業辦公負載設計的電網帶來了巨大壓力。儘管營運商擴大簽署15年期可再生能源購電協議(PPA)以確保價格穩定,但中小企業缺乏簽訂此類協議所需的資金,從而減緩了中端市場對再生能源的接受度。
細分市場分析
預計到2025年,機械基礎設施將佔拉丁美洲資料中心建設市場規模的37.35%。這主要是由於巴西、秘魯和哥倫比亞氣候炎熱潮濕,需要配備強大的冷水循環系統、蒸發冷卻系統和客製化的封閉式系統。電力基礎設施中的配電盤、開關設備和UPS陣列對於滿足銀行和電信產業的運作要求仍然至關重要。在一般建築領域,投資主要集中在堅固的殼體結構上,包括抗震加固和抗颶風外牆,以保護關鍵任務機房。
IT基礎設施是成長最快的類別,複合年成長率 (CAGR) 達 8.16%,這主要得益於針對 AI 推理最佳化的伺服器、NVMe 儲存陣列和 400 Gbps 網路架構。超大規模客戶正在標準化高密度機架,這些機架需要直接到晶片 (DTC) 流體歧管,從而推動了對不銹鋼管道和冗餘冷卻泵的需求。諮詢、試運行和設施管理等服務透過確保合規性和 PUE 最佳化來增加價值。隨著拉丁美洲各證券交易所碳排放揭露標準的日益嚴格,拉丁美洲資料中心建設在能源效率諮詢領域的市場佔有率正在上升。
到2025年,Tier III級資料中心將佔拉丁美洲資料中心建置市場的61.10%,在99.982%的可用性和可控的資本支出(CAPEX)之間取得平衡。銀行、保險公司和公共雲端供應商選擇這一級別來承載核心工作負載,因為這些工作負載可以接受較短的維護窗口。同時,Tier II級資料中心通常用於內容傳遞網路和區域邊緣節點,以便在將節點部署在更靠近使用者的位置的同時降低成本。
由於超大規模資料中心業者和金融科技平台要求99.995%的服務水準保證,預計到2031年,Tier IV級資料中心建設將以8.55%的複合年成長率成長。多條獨立的配電線路、容錯冷卻系統和可並聯維護的發電機組會使資本預算增加高達60%,但客戶為了滿足與運作相關的收入要求,願意接受這部分額外成本。為了避免後維修費用(這些費用曾困擾許多新進業者),建造者在設計初期就與認證機構合作。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 利用雲端運算、人工智慧和巨量資料加速工作負載
- 美國大型雲端公司擴建超大規模園區
- 拉丁美洲主要區域城市對5G主導的邊緣資料中心的需求
- 關於主權雲端資料居住的法規
- 確保可再生能源購電協議(PPA)的簽訂
- 模組化和預製建築的普及
- 市場限制因素
- 電網瓶頸和電費飆漲
- 三級/四級認證機電工程工人短缺
- 水資源短缺阻礙了液冷技術的普及。
- 漫長的環境許可程序和當地居民的反對
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 拉丁美洲資料中心建置關鍵統計數據
- 拉丁美洲資料中心總裝置容量(兆瓦):2023-2024 年
- 2025-2030年拉丁美洲在建IT總負載(兆瓦)
- 拉丁美洲資料中心建置的平均資本投資與營運成本
- 拉丁美洲資料中心基礎建設領域資本投資最大的公司
第5章 市場規模與成長預測
- 透過基礎設施
- 透過電力基礎設施
- 配電解決方案
- 配電單元
- 切換裝置
- 其他電力基礎設施
- 備用電源解決方案
- UPS
- 發電機
- 配電解決方案
- 透過機械基礎設施
- 冷卻系統
- 液冷
- 空氣冷卻
- 機架和機櫃
- 其他機械基礎設施
- 冷卻系統
- 按類別分類的IT基礎設施
- 伺服器
- 貯存
- 其他IT基礎設施
- 一般建築
- 服務
- 設計與諮詢
- 一體化
- 支援與維護
- 透過電力基礎設施
- 基於層級的標準
- 一級和二級
- Tier III
- Tier IV
- 按最終用戶行業分類
- 銀行業、金融服務業及保險業
- 資訊科技/通訊
- 政府/國防
- 衛生保健
- 其他最終用戶
- 依資料中心類型
- 託管資料中心
- 超大規模/自建資料中心
- 其他(企業/邊緣/模組化)
- 按地區
- 巴西
- 智利
- 阿根廷
- 其他拉丁美洲國家
第6章 競爭情勢
- 市佔率分析
- 公司簡介
- AECOM
- Turner Construction Company
- DPR Construction
- Jacobs Solutions Inc.
- Fluor Corporation
- Skanska AB(Latin America)
- Ferrovial SA
- Grupo ACS(Dragados)
- ACCIONA Construccion
- Andrade Gutierrez Engenharia
- Camargo Correa Infra
- Novonor(Odebrecht Engenharia)
- Queiroz Galvao SA
- Techint EandC
- Sacyr Ingenieria e Infraestructuras
- Mota-Engil LATAM
- Constructora Norberto Odebrecht LatAm
- Grupo Carso Infraestructura
- COSAPI Ingenieria y Construccion
- Constructora Colpatria
- Grupo Marhnos
- Constructora Sudamericana
- Ghella SpA
- Besix Watpac
第7章 市場機會與未來展望
According to Mordor Intelligence, the Latin America data center construction market size is expected to grow from USD 5.59 billion in 2025 to USD 6.05 billion in 2026 and is forecast to reach USD 8.96 billion by 2031 at 8.19% CAGR over 2026-2031.
This report is Segmented by Infrastructure (Electrical Infrastructure, Mechanical Infrastructure, and More), Tier Standard (Tier I and II, Tier III, and More), End User (Banking Financial Services & Insurance, IT & Telecommunications, and More), Data Center Type (Colocation, Hyperscale, and More), and Geography (Brazil, Mexico, and More). Forecasts are in USD.
Latin America Data Center Construction Market Trends and Insights
Accelerating cloud, AI and big-data workloads
Artificial-intelligence applications now demand three to five times the power density of legacy computing, compelling operators to redesign thermal architectures and electrical topologies. Microsoft's USD 2.7 billion Brazil investment and Scala's USD 50 billion AI City illustrate the scale of new requirements. Liquid-cooling adoption accelerates, with locally manufactured Delta Cube systems reducing energy usage in ODATA sites. Regional policy makers regard AI infrastructure as a pillar of digital competitiveness, prompting expedited permits and targeted tax breaks. Contractors report surging bids for high-density MEP packages, and suppliers of busway, pumps, and plate-heat exchangers scale up regional production footprints.
Hyperscale campus build-outs by U.S. cloud majors
Amazon Web Services, Microsoft Azure, and Google Cloud collectively earmark more than USD 10 billion for Latin America by 2030. Multi-gigawatt campuses in Sao Paulo, Queretaro, and Bogota require redundant 400 kV utility feeds, advanced fire suppression, and prefabricated power rooms that cut commissioning cycles to 12-18 months. Regional fiber conglomerate V.tal alone budgets USD 1 billion to deliver hyperscale-ready shells in Brazil. The build-to-suit model favors EPC firms proficient in integrated design-build, and demand spills into secondary metros as power availability tightens in first-tier cities.
Grid-power bottlenecks and surging electricity tariffs
Mexico struggles with 18-month utility-interconnection queues, pushing developers to procure diesel generation that adds up to 25% to project CAPEX and inflates operating expenses. Argentina's macro-economic volatility amplifies tariff risk, while localized transmission congestion in Sao Paulo forces developers toward Campinas and Porto Alegre. AI workloads multiply power density, stressing grids originally designed for commercial office loads. Operators increasingly sign 15-year renewable PPAs to secure predictable pricing, but smaller enterprises lack the balance-sheet to pursue such deals, slowing adoption in mid-market segments.
Other drivers and restraints analyzed in the detailed report include:
- 5G-driven edge-DC demand in secondary LATAM metros
- Sovereign-cloud and data-residency regulations
- Scarcity of Tier-III/IV-certified MEP labor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mechanical infrastructure contributed 37.35% to the Latin America Data Center Construction market size in 2025, as hot-humid conditions across Brazil, Peru, and Colombia require robust chilled-water loops, evaporative cooling, and custom containment systems. Power distribution units, switchgear, and UPS arrays within electrical infrastructure stay essential for banking and telecom uptime mandates. General construction captures resilient shell-and-core outlays, including seismic bracing and hurricane-rated envelopes that safeguard mission-critical halls.
IT infrastructure is the fastest-growing category with an 8.16% CAGR, driven by servers optimized for AI inference, NVMe storage arrays, and 400 Gbps networking fabric. Hyperscale clients standardize on high-density racks requiring direct-to-chip liquid manifolds, which boosts demand for stainless-steel piping and redundant coolant pumps. Services such as consulting, commissioning, and facility management add value by ensuring regulation compliance and PUE optimization. The Latin America Data Center Construction market share within energy-efficiency consulting rises as carbon disclosure norms tighten in stock exchanges across the region.
Tier III sites held 61.10% of the Latin America Data Center Construction market share in 2025, balancing 99.982% availability against manageable capex. Banks, insurers, and public clouds select this level for core workloads that tolerate brief maintenance windows. Conversely, content-delivery networks and regional edge nodes often deploy Tier II to limit cost while placing nodes closer to users.
Tier IV construction will grow 8.55% CAGR through 2031 on the back of hyperscalers and fintech platforms seeking 99.995% service-level commitments. Multiple independent distribution paths, fault-tolerant chillers, and concurrently maintainable generators inflate capital budgets by up to 60%, yet clients accept the premium to satisfy uptime-linked revenue clauses. Builders partner with certification bodies early in design to avoid late-stage retrofit costs that have plagued first-time entrants.
Complete Report Scope:
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solutions
- Power Distribution Unit
- Switchgears
- Others Electrical Infrastructure
- Power Backup Solutions
- UPS
- Generators
- Power Distribution Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Liquid-based Cooling
- Air-based Cooling
- Racks and Cabinets
- Other Mechanical Infrastructure
- Cooling Systems
- By IT Infrastructure
- Servers
- Storage
- Other IT Infrastructure
- General Construction
- Services
- Design and Consulting
- Integration
- Support and Maintenance
- By Electrical Infrastructure
- By Tier Standard
- Tier I and II
- Tier III
- Tier IV
- By End-User Industry
- Banking, Financial Services and Insurance
- IT and Telecommunications
- Government and Defense
- Healthcare
- Other End Users
- By Data Center Type
- Colocation Data Centers
- Hyperscale / Self-built Data Centers
- Others (Enterprise / Edge / Modular)
- By Geography
- Brazil
- Chile
- Argentina
- Rest of Latin America
List of Companies Covered in this Report:
- AECOM
- Turner Construction Company
- DPR Construction
- Jacobs Solutions Inc.
- Fluor Corporation
- Skanska AB (Latin America)
- Ferrovial S.A.
- Grupo ACS (Dragados)
- ACCIONA Construccion
- Andrade Gutierrez Engenharia
- Camargo Correa Infra
- Novonor (Odebrecht Engenharia)
- Queiroz Galvao S.A.
- Techint EandC
- Sacyr Ingenieria e Infraestructuras
- Mota-Engil LATAM
- Constructora Norberto Odebrecht LatAm
- Grupo Carso Infraestructura
- COSAPI Ingenieria y Construccion
- Constructora Colpatria
- Grupo Marhnos
- Constructora Sudamericana
- Ghella S.p.A.
- Besix Watpac
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating cloud, AI and big-data workloads
- 4.2.2 Hyperscale campus build-outs by US cloud majors
- 4.2.3 5G-driven edge-DC demand in secondary LATAM metros
- 4.2.4 Sovereign-cloud and data-residency regulations
- 4.2.5 Power-purchase-agreement (PPA) availability for renewables
- 4.2.6 Modular and prefabricated construction adoption
- 4.3 Market Restraints
- 4.3.1 Grid-power bottlenecks and surging electricity tariffs
- 4.3.2 Scarcity of Tier-III/IV-certified MEP labour
- 4.3.3 Water-stress curbing liquid-cooling deployments
- 4.3.4 Lengthy environmental licensing and community opposition
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Key Latin America Data Center Construction Statistics
- 4.8.1 Data Centers Total Installed Capacity (MW) in the Latin America, 2023 and 2024
- 4.8.2 Total IT Load Under Construction in the Latin America, MW, 2025 - 2030
- 4.8.3 Average Capex and Opex for the Latin America Data Center Construction
- 4.8.4 Top Capex Spenders on Data Center Infrastructure in Latin America
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Infrastructure
- 5.1.1 By Electrical Infrastructure
- 5.1.1.1 Power Distribution Solutions
- 5.1.1.1.1 Power Distribution Unit
- 5.1.1.1.2 Switchgears
- 5.1.1.1.3 Others Electrical Infrastructure
- 5.1.1.2 Power Backup Solutions
- 5.1.1.2.1 UPS
- 5.1.1.2.2 Generators
- 5.1.1.1 Power Distribution Solutions
- 5.1.2 By Mechanical Infrastructure
- 5.1.2.1 Cooling Systems
- 5.1.2.1.1 Liquid-based Cooling
- 5.1.2.1.2 Air-based Cooling
- 5.1.2.2 Racks and Cabinets
- 5.1.2.3 Other Mechanical Infrastructure
- 5.1.2.1 Cooling Systems
- 5.1.3 By IT Infrastructure
- 5.1.3.1 Servers
- 5.1.3.2 Storage
- 5.1.3.3 Other IT Infrastructure
- 5.1.4 General Construction
- 5.1.5 Services
- 5.1.5.1 Design and Consulting
- 5.1.5.2 Integration
- 5.1.5.3 Support and Maintenance
- 5.1.1 By Electrical Infrastructure
- 5.2 By Tier Standard
- 5.2.1 Tier I and II
- 5.2.2 Tier III
- 5.2.3 Tier IV
- 5.3 By End-User Industry
- 5.3.1 Banking, Financial Services and Insurance
- 5.3.2 IT and Telecommunications
- 5.3.3 Government and Defense
- 5.3.4 Healthcare
- 5.3.5 Other End Users
- 5.4 By Data Center Type
- 5.4.1 Colocation Data Centers
- 5.4.2 Hyperscale / Self-built Data Centers
- 5.4.3 Others (Enterprise / Edge / Modular)
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Chile
- 5.5.3 Argentina
- 5.5.4 Rest of Latin America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Share Analysis
- 6.2 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.2.1 AECOM
- 6.2.2 Turner Construction Company
- 6.2.3 DPR Construction
- 6.2.4 Jacobs Solutions Inc.
- 6.2.5 Fluor Corporation
- 6.2.6 Skanska AB (Latin America)
- 6.2.7 Ferrovial S.A.
- 6.2.8 Grupo ACS (Dragados)
- 6.2.9 ACCIONA Construccion
- 6.2.10 Andrade Gutierrez Engenharia
- 6.2.11 Camargo Correa Infra
- 6.2.12 Novonor (Odebrecht Engenharia)
- 6.2.13 Queiroz Galvao S.A.
- 6.2.14 Techint EandC
- 6.2.15 Sacyr Ingenieria e Infraestructuras
- 6.2.16 Mota-Engil LATAM
- 6.2.17 Constructora Norberto Odebrecht LatAm
- 6.2.18 Grupo Carso Infraestructura
- 6.2.19 COSAPI Ingenieria y Construccion
- 6.2.20 Constructora Colpatria
- 6.2.21 Grupo Marhnos
- 6.2.22 Constructora Sudamericana
- 6.2.23 Ghella S.p.A.
- 6.2.24 Besix Watpac
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 中東資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032 年)亞太地區資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)南美洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)日本資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032)歐洲資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)法國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)泰國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)義大利資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)英國資料中心建置:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)