


 |
市場調查報告書
商品編碼
2123441
IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)IT Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,2026 年 IT 服務市值將達到 1.65 兆美元,預計在預測期(2026-2031 年)內將以 8.78% 的複合年成長率成長,到 2031 年將達到 2.51 兆美元。
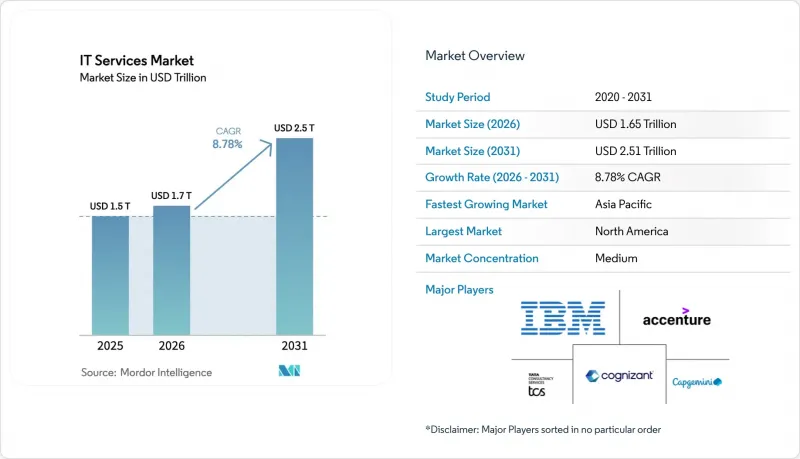
本報告按服務類型(例如,IT諮詢和實施)、最終用戶公司規模(例如,中小企業)、部署模式(例如,境內部署、近岸部署)、最終用戶行業(例如,銀行、金融服務和保險業、製造業)以及地區(北美、南美、歐洲、亞太、中東和非洲)進行細分。市場預測以美元計價。
全球IT服務市場趨勢與洞察
加速後疫情時代的數位轉型
超過 87% 的企業採用多重雲端,其中 51% 的企業正在投資雲端原生現代化項目,這些項目融合了應用程式重構、人工智慧服務和資料平台。在當今的全球 IT 服務市場,擁有容器編排管理、微服務和 DevOps 專業知識的供應商比那些提供簡單「遷移」服務的供應商更受青睞。 DXC Technology 的「Cloud Right」方法幫助 Ocean Network Express 實現了零停機遷移,展現了供應商如何從基礎設施管理員轉型為策略業務合作夥伴。收入正轉向諮詢和託管雲端營運服務,這些服務既需要先進的技術專長,也需要深厚的產業知識。這些合約通常圍繞共用的服務等級成果 (SLA) 構建,能夠提高供應商的客戶留存率和單位盈利。 Kubernetes、站點可靠性工程 (SRE) 和財務維 (FinOps) 的技能短缺進一步推高了服務費用,凸顯了雲端優先計畫對長期成長的最大正面影響。
混合雲端遷移的蓬勃發展
隨著企業追求工作負載可移植性和合規性,預計2022年至2027年間,全球在雲端ERP的支出將幾乎翻倍。到2025年,歐洲企業在IT服務上的支出將達到4,898億歐元(5,535億美元),其中45%將用於雲端舉措。雖然多重雲端策略有助於企業避免供應商鎖定,但也會導致管治複雜性增加,進而導致對諮詢和最佳化服務的需求不斷成長。有關資料主權的法規增加了對區域託管地點的需求,並推動了近岸和在岸外包業務的發展。提供認證雲端架構師和託管FinOps人才的供應商正在整個IT服務市場獲得高利潤合約。
商品化對服務價格的壓力
自動化和離岸部署的擴展正在降低通用服務台和基礎設施相關服務的進入門檻,從而壓縮傳統外包的利潤空間。客戶越來越要求按結果收費,這要求供應商證明其服務對業務的實際影響。小規模的競爭對手正在降低價格,加速現有公司之間的整合,這些公司能夠交叉銷售高階諮詢和保全服務。由此產生的產業重組預計將在未來兩年內重塑IT服務市場的競爭格局。
細分市場分析
託管安全服務正以12.18%的複合年成長率成長,是整個IT服務市場中成長最快的。企業意識到,在威脅偵測和事件回應方面,專業服務提供者的表現優於內部團隊,因此簽訂了包含持續合規性監控的長期外包合約。 IT外包佔了28.04%的最大收入佔有率,這主要得益於企業對成本最佳化的現有需求。然而,同質化業務領域的利潤率壓縮迫使供應商將外包和諮詢服務打包出售以維持價格。雲端和平台服務正受益於混合雲端的普及。專案通常會結合ERP現代化和資料整合層,從而促進交叉銷售。
業務流程外包 (BPO) 的需求趨勢也十分有利。機器人流程自動化 (RPA) 尤其能夠提升財務、人力資源和特定產業後勤部門營運的效率。由於企業需要指導如何整合人工智慧、邊緣運算和垂直雲,IT 諮詢收入也隨之成長,這主要是因為 IT 系統日益複雜。提供參考架構、遷移加速工具包和領域特定解決方案的供應商正在擴大其在整體 IT 服務市場的佔有率。
預計到2031年,中小企業(SME)的複合年成長率將達到10.92%,反映出企業資源規劃(ERP)、客戶關係管理(CRM)和網路安全等雲端解決方案的廣泛應用。付費使用制使中小企業能夠實施以前只有大型企業才能使用的功能,並將實施時間從數月縮短至數週。醫療保健和金融服務業的合規負擔促使中小企業依賴外部專家而非建立內部控制系統,從而擴大了託管服務合作夥伴的潛在收入。
大型企業仍佔69.42%的營收佔有率,這主要得益於其龐大的舊有系統組合,這些系統需要製定長期的轉型藍圖。將內部專家與有針對性的外部專業知識相結合的混合模式正逐漸成為主流,從而為專業供應商帶來高價值合約。企業負責人擴大在招標書(RFP)中納入永續發展記錄和碳提案報告準備情況,這為在整個IT服務市場中追蹤範圍3排放的供應商創造了差異化機會。
區域分析
到2025年,北美將佔全球收入的37.05%,這主要得益於高達2.7兆美元的企業技術支出以及人工智慧和雲端平台領域的早期採用趨勢。一項要求設立人工智慧管治委員會的聯邦指令,使得策略諮詢和實施服務的需求制度化。加拿大正在大力推動數位政府專案和自然資源自動化,而墨西哥的近岸提案則吸引了尋求文化親和性和智慧財產權保護的美國公司。
預計到2031年,亞太地區的年複合成長率(CAGR)將達到11.12%,位居全球最高。中國正在擴大智慧城市試點項目,並向綠色製造轉型;印度正發揮其作為傳統物流樞紐的優勢,以擴大國內需求。東南亞國協也努力彌合基礎設施差距,以支持跨境電子商務和金融科技的發展。日本和韓國正集中投資先進製造業和電信領域,並重振5G和邊緣運算等細分諮詢業務。儘管澳洲和紐西蘭的IT支出已相當成熟,但它們仍然將網路安全和雲端合規性作為銀行和政府部門的優先事項。
到2025年,歐洲將有4,898億歐元(5,535億美元)的資金投入IT服務,其中45%將用於雲端運算專案。 GDPR、DORA和NIS2等法律規範正在推動安全和合規方面的支出,並確保合格供應商擁有穩定的專案儲備。德國主導製造業的數位轉型,英國推動金融服務業的轉型,法國、義大利和西班牙正在擴大雲端ERP的應用。東歐正在發展成為近岸開發中心和現代化服務需求源,從而深化整個IT服務市場的生態系統。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速後疫情時代的數位轉型
- 混合雲端遷移熱潮
- 網路威脅情勢日益惡化
- 企業在人工智慧和分析方面的支出正在激增。
- 產業特定雲端平台實施
- 以永續性為優先的綠色IT審計
- 市場限制因素
- 服務價格面臨商品化壓力
- 全球勞動力短缺和離職率上升
- 圍繞數據主權的地緣政治障礙
- 範圍 3 碳排放報告的合規成本
- 產業價值鏈分析
- 宏觀經濟因素的影響
- 重要法規結構的評估
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- IT諮詢與實施
- IT外包(ITO)
- 業務流程外包(BPO)
- 託管安全服務
- 雲端和平台服務
- 按最終用戶公司規模分類
- 中小企業
- 大公司
- 按部署模式
- 陸上交付
- 近岸交付
- 離岸交付
- 按最終用戶行業分類
- BFSI
- 製造業
- 政府/公共部門
- 醫療保健和生命科學
- 零售和消費品
- 通訊與媒體
- 物流/運輸
- 能源公用事業
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 澳洲和紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accenture plc
- International Business Machines Corporation(IBM)
- Tata Consultancy Services Limited(TCS)
- Infosys Limited
- Cognizant Technology Solutions Corporation
- Capgemini SE
- Wipro Limited
- HCL Technologies Limited
- DXC Technology Company
- Atos SE
- Fujitsu Limited
- NTT DATA Corporation
- CGI Inc.
- L&T Technology Services Limited
- Tech Mahindra Limited
- EPAM Systems Inc.
- Endava plc
- Globant SA
- Mindtree Limited
- Sopra Steria Group SA
- Rackspace Technology Inc.
- Virtusa Corporation
- Persistent Systems Limited
- UST Global Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the IT services market size is estimated at USD 1.65 trillion in 2026, and is expected to reach USD 2.51 trillion by 2031, at a CAGR of 8.78% during the forecast period (2026-2031).
This report is Segmented by Service Type (IT Consulting and Implementation, and More), End-User Enterprise Size (Small and Medium Enterprises, and More), Deployment Model (Onshore, Nearshore, and More), End-User Vertical (BFSI, Manufacturing, and More), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global IT Services Market Trends and Insights
Digital-transformation acceleration post-COVID-19
Multi-cloud adoption has crossed 87% of enterprises, while 51% are funding cloud-native modernization tracks that bundle application refactoring, AI services and data platforms. The Global IT services market now rewards providers that master container orchestration, micro-services and DevOps over simple lift-and-shift migration. DXC Technology's "Cloud Right" approach enabled Ocean Network Express to achieve zero-downtime migration, showcasing how vendors move from infrastructure caretakers to strategic business partners. Revenue pools are shifting toward advisory and managed cloud operations layers that demand both deep technical credentials and sector insight. These engagements, typically structured around shared service-level outcomes, lift provider stickiness and unit economics. Skills scarcity in Kubernetes, site reliability engineering and FinOps is further buoying service rates, underscoring why cloud-first programmes add the highest positive delta to long-run growth.
Hybrid-cloud migration boom
Global cloud-ERP outlays are on track to nearly double between 2022 and 2027 as enterprises pursue workload portability and regulatory compliance. European firms directed EUR 489.8 billion (USD 553.5 billion) to IT services in 2025, with 45% tagged for cloud initiatives. Multi-cloud strategies help organizations avert vendor lock-in, yet they impose governance complexity that drives demand for advisory and optimization services. Data sovereignty mandates heighten the need for region-specific hosting footprints, bolstering nearshore and onshore engagements. Providers offering certified cloud architects and managed FinOps talent are capturing high-margin contracts across the IT services market.
Service-price commoditization pressure
Automation and offshore scale have erased entry barriers for common help-desk and infrastructure tasks, compressing margins in traditional outsourcing. Clients increasingly demand outcome-based billing, compelling vendors to prove tangible business impact. Smaller rivals undercut pricing, which accelerates consolidation among incumbents able to cross-sell premium consulting and security offerings. The resulting shake-out is likely to realign the competitive order within the IT services market over the next two years.
Other drivers and restraints analyzed in the detailed report include:
- Escalating cyber-threat landscape
- Enterprise AI and analytics spend surge
- Global talent shortage and attrition
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Managed Security Services is growing at a 12.18% CAGR, the steepest rate across the IT services market. Enterprises accept that specialized providers outperform internal teams in threat detection and incident response, prompting long-term outsourcing contracts that include continuous compliance monitoring. IT Outsourcing retains the largest 28.04% revenue position due to entrenched cost-optimization mandates. However, margin compression in commoditized workstreams is pushing vendors to package outsourcing with consulting to protect pricing. Cloud and Platform Services benefit from surging hybrid-cloud adoption; projects frequently bundle ERP modernization with data-integration layers, supporting cross-selling momentum.
Demand dynamics also favor Business Process Outsourcing, especially in finance, HR, and industry-specific back-office workflows where robotic process automation amplifies efficiency gains. IT Consulting revenues rise on complexity: organizations need guidance to harmonize AI, edge computing, and vertical clouds. Vendors that deliver reference architectures, accelerated migration toolkits, and domain-centric solutions increase wallet share across the IT services market.
Small and Medium Enterprises register an 10.92% CAGR through 2031, reflecting democratized access to cloud-delivered ERP, CRM, and cybersecurity bundles. Consumption-based pricing allows SMEs to deploy capabilities historically reserved for large corporations, compressing deployment timelines from months to weeks. Compliance burdens in healthcare and financial services incentivize SMEs to engage external specialists rather than build in-house controls, expanding addressable revenue for managed-service partners.
Large Enterprises still command 69.42% revenue, underpinned by sprawling legacy estates that demand long-duration transformation roadmaps. Hybrid models blending internal centers of excellence with targeted external expertise prevail, securing high-value contracts for niche providers. Enterprise buyers increasingly list sustainability credentials and carbon-reporting readiness in RFPs, offering differentiation avenues for providers that track Scope-3 emissions across the IT services market.
Complete Report Scope:
- By Service Type
- IT Consulting and Implementation
- IT Outsourcing (ITO)
- Business Process Outsourcing (BPO)
- Managed Security Services
- Cloud and Platform Services
- By End-User Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Deployment Model
- Onshore Delivery
- Nearshore Delivery
- Offshore Delivery
- By End-user Vertical
- BFSI
- Manufacturing
- Government and Public Sector
- Healthcare and Life-Sciences
- Retail and Consumer Goods
- Telecom and Media
- Logistics and Transport
- Energy and Utilities
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America represents 37.05% of 2025 revenue, steered by USD 2.7 trillion in enterprise tech spending and early-adopter behavior toward AI and cloud platforms. Federal mandates requiring AI governance boards have institutionalized demand for strategic advisory and implementation services. Canada advances digital-government programs and natural-resource automation, whereas Mexico's nearshore proposition attracts U.S. firms seeking cultural affinity and IP protection.
Asia-Pacific records the highest 11.12% CAGR through 2031. China scales smart-city pilots and green-manufacturing upgrades, India leverages its delivery-hub heritage while expanding domestic demand, and ASEAN economies close infrastructure gaps to support cross-border e-commerce and fintech growth. Japan and South Korea funnel investments into advanced manufacturing and telecom, spurring niche consulting around 5G and edge computing. Australia and New Zealand, despite mature IT spend, continue prioritizing cybersecurity and cloud compliance in banking and government.
Europe allocates EUR 489.8 billion (USD 553.5 billion) to IT services in 2025, 45% of which funds cloud programs. Regulatory frameworks-GDPR, DORA, and NIS2-propel security and compliance spend, ensuring consistent engagement pipelines for qualified providers. Germany spearheads manufacturing digitization, the United Kingdom leads in financial services transformation, and France, Italy, and Spain scale cloud-ERP rollouts. Eastern Europe develops as both a nearshore delivery basin and a consumer of modernization services, strengthening ecosystem depth across the IT services market.
- Accenture plc
- International Business Machines Corporation (IBM)
- Tata Consultancy Services Limited (TCS)
- Infosys Limited
- Cognizant Technology Solutions Corporation
- Capgemini SE
- Wipro Limited
- HCL Technologies Limited
- DXC Technology Company
- Atos SE
- Fujitsu Limited
- NTT DATA Corporation
- CGI Inc.
- L&T Technology Services Limited
- Tech Mahindra Limited
- EPAM Systems Inc.
- Endava plc
- Globant S.A.
- Mindtree Limited
- Sopra Steria Group SA
- Rackspace Technology Inc.
- Virtusa Corporation
- Persistent Systems Limited
- UST Global Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Digital-transformation acceleration post-COVID-19
- 4.2.2 Hybrid-cloud migration boom
- 4.2.3 Escalating cyber-threat landscape
- 4.2.4 Enterprise AI and analytics spend surge
- 4.2.5 Vertical-specific cloud platforms adoption
- 4.2.6 Sustainability-driven Green-IT audits
- 4.3 Market Restraints
- 4.3.1 Service-price commoditization pressure
- 4.3.2 Global talent shortage and attrition
- 4.3.3 Data-sovereignty geopolitical barriers
- 4.3.4 Scope-3 carbon-reporting compliance costs
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Evaluation of Critical Regulatory Framework
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 IT Consulting and Implementation
- 5.1.2 IT Outsourcing (ITO)
- 5.1.3 Business Process Outsourcing (BPO)
- 5.1.4 Managed Security Services
- 5.1.5 Cloud and Platform Services
- 5.2 By End-User Enterprise Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 Onshore Delivery
- 5.3.2 Nearshore Delivery
- 5.3.3 Offshore Delivery
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 Manufacturing
- 5.4.3 Government and Public Sector
- 5.4.4 Healthcare and Life-Sciences
- 5.4.5 Retail and Consumer Goods
- 5.4.6 Telecom and Media
- 5.4.7 Logistics and Transport
- 5.4.8 Energy and Utilities
- 5.4.9 Other End-user Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Australia and New Zealand
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 International Business Machines Corporation (IBM)
- 6.4.3 Tata Consultancy Services Limited (TCS)
- 6.4.4 Infosys Limited
- 6.4.5 Cognizant Technology Solutions Corporation
- 6.4.6 Capgemini SE
- 6.4.7 Wipro Limited
- 6.4.8 HCL Technologies Limited
- 6.4.9 DXC Technology Company
- 6.4.10 Atos SE
- 6.4.11 Fujitsu Limited
- 6.4.12 NTT DATA Corporation
- 6.4.13 CGI Inc.
- 6.4.14 L&T Technology Services Limited
- 6.4.15 Tech Mahindra Limited
- 6.4.16 EPAM Systems Inc.
- 6.4.17 Endava plc
- 6.4.18 Globant S.A.
- 6.4.19 Mindtree Limited
- 6.4.20 Sopra Steria Group SA
- 6.4.21 Rackspace Technology Inc.
- 6.4.22 Virtusa Corporation
- 6.4.23 Persistent Systems Limited
- 6.4.24 UST Global Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 印尼IT服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)北美IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)歐洲IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 2026-2030年全球IT服務市場美國IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)英國IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)零售商個人化服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 BlockConnect 服務市場預測至 2034 年—按服務類型、部署模式、技術、應用、最終用戶和地區分類的全球分析個人化服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)亞太地區IT服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)