


 |
市場調查報告書
商品編碼
2117226
北美IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)North America IT Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
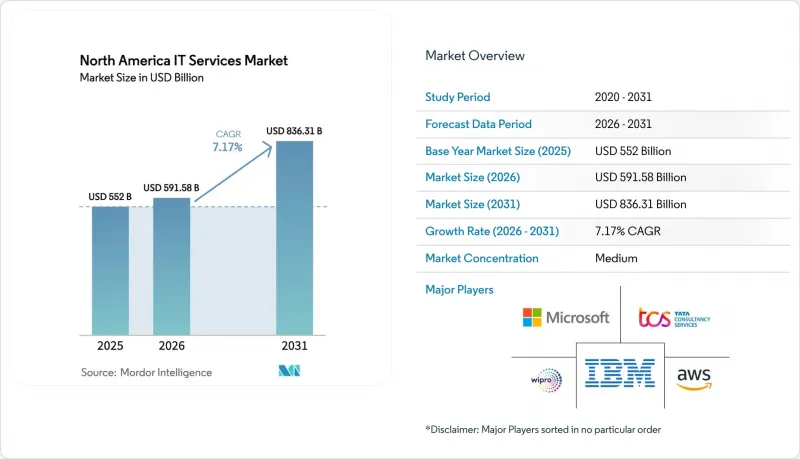
據 Mordor Intelligence 稱,2025 年北美 IT 服務市值為 5520 億美元,預計到 2031 年將達到 8363.1 億美元,而 2026 年為 5915.8 億美元,預測期(2026-2031 年)的複合年成長率為 7.17%。
本報告按服務類型(IT諮詢與實施、託管服務等)、部署模式(本地部署和雲端部署)、組織規模(大型企業和中小企業)、最終用戶行業(銀行、金融服務和保險業、政府和公共部門等)以及國家/地區進行細分。市場預測以美元計價。
北美IT服務市場的趨勢與洞察
加速公司範圍內的數位轉型
72%的數位領導者預計2025年預算將會增加,這顯示轉型已演變為經營模式的徹底重組。北美公司每年在IT方面的支出平均為3,300萬美元,反映出IT採用率的提高和人事費用的飆升。合約中擴大包含人工智慧驅動的決策支援、自主營運和即時客戶參與平台,為供應商提供了多年的收入前景。
快速遷移到雲端和混合多重雲端
混合架構在超大規模資料中心業者之間實現了效能、合規性和成本的平衡。預計到 2027 年,75% 的 IT 工作負載將在雲端運作。企業正在採用多重雲端以避免供應商鎖定,從而推動了對編配和管治服務的需求。儘管超大規模資料中心業者佔據了 67% 的市場佔有率,但用戶正在分散部署,以降低集中化風險。
資料主權和合規性的複雜性日益增加。
隱私法規的分散迫使企業運作重疊的框架,增加了成本和架構複雜性。歐盟的人工智慧透明度增強規則以及加州、奧勒岡州和德克薩斯州的州法律等區域性法規要求進行本地化處理和即時審計。在多重雲端環境中,整合資料本地化管理功能的需求增加了編配開銷。專業的管治平台和法律諮詢服務擴大被納入轉型專案契約,影響著北美IT服務市場的專案進度安排和定價。
細分市場分析
預計到2025年,IT諮詢和實施服務將佔北美IT服務市場佔有率的45.02%,凸顯了策略指導和變革管理日益受到重視。目前的項目包括人工智慧驅動的業務流程重組、合規性以及資料管治藍圖設計。預計年複合成長率為8.22%的託管服務正在滿足混合環境下對可預測、以結果為導向的營運的需求。這一成長主要由人工智慧驅動的服務台、AIOps平台和主動事件預防所推動。 IT外包領域仍保持強勁勢頭,提供成本最佳化和稀缺技能獲取途徑,而業務流程外包(BPO)正在朝向智慧自動化方向發展。人工智慧即服務和量子運算諮詢等新興領域預示著未來的成長潛力,但目前即使加起來,它們也僅佔北美整體IT服務市場的一小部分。
供應商正透過併購重組其業務組合,每年投資約200億美元以增強其自動化、網路安全和垂直產業能力。成功的整合商正儘早實現交付框架的標準化,加速交叉銷售,並整合統一的服務目錄。同時,那些在併購後整合過程中步履維艱的公司,正被敏捷的競爭對手蠶食市場佔有率。
到2025年,本地部署仍將佔總收入的67.12%,但其角色正在轉變,成為高度分散式架構中的核心節點。預計到2031年,雲端領域的規模將達到本地部署的水平,複合年成長率(CAGR)為8.71%,重點在於工作負載可攜性、基於資料位置的合規性以及用於人工智慧訓練的彈性擴展。在北美IT服務市場,雲端服務市場在嚴格監管的產業中成長最為迅速,這些產業的自主雲端解決方案能夠在不犧牲超大規模優勢的前提下,提供合規性保障。
市場領先的供應商正透過端到端可觀測性、邊緣到核心的數據整合以及跨平台策略執行來凸顯自身優勢。尤其值得一提的是,市場對將傳統舊有應用程式遷移到 Kubernetes、實施服務網格架構以及建立基於價值標準最佳化支出的 FinOps 實踐有著強勁的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速公司範圍內的數位轉型
- 快速遷移到雲端和混合多重雲端
- 網路安全的重要性日益凸顯,零信任理念也日益普及。
- 近岸人才中心正在緩解美國的技能缺口。
- 績效定價正在刺激中型市場的需求。
- 託管式 GenAI 加速器即服務
- 市場限制因素
- 資料主權和合規性的複雜性
- 勞動力嚴重短缺和工資上漲
- 碳排放資訊揭露法規阻礙了資料中心外包。
- 為因應利率上升,合約風險規避行為正在發生。
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 評估宏觀經濟趨勢對市場的影響
第5章 市場規模與成長預測
- 按服務類型
- IT諮詢與實施
- 託管服務
- IT外包(ITO)
- 業務流程外包(BPO)
- 其他服務類型
- 按部署模式
- 現場
- 雲
- 按組織規模
- 大公司
- 中小企業
- 按最終用戶行業分類
- BFSI
- 政府/公共部門
- 製造業
- 醫療保健和生命科學
- 零售和消費品
- 物流/運輸
- 其他終端用戶產業
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accenture plc
- IBM Corporation
- Microsoft Corporation
- Tata Consultancy Services(TCS)
- Infosys Limited
- Wipro Limited
- HCLTech
- Capgemini SE
- Cognizant Technology Solutions
- Deloitte Consulting
- Amazon Web Services(AWS)Professional Services
- DXC Technology
- CGI Inc.
- NTT DATA Services
- Kyndryl Holdings
- EPAM Systems
- Tech Mahindra
- Rackspace Technology
- Softchoice Corporation
- Insight Enterprises
- Perficient Inc.
- ThoughtWorks
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America IT services market size was valued at USD 552 billion in 2025 and estimated to grow from USD 591.58 billion in 2026 to reach USD 836.31 billion by 2031, at a CAGR of 7.17% during the forecast period (2026-2031).
This report is Segmented by Service Type (IT Consulting and Implementation, Managed Services, and More), Deployment Model (On-Premise and Cloud), Organization Size (Large Enterprises and Small and Medium Enterprises (SMEs)), End-User Industry (BFSI, Government and Public Sector, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America IT Services Market Trends and Insights
Acceleration of Enterprise-Wide Digital Transformation
Seventy-two percent of digital leaders expect bigger 2025 budgets, signaling that transformation has evolved into full business-model reinvention. North American firms spend an average of USD 33 million annually on IT, reflecting higher adoption rates and labor costs. Contracts increasingly embed AI-driven decision support, autonomous operations, and real-time customer-engagement platforms, granting providers multi-year revenue visibility.
Rapid Cloud and Hybrid-Multi-Cloud Migration
Hybrid architectures balance performance, compliance, and cost across hyperscalers; 75% of IT workloads are forecast to run in the cloud by 2027. Enterprises adopt multi-cloud to avoid vendor lock-in, prompting demand for orchestration and governance services. The top three hyperscalers hold 67% market share, yet users diversify to lower concentration risk.
Data-Sovereignty and Compliance Complexity
Fragmented privacy rules are forcing enterprises to operate overlapping frameworks that raise cost and architectural complexity. Region-specific mandates such as enhanced AI transparency rules in the EU and state-level statutes in California, Oregon, and Texas demand localized processing and real-time auditability. Multi-cloud environments must integrate data-localization controls, adding orchestration overhead. Specialized governance platforms and legal advisory services are increasingly bundled into transformation deals, influencing project timelines and pricing in the North America IT Services market.
Other drivers and restraints analyzed in the detailed report include:
- Escalating Cyber-Security and Zero-Trust Adoption
- Near-Shore Talent Hubs Ease US Skills Gap
- Acute Talent Shortage and Wage Inflation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IT consulting and implementation held 45.02% of North America IT Services market share in 2025, underlining the premium placed on strategic guidance and change management. Engagements now encompass AI-infused business-process redesign, regulatory alignment, and data-governance blueprints. Managed services, forecasting an 8.22% CAGR, capture demand for predictable, outcome-linked operations across hybrid estates. Growth is fueled by AI-enabled service desks, AIOps platforms, and proactive incident prevention. The IT outsourcing segment remains resilient, offering cost optimization and access to scarce skills, while BPO is evolving toward intelligent automation. Emergent categories such as AI-as-a-service and quantum advisory signal future white-space, though they collectively account for a modest slice of the current North America IT Services market.
Providers are reshaping portfolios via M&A, deploying roughly USD 20 billion annually to bolt on automation, cybersecurity, and vertical-domain capabilities. Successful integrators standardize delivery frameworks early, accelerate cross-selling, and embed unified service catalogs. Those who stumble on post-merger integration leave value on the table for nimble competitors.
On-premise installations still represent 67.12% of 2025 revenue, but their role has shifted to anchor nodes within highly distributed fabrics. The cloud cohort, slated for parity by 2031 on a 8.71% CAGR, centers on workload portability, data-resident compliance, and elastic scaling for AI training. The North America IT Services market size for cloud services is expanding fastest in regulated verticals, where sovereign-cloud variants provide compliance assurance without sacrificing hyperscale benefits.
Market-leading providers differentiate through end-to-end observability, edge-to-core data integration, and cross-platform policy enforcement. Demand is especially strong for re-platforming legacy applications onto Kubernetes, implementing service mesh architectures, and instituting FinOps practices that optimize spend against value benchmarks.
Complete Report Scope:
- By Service Type
- IT Consulting and Implementation
- Managed Services
- IT Outsourcing (ITO)
- Business Process Outsourcing (BPO)
- Other Service Types
- By Deployment Model
- On-premise
- Cloud
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user Industry
- BFSI
- Government and Public Sector
- Manufacturing
- Healthcare and Life Sciences
- Retail and Consumer Goods
- Logistics and Transportation
- Other End-user Industries
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Accenture plc
- IBM Corporation
- Microsoft Corporation
- Tata Consultancy Services (TCS)
- Infosys Limited
- Wipro Limited
- HCLTech
- Capgemini SE
- Cognizant Technology Solutions
- Deloitte Consulting
- Amazon Web Services (AWS) Professional Services
- DXC Technology
- CGI Inc.
- NTT DATA Services
- Kyndryl Holdings
- EPAM Systems
- Tech Mahindra
- Rackspace Technology
- Softchoice Corporation
- Insight Enterprises
- Perficient Inc.
- ThoughtWorks
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Acceleration of enterprise-wide digital transformation
- 4.2.2 Rapid cloud and hybrid-multi-cloud migration
- 4.2.3 Escalating cyber-security and zero-trust adoption
- 4.2.4 Near-shore talent hubs ease U.S. skills gap
- 4.2.5 Outcome-based pricing unlocking mid-market demand
- 4.2.6 Managed GenAI accelerators as a service
- 4.3 Market Restraints
- 4.3.1 Data-sovereignty and compliance complexity
- 4.3.2 Acute talent shortage and wage inflation
- 4.3.3 Carbon-disclosure rules hinder data-center outsourcing
- 4.3.4 Higher interest-rate-driven contract risk aversion
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of the Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 IT Consulting and Implementation
- 5.1.2 Managed Services
- 5.1.3 IT Outsourcing (ITO)
- 5.1.4 Business Process Outsourcing (BPO)
- 5.1.5 Other Service Types
- 5.2 By Deployment Model
- 5.2.1 On-premise
- 5.2.2 Cloud
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Government and Public Sector
- 5.4.3 Manufacturing
- 5.4.4 Healthcare and Life Sciences
- 5.4.5 Retail and Consumer Goods
- 5.4.6 Logistics and Transportation
- 5.4.7 Other End-user Industries
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 IBM Corporation
- 6.4.3 Microsoft Corporation
- 6.4.4 Tata Consultancy Services (TCS)
- 6.4.5 Infosys Limited
- 6.4.6 Wipro Limited
- 6.4.7 HCLTech
- 6.4.8 Capgemini SE
- 6.4.9 Cognizant Technology Solutions
- 6.4.10 Deloitte Consulting
- 6.4.11 Amazon Web Services (AWS) Professional Services
- 6.4.12 DXC Technology
- 6.4.13 CGI Inc.
- 6.4.14 NTT DATA Services
- 6.4.15 Kyndryl Holdings
- 6.4.16 EPAM Systems
- 6.4.17 Tech Mahindra
- 6.4.18 Rackspace Technology
- 6.4.19 Softchoice Corporation
- 6.4.20 Insight Enterprises
- 6.4.21 Perficient Inc.
- 6.4.22 ThoughtWorks
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 印尼IT服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)歐洲IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 2026-2030年全球IT服務市場美國IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)英國IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)零售商個人化服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)IT服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 BlockConnect 服務市場預測至 2034 年—按服務類型、部署模式、技術、應用、最終用戶和地區分類的全球分析個人化服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)亞太地區IT服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)