


 |
市場調查報告書
商品編碼
2122402
中東和非洲電動車市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Middle East And Africa Electric Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
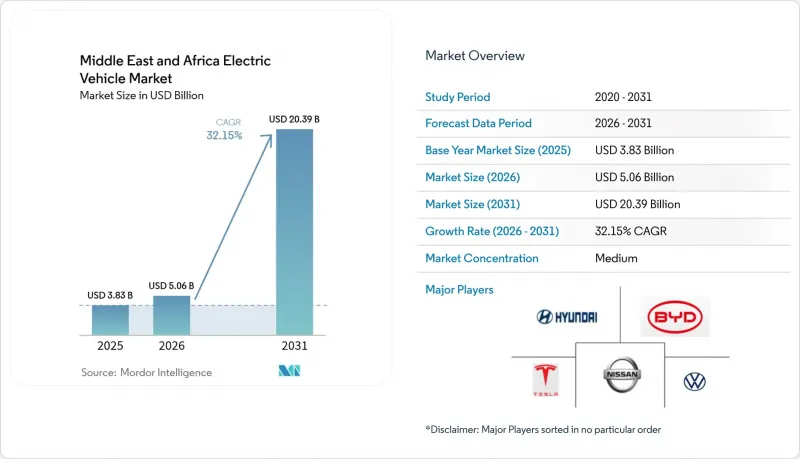
據 Mordor Intelligence 稱,2025 年中東和非洲電動車 (EV) 市場價值為 38.3 億美元,預計到 2031 年將從 2026 年的 50.6 億美元成長至 203.9 億美元,預測期(2026-2031 年)的複合成長率為 32.15%。
本報告按動力系統(電池式電動車、插電式混合動力汽車、燃料電池汽車)、車輛類型(乘用車、輕型商用車等)、電池化學成分(鋰離子電池、鎳氫電池、其他)、充電等級(7kW以下交流充電等)和國家進行細分。市場預測以美元計價。
中東和非洲電動車市場趨勢與洞察
政府強制推行脫碳政策,並設定目標禁止內燃機(ICE)。
海灣合作理事會(GCC)成員國正將電動車配額納入國家發展議程,設定需求下限,以此作為汽車製造商投資決策的依據。沙烏地阿拉伯的「2030願景」要求到2030年,利雅德30%的車輛必須為電動車;而阿拉伯聯合大公國的聯邦戰略則力爭2050年實現50%的車輛為電動車。這些指南正推動公共部門採購轉向零排放車輛,加速私部門車輛現代化,並促進海灣標準化組織(GSO)規則下的認證標準化,從而促進跨境貿易。摩洛哥已強制要求到2026年安裝2500個充電站,顯示強而有力的政策正在加速基礎設施的擴張。這些具有法律約束力的目標與《巴黎協定》第二十八屆聯合國氣候變遷大會(COP28)的承諾緊密相關,並為投資者提供了長期前景,有助於抵銷初期需求的波動。
公共直流快速充電走廊的快速發展
城際高速充電走廊的建設將使電動車從城市內部的交通工具轉變為覆蓋全部區域的交通工具。 EVIQ 在利雅德卡西姆高速公路上安裝的旗艦級 150 千瓦充電站,展現了其在高速公路上的實用性,並預示著該充電網路最終將覆蓋沙烏地阿拉伯王國最繁忙的 10 條主幹道。同時,阿拉伯聯合大公國計劃在 2030 年之前在阿布達比安裝 7 萬個公共充電樁,杜拜的目標是到 2025 年安裝 1000 個,從而有效消除酋長國境內的續航里程擔憂。摩洛哥的計畫將卡薩布蘭卡、拉巴特和丹吉爾連接起來,建造可再生能源直流充電樁,使充電時間縮短至 30 分鐘以內。在奈及利亞,西非最大的充電中心將於 2025 年開放,相關基礎設施也將擴展到新興市場。沿線充電站密度的增加將顯著提高商用車輛的運作,為傑貝阿里等港口貨運公司的電氣化鋪平道路。
車輛初始購買價格高昂,消費者融資受到限制。
儘管電池價格下降,但高昂的購車成本仍然阻礙著低收入群體對電動車的大規模普及。在埃及,分期付款計劃有限,且外匯以硬通貨支付(硬通貨易受匯率波動影響),導致電動車的市場佔有率僅為0.1%。習慣為二手進口車提供證券化服務的二手金融機構,在電動車貸款方面缺乏殘值基準,導致利率利差較大。在撒哈拉以南非洲地區,小額信貸機制主要針對兩輪計程車而非四輪汽車,進一步阻礙了汽車製造商實現規模經濟。
細分市場分析
預計到2025年,電池式電動車(BEV)將佔據電動車市場78.64%的佔有率,凸顯了該地區對純電動驅動系統的偏好,並避免了插電式混合動力汽車複雜的燃油稅問題。純電動車的吸引力在於其易於維護,以及在購物中心、機場和工業園區等地均可便捷地使用目的地充電樁。該細分市場強勁的利潤率促使特斯拉、比亞迪和吉利等公司推出了繞過傳統經銷商的直銷平台。
車隊營運商正採用純電動車(BEV)在基地進行夜間充電,從而減少對白天營運的干擾。隨著沙烏地阿拉伯在其工業走廊周邊擴建綠色氫氣加註站,預計到2031年,燃料電池電動車(FCEV)的複合年成長率將達到35.90%,凸顯其在長程運輸領域的潛力。同時,插電式混合動力汽車仍處於過渡階段,在電網不穩定的地區提供可靠的續航里程。因此,動力系統類型的構成比反映了基礎設施的成熟度:純電動車在沿岸地區的都市區地區佔據主導地位,而燃料電池汽車則在沙漠地區的貨運路線上日益普及。
2025年乘用車銷量佔比達64.05%,但預計到2031年,中型和重型商用車的複合年成長率將達到35.05%,這將擴大企業採購通路中電動車的市場規模。油田服務卡車和末端配送貨車由於每日行駛里程長,將更加受益於燃油成本的降低和碳排放審計的優勢。在吉達自由貿易區,物流公司在競標港口當局的排放氣體法規競標,正指定使用電動車車型。開羅和開普敦的公車電氣化試點計畫表明,公共交通的需求正在成長,而共享出行營運商正在引入小型掀背車電動車,以滿足城市空氣品質法規的要求。汽車製造商正透過調整車輛的負載容量、改進車內空調系統以及增強懸吊系統以適應非鋪裝路面來應對這一變化。隨著商用車銷量的成長,供應鏈正變得更加本地化,因為卡車車身、電池組和遠端資訊處理服務都可以在國內採購。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府強制推行脫碳政策,並設定目標禁止內燃機(ICE)。
- 海灣合作理事會(GCC)對進口電動車(EV)的補貼和關稅豁免
- 公共直流快速充電走廊的快速發展
- 更低的電池組價格和更長的續航里程
- 石油和天然氣產業推進車輛電氣化的努力預計將引發大量訂單。
- 白天太陽能發電產生的剩餘電力可以實現超低充電速率。
- 市場限制因素
- 車輛初始購買價格高昂,消費貸款受限。
- 原始設備製造商正在限制高溫環境專用型號的供應。
- 電網的不穩定性限制了充電器的運作時間(撒哈拉以南地區)。
- 大量廉價二手內燃機汽車的湧入抑制了對電動車的需求。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 透過驅動系統
- 電池式電動車(BEV)
- 插電式混合動力車(PHEV)
- 燃料電池汽車(FCEV)
- 車輛類型
- 搭乘用車
- 輕型商用車
- 中型和重型商用車輛
- 巴士和長途汽車
- 二輪車和三輪車
- 電池化學成分
- 鋰離子電池(NMC/NCA/LFP)
- 鎳氫電池
- 其他
- 按充電等級
- 交流充電(低速),功率低於 7 千瓦
- 交流充電(半快充)功率從 7 千瓦以上到 22 千瓦
- 22千瓦或以上的直流(快速/超快速)
- 國家
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 以色列
- 埃及
- 南非
- 奈及利亞
- 肯亞
- 卡達
- 阿曼
- 其他中東和非洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Tesla Inc.
- BYD Co. Ltd.
- Hyundai Motor Co.
- Kia Corp.
- Volkswagen AG
- Nissan Motor Co. Ltd.
- BMW Group
- Toyota Motor Corp.
- Stellantis NV
- Mercedes-Benz Group AG
- Renault Group
- Jaguar Land Rover Ltd.
- Zhejiang Geely Holding
- Lucid Group
- Ceer Motors
- Togg AS
- General Motors Co.
- SAIC-MG Motor
- Ford Motor Co.
- Rivian Automotive Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the electric vehicle market size in the Middle East and Africa was valued at USD 3.83 billion in 2025 and estimated to grow from USD 5.06 billion in 2026 to reach USD 20.39 billion by 2031, at a CAGR of 32.15% during the forecast period (2026-2031).
This report is Segmented by Drive Type (Battery-Electric, Plug-In Hybrid, and Fuel-Cell Electric), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Battery Chemistry (Lithium-Ion, Nickel-Metal Hydride, and Others), Charging Level (AC Below 7 KW, and More), and by Country. Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Electric Vehicle Market Trends and Insights
Government Decarbonization Mandates and ICE-Ban Targets
Gulf Cooperation Council (GCC) members have embedded electric-mobility quotas into national development agendas, creating demand floors that anchor OEM investment decisions. Saudi Arabia's Vision 2030 compels 30% of Riyadh's vehicles to be electric by 2030, while the UAE's federal strategy targets a 50% electric-vehicle mix by 2050. These directives funnel public-sector procurement toward zero-emission models, catalyze private-sector fleet conversions, and standardize certification under Gulf Standardization Organization (GSO) rules, which ease cross-border trade. Morocco's mandates 2,500 charging points by 2026, illustrating how firm policy anchors accelerate infrastructure scale-up. Binding targets dovetail with COP28 commitments, giving investors long-cycle visibility, compensating for initial demand volatility.
Rapid Rollout of Public DC Fast-Charging Corridors
Intercity fast-charging corridors convert EVs from urban runabouts into region-wide mobility options. EVIQ's flagship 150 kW site on the Riyadh-Qassim motorway demonstrates highway viability and signals forthcoming coverage of the kingdom's 10 busiest arterial routes. In parallel, the UAE plans 70,000 public chargers across Abu Dhabi by 2030, while Dubai targets 1,000 sites by 2025, effectively eliminating intra-emirate range anxiety. Morocco's plan links Casablanca, Rabat, and Tangier with green-energy-powered DC units that supply sub-30-minute stops. Nigeria's 2025 inauguration of West Africa's largest assembled charging hub widens the infrastructure map to frontier markets. Corridor density materially lifts commercial-vehicle uptime, unlocking electrification for freight operators serving ports such as Jebel Ali.
High Upfront Vehicle Price and Limited Consumer Financing
Purchase-price premiums continue to deter mass-market adoption in lower-income segments even as batteries cheapen. Egypt's EV share remains just 0.1% of new-car sales due to limited installment plans and hard-currency outlays that expose buyers to exchange-rate swings. Traditional lenders, accustomed to securitizing used imports, lack residual-value benchmarks for electric vehicle market loans, inflating interest spreads. In Sub-Saharan Africa, microfinance mechanisms target two-wheeler taxis rather than four-wheeler purchases, further stalling scale economics for OEMs.
Other drivers and restraints analyzed in the detailed report include:
- Day-Time Solar-PV Surplus Driving Ultra-Low-Cost Charging Tariffs
- Oil-and-Gas Fleet-Electrification Pledges Unlocking Bulk Orders
- Influx of Cheap Used ICE Imports Undermines EV Demand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Battery-electric vehicles (BEVs) commanded 78.64% of the electric vehicle market share in 2025, validating the region's preference for fully electric drivetrains and sidestepping the fuel-duty complexity of plug-in hybrids. BEV appeal stems from simpler maintenance and the rollout of destination chargers at malls, airports, and industrial parks. The segment's robust margin structure has enticed Tesla, BYD, and Geely to launch direct-to-consumer sales portals that bypass traditional dealerships.
Fleet operators adopt BEVs for depot-night charging, reducing daytime operational disruptions. Fuel-cell electric vehicles post a 35.90% CAGR through 2031 as Saudi Arabia scales green-hydrogen refueling nodes around its industrial corridors, underscoring their long-haul potential. Meanwhile, plug-in hybrids remain transitional, offering range security where grid reliability lags. The drive-type mix therefore mirrors infrastructure maturity, with BEVs prevailing in the urban Gulf and fuel-cells rising along desert freight links.
Passenger cars controlled 64.05% of 2025 revenue, yet medium and heavy commercial vehicles are forecast to outpace with a 35.05% CAGR to 2031, expanding the electric vehicle market size in corporate procurement channels. Oil-field service trucks and last-mile delivery vans accrue higher daily mileage, magnifying fuel savings and carbon audit benefits. Logistics firms in the Jeddah free zone now specify electric models in tenders to comply with port authority emissions limits. Bus electrification pilots in Cairo and Cape Town indicate growing public-transport appetite, while ride-hailing operators deploy small hatchback EVs to meet city-center clean-air mandates. OEMs are responding with region-tuned payload ratings, enhanced cabin HVAC, and reinforced suspensions for unpaved routes. As commercial volumes climb, supply-chain localization deepens because truck bodies, battery enclosures, and telematics services can all be sourced domestically.
Complete Report Scope:
- By Drive Type
- Battery-Electric (BEV)
- Plug-in Hybrid (PHEV)
- Fuel-Cell Electric (FCEV)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Buses and Coaches
- Two and Three Wheelers
- By Battery Chemistry
- Lithium-ion (NMC / NCA / LFP)
- Nickel-Metal Hydride
- Others
- By Charging Level
- AC below 7 kW (Slow)
- AC above 7 kW - 22 kW (Semi-fast)
- DC above 22 kW (Fast / Ultra-fast)
- By Country
- Saudi Arabia
- United Arab Emirates
- Israel
- Egypt
- South Africa
- Nigeria
- Kenya
- Qatar
- Oman
- Rest of Middle East and Africa
List of Companies Covered in this Report:
- Tesla Inc.
- BYD Co. Ltd.
- Hyundai Motor Co.
- Kia Corp.
- Volkswagen AG
- Nissan Motor Co. Ltd.
- BMW Group
- Toyota Motor Corp.
- Stellantis N.V.
- Mercedes-Benz Group AG
- Renault Group
- Jaguar Land Rover Ltd.
- Zhejiang Geely Holding
- Lucid Group
- Ceer Motors
- Togg A.S.
- General Motors Co.
- SAIC-MG Motor
- Ford Motor Co.
- Rivian Automotive Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Decarbonizations Mandates and ICE-Ban Targets
- 4.2.2 Subsidies And Zero-Customs Duties on EV Imports (GCC)
- 4.2.3 Rapid Rollout of Public DC Fast-Charging Corridors
- 4.2.4 Declining Battery Pack Prices and Longer Driving Range
- 4.2.5 Oil-and-Gas Fleet Electrification Pledges Unlocking Bulk Orders
- 4.2.6 Day-Time Solar-PV Surplus Driving Ultra-Low-Cost Charging Tariffs
- 4.3 Market Restraints
- 4.3.1 High Upfront Vehicle Price and Limited Consumer Financing
- 4.3.2 Restricted Hot-Climate Model Availability From OEMs
- 4.3.3 Grid Unreliability Curbing Charger Uptime (Sub-Saharan Sites)
- 4.3.4 Influx of Cheap Used ICE Imports Undermines EV Demand
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD Million)
- 5.1 By Drive Type
- 5.1.1 Battery-Electric (BEV)
- 5.1.2 Plug-in Hybrid (PHEV)
- 5.1.3 Fuel-Cell Electric (FCEV)
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Medium and Heavy Commercial Vehicles
- 5.2.4 Buses and Coaches
- 5.2.5 Two and Three Wheelers
- 5.3 By Battery Chemistry
- 5.3.1 Lithium-ion (NMC / NCA / LFP)
- 5.3.2 Nickel-Metal Hydride
- 5.3.3 Others
- 5.4 By Charging Level
- 5.4.1 AC below 7 kW (Slow)
- 5.4.2 AC above 7 kW - 22 kW (Semi-fast)
- 5.4.3 DC above 22 kW (Fast / Ultra-fast)
- 5.5 By Country
- 5.5.1 Saudi Arabia
- 5.5.2 United Arab Emirates
- 5.5.3 Israel
- 5.5.4 Egypt
- 5.5.5 South Africa
- 5.5.6 Nigeria
- 5.5.7 Kenya
- 5.5.8 Qatar
- 5.5.9 Oman
- 5.5.10 Rest of Middle East and Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Tesla Inc.
- 6.4.2 BYD Co. Ltd.
- 6.4.3 Hyundai Motor Co.
- 6.4.4 Kia Corp.
- 6.4.5 Volkswagen AG
- 6.4.6 Nissan Motor Co. Ltd.
- 6.4.7 BMW Group
- 6.4.8 Toyota Motor Corp.
- 6.4.9 Stellantis N.V.
- 6.4.10 Mercedes-Benz Group AG
- 6.4.11 Renault Group
- 6.4.12 Jaguar Land Rover Ltd.
- 6.4.13 Zhejiang Geely Holding
- 6.4.14 Lucid Group
- 6.4.15 Ceer Motors
- 6.4.16 Togg A.S.
- 6.4.17 General Motors Co.
- 6.4.18 SAIC-MG Motor
- 6.4.19 Ford Motor Co.
- 6.4.20 Rivian Automotive Inc.
7 Market Opportunities & Future Outlook

 2026年全球電動車市場預測印度電動車市場,2025-2032年
 北美電動車市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)新加坡電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)法國電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)電動車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)越南電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)電動車中800V架構的演變非洲電動車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)東協電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)