


 |
市場調查報告書
商品編碼
2125746
越南電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)Vietnam Electric Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
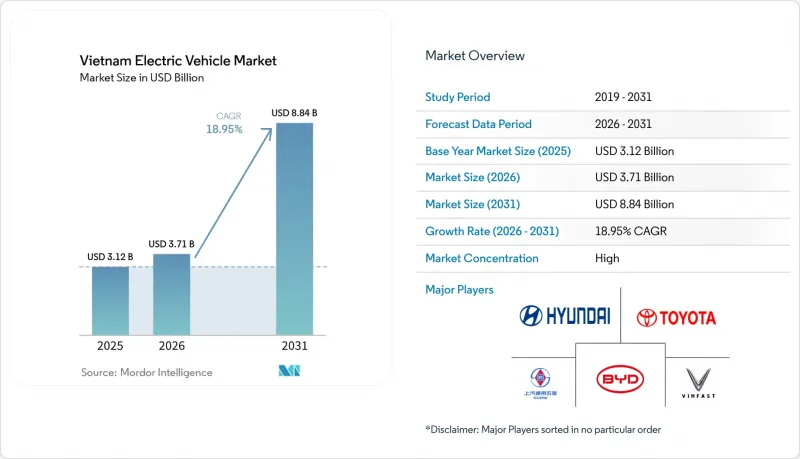
根據 Mordor Intelligence 預測,越南電動車市場規模預計將從 2025 年的 31.2 億美元成長到 2026 年的 37.1 億美元。
此外,預計到 2031 年,該產業的價值將達到 88.4 億美元,並且預計從 2026 年到 2031 年的複合年成長率將達到 18.95%。
本報告按車輛類型(乘用車、商用車、其他)、驅動方式(電池式電動車、插電式混合動力車、其他)、續航里程(200公里以下、200-400公里、其他)、電池類型(磷酸鐵鋰電池、其他)、最終用戶(私人所有、其他)和地區進行分類。市場預測以貨幣價值(美元)和銷售(輛)兩種形式呈現。
越南電動車市場趨勢與洞察
擴大國內生產規模(VinFast 和進口車)
VinFast的目標是到2026年實現約80%的國內採購比例,併計劃到2027年將其產能擴大至約50萬台,到2030年達到每年100萬台。此次產能擴張旨在降低零件的單位成本,深化供應商本地化,並降低進口零件相關的外匯波動風險。奇瑞和吉利的同步投資計畫進一步鞏固了越南作為新興區域組裝和出口中心的地位。然而,對於先進半導體、電力電子和電池管理系統等高附加價值零件,由於國內產能有限,越南仍高度依賴進口。 VinFast主導的長期採購和外送協議,為本地供應商提供了更清晰的需求前景,鼓勵了新的資本投資、技術轉讓,並加速了生態系統的在地化進程。
政府獎勵和退稅
在國家獎勵框架下,純電動車(BEV)的註冊費將完全免除至2027年2月,顯著降低了消費者和車隊營運商的初始購買成本。同時,根據現行的區域貿易協定,從東協成員國進口的車輛關稅仍為0%,使得每款符合資格的車型零售價格降低超過1億越南盾。電動車的優惠充電費率設定為每千瓦時約2204越南盾,進一步改善了其全生命週期營運經濟性,縮短了投資回收期(與內燃機汽車相比),並增強了總擁有成本(TCO)的競爭力,凸顯了多層次政策協調的成效。 2027年後的持續性取決於成本平價的實現,而市場面臨與財政政策延續相關的風險。
公共充電基礎設施不足
雖然主要都會地區的充電基礎設施相對完善,但農村地區和城際走廊沿線的覆蓋率卻急劇下降,這阻礙了長途旅行的可行性,並限制了續航里程超過200公里的車型需求。這種分佈不均制約了市場向大都會圈以外更廣泛區域的擴張。 V-Green公司正在投資約4.04億美元,以加快在全國部署充電站,但考慮到授權程序、電網整合計劃和建設前置作業時間,預計短期內仍將面臨瓶頸。電力需求的季節性激增進一步加劇了電網風險,政府已發布指南,重點加強輸電能力並確保電力供應的韌性,以支持電動車的永續普及。
細分市場分析
預計到2025年,乘用車將佔總收入的67.65%,繼續保持其在整體市場中的主導地位,而公車則以33.11%的複合年成長率呈現最快成長勢頭。在地方政府強制推行電氣化政策的推動下,公車市場預計將在2028年之前快速擴張,這將促進大規模公共競標和系統化的採購流程。儘管目前私人擁有的公車數量占主導地位,但商業業者的需求正在顯著成長。胡志明市的大規模部署以及河內市中心區的電氣化藍圖正在帶來可預測的大訂單,這提高了供應商的可見度和生產規劃能力。
車隊營運的高日均運轉率進一步提升了整體擁有成本 (TCO) 優勢,使商業買家能夠率先採用者先進的電池化學技術和大容量快速充電解決方案。同時,摩托車繼續滿足郊區和農村交通走廊的通勤需求,間接提高了充電站的利用效率,並促進了四輪車輛的普及。在整個預測期內,儘管乘用車銷售絕對值有所成長,但預計其市佔率成長率將略有放緩。這主要是由於在政策支持下,公車和電動貨車在公共交通現代化和最後一公里物流網路建設中發展勢頭強勁。
到2025年,電池式電動車(BEV)將佔據70.82%的市場佔有率,明顯優於混合動力汽車和插電式混合動力車等其他車型。在各國優先發展全面電氣化而非過渡性驅動技術的政策支持下,純電動車的銷售量預計將以27.85%的複合年成長率成長,並且這一領先優勢有望進一步擴大。混合動力車在郊區用戶中仍保持著一定的市場需求,這些用戶追求的是續航里程的柔軟性,但由於財政獎勵相對有限,混合動力汽車的普及受到限制。燃料電池汽車由於氫能基礎設施不完善和部署成本高昂,目前仍主要處於測試階段。
VinFast專注於純電動車(BEV)的產品策略,進一步鞏固了其在消費者心目中純電動車的地位,而全國範圍內的充電補貼獎勵也進一步促進了其普及。儘管國際汽車製造商可能會推出插電式混合動力(PHV)車型以緩解消費者對續航里程的擔憂,但監管趨勢仍然傾向於純電動車平台。電池技術的不斷進步正在縮短充電時間並提高能量密度,縮小了曾經支撐混合動力汽車溢價的功能差距。因此,越南的電動車市場正直接向純電動車轉型,而不是像一些成熟經濟體那樣逐步過渡到混合動力汽車。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大國內生產規模(VinFast 和進口車)
- 政府獎勵和退稅
- 日益增強的環保意識和淨零排放目標
- 電動摩托車生態系的漣漪效應
- 電池組價格正在下降。
- 電動車充電優惠收費系統
- 市場限制因素
- 公共充電基礎設施不足
- 高額的車輛購置成本與平均收入的比較
- 中階機型供應有限
- 尖峰時段電網容量受限
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 電動車充電基礎設施建設
第5章 市場規模與成長預測
- 按車輛類型
- 搭乘用車
- 商用車輛
- 摩托車
- 公車
- 透過驅動系統
- 電池式電動車(BEV)
- 插電式混合動力車(PHEV)
- 混合動力電動車(HEV)
- 燃料電池汽車(FCEV)
- 透過練習場
- 200公里或更短
- 200~400km
- 超過400公里
- 依電池類型
- LFP
- NMC/NCA
- 其他
- 最終用戶
- 個人所有
- 商用車輛/共乘
- 政府/公共交通
- 按地區
- 越南北部
- 越南中部
- 越南南部
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- VinFast Auto Ltd.
- Hyundai Motor Company
- Toyota Motor Corporation
- BYD Auto Co. Ltd
- SAIC-GM-Wuling Automobile Co., Ltd.
- Tesla Inc.
- Mercedes-Benz Group AG
- Kia Corporation
- Nissan Motor Co. Ltd
- Honda Motor Co. Ltd
- MG汽車(中國)
- Chery Automobile Co.
- Great Wall Motor(Haval)
- Volvo Car AB
- Selex Motors(VN)
- Dat Bike(VN)
- Foxconn EV Charging(VN)
- VinES Battery(VN)
- ABB越南(充電器)
- Delta Electronics(VN)
第7章 市場機會與未來展望
According to Mordor Intelligence, the Vietnam electric vehicle market size in 2026 is estimated at USD 3.71 billion, growing from the 2025 value of USD 3.12 billion, with 2031 projections showing USD 8.84 billion, growing at 18.95% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Passenger Cars, Commercial Vehicles, and More), Propulsion (Battery Electric Vehicles, Plug-In Hybrid Electric Vehicles, and More), Driving Range (Below 200 Km, 200 To 400 Km, and More), Battery Type (LFP, and More), End User (Private Ownership and More), and Region. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Vietnam Electric Vehicle Market Trends and Insights
Domestic Manufacturing Scale-up
VinFast targets roughly 80% domestic content by 2026 while expanding installed capacity to about 500,000 vehicles by 2027 and up to 1 million units annually by 2030. This scale-up is designed to compress per-unit component costs, deepen supplier localization, and reduce exposure to exchange-rate volatility tied to imported parts. Parallel investment plans from Chery and Geely further strengthen Vietnam's position as an emerging regional assembly and export hub. However, high-value components such as advanced semiconductors, power electronics, and battery management systems continue to rely significantly on imports due to limited domestic fabrication capability. Long-term procurement and offtake agreements led by VinFast provide local suppliers with stronger demand visibility, supporting fresh capital expenditure, technology transfer, and faster ecosystem localization.
Government Incentives and Tax Rebates
The national incentive framework extends full registration-fee exemptions for battery electric vehicles through February 2027, materially lowering upfront acquisition costs for consumers and fleet operators. In parallel, import duties remain at 0% for vehicles sourced from ASEAN member states under prevailing regional trade agreements, reducing retail prices by more than VND 100 million per unit for qualifying models. Preferential EV charging tariffs set at approximately 2,204 VND/kWh further improve lifetime operating economics, narrowing payback periods versus internal combustion alternatives and strengthening the total cost of ownership proposition, underscoring multi-tier policy coordination. Continuity beyond 2027 depends on reaching cost parity, exposing the market to fiscal-policy rollover risk.
Sparse Public Charging Infrastructure
While charging infrastructure remains relatively dense across tier-one urban clusters, coverage declines sharply along rural and inter-city corridors, constraining long-distance travel viability and limiting demand for models exceeding sub-200 km range brackets. This uneven distribution restricts broader geographic market expansion beyond metropolitan centers. V-Green has committed approximately USD 404 million to accelerate nationwide station deployment, yet permitting cycles, grid integration timelines, and construction lead times suggest near-term bottlenecks will persist. Seasonal electricity demand spikes further expose grid stress risks, prompting government directives focused on strengthening transmission capacity and ensuring power-supply resilience to support sustained EV penetration.
Other drivers and restraints analyzed in the detailed report include:
- Rising Environmental Awareness and Net-Zero Targets
- Electric Two-wheeler Ecosystem Spill-over
- High Up-front Vehicle Cost vs Average Income
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars accounted for 67.65% of total revenue in 2025, maintaining leadership in overall market contribution, while buses recorded the fastest expansion trajectory at a 33.11% CAGR. The bus segment is expected to scale rapidly through 2028 as provincial electrification mandates unlock sizeable public tenders and structured procurement cycles. Although private ownership dominates the current vehicle base, commercial operators are increasingly shaping incremental demand. Large-scale deployments in Ho Chi Minh City and the central-district electrification roadmap in Hanoi are creating predictable bulk orders that strengthen supplier visibility and manufacturing planning.
High daily utilization rates in fleet operations amplify total-cost-of-ownership advantages, positioning commercial buyers as early adopters of advanced battery chemistries and high-capacity fast-charging solutions. Meanwhile, two-wheelers continue serving commuter flows across peri-urban and rural corridors, indirectly improving charging-station utilization economics that also support four-wheeler penetration. Over the forecast horizon, passenger-car revenue share is likely to moderate slightly despite rising absolute volumes, as buses and electric vans gain policy-driven traction in public transport modernization and last-mile logistics networks.
Battery electric vehicles (BEVs) accounted for 70.82% of the total market share in 2025, clearly outperforming hybrid and plug-in hybrid alternatives. This lead is expected to widen as BEV volumes expand at a projected 27.85% CAGR, supported by a national policy framework that prioritizes full electrification over transitional drivetrain technologies. Hybrids retain selective demand among peri-urban users seeking extended range flexibility, yet comparatively limited fiscal incentives constrain broader uptake. Fuel-cell vehicles remain largely at a pilot stage due to minimal hydrogen infrastructure and high deployment costs.
VinFast's concentrated BEV-focused product strategy reinforces the pure-electric positioning in consumer perception, while nationwide charging incentives further strengthen adoption momentum. International automakers may introduce plug-in hybrid variants as a hedge against residual range anxiety, but regulatory direction continues to favor fully electric platforms. Continuous battery improvements are reducing charging times and improving energy density, narrowing the functional gap that once justified hybrid premiums. Consequently, the Vietnam electric vehicle market is progressing along a direct-to-BEV trajectory rather than following the phased hybrid transition observed in several mature economies.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Two-Wheelers
- Buses
- By Propulsion
- Battery Electric Vehicles (BEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Hybrid Electric Vehicles (HEV)
- Fuel-Cell Electric Vehicles (FCEV)
- By Driving Range
- Below 200 km
- 200 to 400 km
- Above 400 km
- By Battery Type
- LFP
- NMC/NCA
- Others
- By End User
- Private Ownership
- Commercial Fleet/Ride-Hailing
- Government and Public Transport
- By Region
- Northern Vietnam
- Central Vietnam
- Southern Vietnam
List of Companies Covered in this Report:
- VinFast Auto Ltd.
- Hyundai Motor Company
- Toyota Motor Corporation
- BYD Auto Co. Ltd
- SAIC-GM-Wuling Automobile Co., Ltd.
- Tesla Inc.
- Mercedes-Benz Group AG
- Kia Corporation
- Nissan Motor Co. Ltd
- Honda Motor Co. Ltd
- MG Motor (China)
- Chery Automobile Co.
- Great Wall Motor (Haval)
- Volvo Car AB
- Selex Motors (VN)
- Dat Bike (VN)
- Foxconn EV Charging (VN)
- VinES Battery (VN)
- ABB Vietnam (Chargers)
- Delta Electronics (VN)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Domestic Manufacturing Scale-up (VinFast and Imports)
- 4.2.2 Government Incentives and Tax Rebates
- 4.2.3 Rising Environmental Awareness and Net-Zero Targets
- 4.2.4 Electric Two-Wheeler Ecosystem Spill-Over
- 4.2.5 Falling Battery Pack Prices
- 4.2.6 Preferential EV-Charging Tariff Structure
- 4.3 Market Restraints
- 4.3.1 Sparse Public Charging Infrastructure
- 4.3.2 High Up-Front Vehicle Cost Vs Average Income
- 4.3.3 Limited Mid-Range Model Availability
- 4.3.4 Grid Capacity Constraints At Peak Hours
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 EV Charging Infrastructure Development
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Commercial Vehicles
- 5.1.3 Two-Wheelers
- 5.1.4 Buses
- 5.2 By Propulsion
- 5.2.1 Battery Electric Vehicles (BEV)
- 5.2.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 5.2.3 Hybrid Electric Vehicles (HEV)
- 5.2.4 Fuel-Cell Electric Vehicles (FCEV)
- 5.3 By Driving Range
- 5.3.1 Below 200 km
- 5.3.2 200 to 400 km
- 5.3.3 Above 400 km
- 5.4 By Battery Type
- 5.4.1 LFP
- 5.4.2 NMC/NCA
- 5.4.3 Others
- 5.5 By End User
- 5.5.1 Private Ownership
- 5.5.2 Commercial Fleet/Ride-Hailing
- 5.5.3 Government and Public Transport
- 5.6 By Region
- 5.6.1 Northern Vietnam
- 5.6.2 Central Vietnam
- 5.6.3 Southern Vietnam
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 VinFast Auto Ltd.
- 6.4.2 Hyundai Motor Company
- 6.4.3 Toyota Motor Corporation
- 6.4.4 BYD Auto Co. Ltd
- 6.4.5 SAIC-GM-Wuling Automobile Co., Ltd.
- 6.4.6 Tesla Inc.
- 6.4.7 Mercedes-Benz Group AG
- 6.4.8 Kia Corporation
- 6.4.9 Nissan Motor Co. Ltd
- 6.4.10 Honda Motor Co. Ltd
- 6.4.11 MG Motor (China)
- 6.4.12 Chery Automobile Co.
- 6.4.13 Great Wall Motor (Haval)
- 6.4.14 Volvo Car AB
- 6.4.15 Selex Motors (VN)
- 6.4.16 Dat Bike (VN)
- 6.4.17 Foxconn EV Charging (VN)
- 6.4.18 VinES Battery (VN)
- 6.4.19 ABB Vietnam (Chargers)
- 6.4.20 Delta Electronics (VN)
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 2026年全球電動車市場預測印度電動車市場,2025-2032年
 北美電動車市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)新加坡電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)法國電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)電動車:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)電動車中800V架構的演變非洲電動車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)東協電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)800V電動車架構的市場規模、佔有率、成長、全球產業分析、區域趨勢與2026年至2034年預測