


 |
市場調查報告書
商品編碼
2121827
北美工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)North America Factory Automation And Industrial Controls - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年北美工廠自動化和工業控制市場價值為 550.7 億美元,預計到 2031 年將達到 972.7 億美元,而 2026 年為 605.5 億美元,預測期(2026-2031 年)的複合成長率為 9.95%。
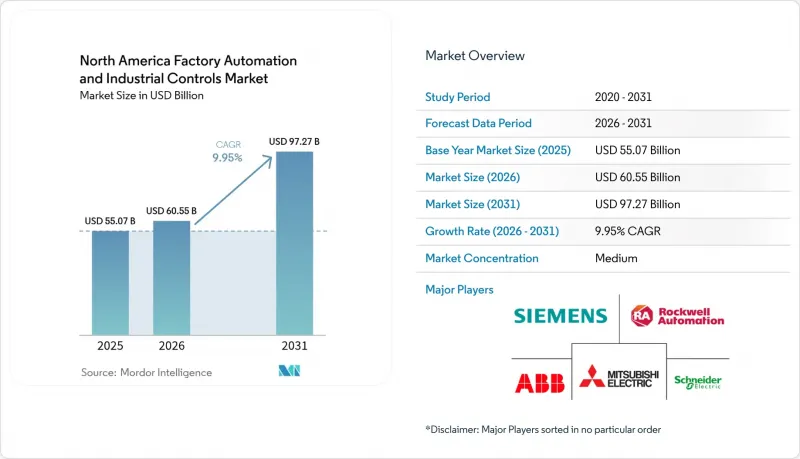
本報告按類型(工業控制系統和現場設備)、組件(硬體、軟體和服務)、部署模式(本地部署、雲端部署和邊緣部署)、最終用戶產業(石油天然氣、化學和石化、電力和公共產業等)以及國家/地區進行細分。市場預測以美元(USD)計價。
北美工廠自動化與工業控制市場趨勢及洞察
對節能製造營運的需求激增
北美各地的製造商正在實施先進的控制迴路、負載平衡和即時能源儀錶板,以滿足各州和地方政府嚴格的能源效率法規並降低能源成本。現有生產線進行改造,加裝變頻驅動器和智慧調度模組,通常可降低20%至30%的總電力消耗量。這種節能效益超過了生產力提升帶來的投資回報,從而加快了董事會批准其他自動化項目的速度。整合現場可再生能源和智慧控制器的工廠正在參與電網穩定計劃,創造新的收入來源。工廠團隊不僅需要硬體,還需要全面的藍圖,因此提供成套試運行服務和ISO 50001諮詢服務的供應商正在贏得合約。隨著華盛頓和渥太華關於碳定價的辯論再次升溫,先驅者正在獲得永續的成本優勢,這些優勢將隨著時間的推移而不斷成長。
中小企業工廠迅速採用合作機器人
中小企業正在採用價格在 11 萬至 20 萬美元之間的協作機器人。這是因為這些機器人所需的防護措施極少,而且現有技術人員即可重新部署。協作機器人可以處理重複性的取放任務、機器操作和輕型組裝組裝,使員工能夠專注於更高價值的檢驗任務。考慮到減少加班費和產品缺陷,投資回收期通常為 18 個月或更短。無需重新設計整條生產線柔軟性切換 SKU,這符合北美中小企業典型的「多品種、小批量生產」需求。隨著成功案例在區域製造協會中傳播,在同行的支持下,協作機器人的採用正在加速,進一步擴大了北美工廠自動化和工業控制市場。
傳統控制系統中的網路安全漏洞
美國網路安全與基礎設施安全局 (CISA) 於 2024 年揭露了廣泛部署的 PLC 和 HMI 平台中存在的多個遠端程式碼執行漏洞。那些急於將隔離網路連接到遠端監控系統的工廠,如今面臨更大的攻擊面。修補漏洞通常需要運作的停機時間和控制器更換,這給維護預算帶來了巨大壓力。隨著保險公司重新評估營運技術的風險,保險費也在上漲。一些工廠正在推遲新的數位轉型,直到零信任架構成熟,這暫時減緩了北美工廠自動化和工業控制市場的成長。
細分市場分析
到2025年,工業控制系統將成為北美工廠自動化和工業控制市場最大的收入來源,佔58.15%的市場。現場設備展現出更強勁的成長勢頭,複合年成長率(CAGR)達到10.85%,這將推動感測器和視覺系統供應商的業績成長。集中式控制器與蓬勃發展的邊緣設備之間整合的複雜性,促使買家更傾向於整合工程套件。隨著工廠對傳統程式碼進行現代化改造並添加情境資料層,與分散式控制系統和PLC升級相關的北美工廠自動化和工業控制市場規模持續擴大。
協作機器人、先進的機器視覺技術和多軸運動套件的出現推動了現場設備的成長,這些技術提高了品質保證和生產效率。供應商為關鍵控制平台提供現成的整合功能,從而縮短了專案週期,這對於旨在縮短建模時間的頂級汽車製造商的生產線至關重要。設備數據持續串流到分析中心,為人工智慧模型提供數據,從而最佳化週期時間和預測性維護規則。因此,與硬體捆綁銷售的軟體庫和協議轉換器如今在北美工廠自動化和工業控制市場創造了高利潤率。
到2025年,硬體將佔銷售額的60.05%,這反映了數千家工廠安裝的實體資產。然而,隨著工廠開始利用潛在數據來提高生產力和永續性,軟體正以10.98%的複合年成長率成長。雲端歷史資料庫、人工智慧工具包和數位孿生技術擴大與驅動器和感測器捆綁銷售,這表明價值創造正在轉移到程式碼中。預計到2031年,北美工廠自動化和工業控制市場中與工業軟體訂閱相關的規模將與單一硬體的支出不相上下。
這種邊緣到雲端的架構使工廠能夠在本地採集高頻訊號,同時將匯總資訊傳輸到中央控制面板。模擬包裝功能幫助工程師離線測試配方變更,進而減少產品推出時的缺陷。擴增實境(AR) 驅動的工作指導提高了技術人員的準確性,並縮短了培訓時間。將網路安全模組整合到標準許可證中,滿足了董事會和保險公司尋求風險緩解的需求,使該軟體從簡單的可選附加組件提升為戰略性必需品。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對節能型製造營運的需求激增
- 中小企業工廠迅速採用合作機器人
- 聯邦政府的激勵措施加速了電子產品生產回流國內。
- 5G賦能的工業IoT網路的整合
- 由於技術純熟勞工短缺,推廣自主物料輸送
- 透過人工智慧驅動的預測性維護減少意外停機時間。
- 市場限制因素
- 傳統控制系統中的網路安全漏洞
- 由於利率高企,中型製造商凍結了資本投資。
- 關鍵自動化組件的供應鏈波動
- 北美互通性標準的碎片化
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 工業控制系統
- 分散式控制系統(DCS)
- 可程式邏輯控制器(PLC)
- 監控、控制和資料採集(SCADA)
- 產品生命週期管理(PLM)
- 人機介面(HMI)
- 製造執行系統(MES)
- 現場設備
- 機器視覺系統
- 工業機器人
- 感測器發射器
- 馬達驅動
- 其他現場設備
- 工業控制系統
- 按組件
- 硬體
- 軟體
- 服務
- 部署模式
- 現場
- 雲
- 邊緣
- 按最終用戶行業分類
- 石油和天然氣
- 化工/石油化工
- 電力/公共產業
- 飲食
- 車
- 金屬和採礦
- 製藥
- 其他
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Rockwell Automation Inc.
- Siemens AG
- Mitsubishi Electric Corporation
- ABB Ltd.
- Schneider Electric SE
- Honeywell International Inc.
- Emerson Electric Company
- Omron Corporation
- Yokogawa Electric Corporation
- Yaskawa Electric Corporation
- KUKA AG
- Fanuc Corporation
- Beckhoff Automation GmbH and Co. KG
- Schneider Electric Motion USA Inc.
- Regal Rexnord Corporation
- Nidec Motor Corporation
- Basler AG
- Cognex Corporation
- Bosch Rexroth AG
- Parker Hannifin Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America factory automation and industrial controls market size was valued at USD 55.07 billion in 2025 and estimated to grow from USD 60.55 billion in 2026 to reach USD 97.27 billion by 2031, at a CAGR of 9.95% during the forecast period (2026-2031).
This report is Segmented by Type (Industrial Control Systems and Field Devices), Component (Hardware, Software, and Services), Deployment Mode (On-Premise, Cloud, and Edge), End-User Industry (Oil and Gas, Chemical and Petrochemical, Power and Utilities, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Factory Automation And Industrial Controls Market Trends and Insights
Surge in demand for energy-efficient manufacturing operations
Manufacturers across North America implement advanced control loops, load balancing, and real-time energy dashboards to meet strict state and provincial efficiency rules and to cut utility costs. Retrofitting variable-frequency drives and intelligent scheduling modules into legacy lines typically lowers total electricity consumption by 20% to 30%. Savings arrive faster than productivity-led paybacks, which accelerates board approval for additional automation projects. Facilities integrating on-site renewable power with smart controllers participate in grid-stabilization programs that offer new revenue streams. Vendors that package commissioning services with ISO 50001 advisory win contracts because plant teams need holistic road maps, not just hardware. As carbon pricing discussions resurface in Washington and Ottawa, early movers lock sustainable cost advantages that compound over time.
Rapid adoption of collaborative robots in SME factories
Small and mid-size enterprises adopt collaborative robots priced between USD 110,000 and USD 200,000 because the units require minimal guarding and can be re-tasked by existing technicians. Cobots handle repetitive pick-and-place, machine tending, and light assembly while employees focus on value-added inspection. Payback periods often fall below 18 months when overtime premiums and scrap reductions are considered. The flexibility to shift between SKUs without re-engineering entire lines aligns with the low-volume, high-variety production typical of North American SMEs. As success stories spread through regional manufacturing associations, peer endorsement accelerates wider deployments, further enlarging the North America factory automation and industrial controls market.
Cybersecurity vulnerabilities in legacy control systems
The Cybersecurity and Infrastructure Security Agency disclosed multiple remote-code-execution flaws in widely deployed PLC and HMI platforms during 2024. Plants that rushed to connect isolated networks for remote monitoring now face expanded attack surfaces. Patching often requires costly downtime or controller replacement, which stretches maintenance budgets. Insurance premiums climb as underwriters reassess operational-technology risk. Some facilities delay new digitization until zero-trust architectures mature, temporarily slowing the North America factory automation and industrial controls market.
Other drivers and restraints analyzed in the detailed report include:
- Federal incentives accelerating on-shoring of electronics production
- AI-driven predictive maintenance reducing unplanned downtime
- Supply-chain volatility for critical automation components
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial control systems generated the largest revenue in 2025 with a 58.15% share of the North America factory automation and industrial controls market. Field devices displayed stronger momentum, recording an 10.85% CAGR that is lifting sensor and vision-system suppliers. Integration complexity between centralized controllers and proliferating edge devices motivates buyers to favor unified engineering suites. The North America factory automation and industrial controls market size attached to distributed control systems and PLC upgrades continues to rise as plants modernize legacy code and add contextual data layers.
Growth in field devices stems from collaborative robotics, advanced machine vision, and multi-axis motion kits that bolster quality assurance and throughput. Vendors offering out-of-the-box links to major control platforms shorten project cycles, a key factor for tier-one automotive lines targeting shorter model launches. Continuous streaming of device data into analytics hubs also feeds AI models that refine cycle timing and predictive maintenance rules. As a result, software libraries and protocol converters bundled with hardware now command premium margins across the North America factory automation and industrial controls market.
Hardware still contributed 60.05% of 2025 revenue, reflecting the physical assets installed across thousands of factories. Software, however, advances at an 10.98% CAGR as plants unlock latent data for productivity and sustainability gains. Cloud historians, AI toolkits, and digital twins increasingly ship alongside drives and sensors, proving that value creation has migrated toward code. The North America factory automation and industrial controls market size linked to industrial-software subscriptions is on track to rival discrete hardware outlays by 2031.
Edge-to-cloud architectures let plants collect high-frequency signals locally while pushing summarized insights to central dashboards. Simulation packages help engineers test recipe changes offline, reducing scrap at launch. Augmented-reality work instructions improve technician accuracy and shorten training curves. Integration of cybersecurity modules within standard licenses also answers board and insurer demands for risk mitigation, elevating software from an optional add-on to a strategic requirement.
Complete Report Scope:
- By Type
- Industrial Control Systems
- Distributed Control System (DCS)
- Programmable Logic Controller (PLC)
- Supervisory Control and Data Acquisition (SCADA)
- Product Lifecycle Management (PLM)
- Human Machine Interface (HMI)
- Manufacturing Execution System (MES)
- Field Devices
- Machine Vision Systems
- Robotics (Industrial)
- Sensors and Transmitters
- Motors and Drives
- Other Field Devices
- Industrial Control Systems
- By Component
- Hardware
- Software
- Services
- By Deployment Mode
- On-premise
- Cloud
- Edge
- By End-user Industry
- Oil and Gas
- Chemical and Petrochemical
- Power and Utilities
- Food and Beverages
- Automotive
- Metals and Mining
- Pharmaceuticals
- Other Industries
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Rockwell Automation Inc.
- Siemens AG
- Mitsubishi Electric Corporation
- ABB Ltd.
- Schneider Electric SE
- Honeywell International Inc.
- Emerson Electric Company
- Omron Corporation
- Yokogawa Electric Corporation
- Yaskawa Electric Corporation
- KUKA AG
- Fanuc Corporation
- Beckhoff Automation GmbH and Co. KG
- Schneider Electric Motion USA Inc.
- Regal Rexnord Corporation
- Nidec Motor Corporation
- Basler AG
- Cognex Corporation
- Bosch Rexroth AG
- Parker Hannifin Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in demand for energy-efficient manufacturing operations
- 4.2.2 Rapid adoption of collaborative robots in SME factories
- 4.2.3 Federal incentives accelerating on-shoring of electronics production
- 4.2.4 Integration of 5G-enabled industrial IoT networks
- 4.2.5 Shortage of skilled labor spurring autonomous material handling
- 4.2.6 AI-driven predictive maintenance reducing unplanned downtime
- 4.3 Market Restraints
- 4.3.1 Cybersecurity vulnerabilities in legacy control systems
- 4.3.2 Capex freeze among mid-tier manufacturers amid high interest rates
- 4.3.3 Supply-chain volatility for critical automation components
- 4.3.4 Fragmented North American interoperability standards
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Type
- 5.1.1 Industrial Control Systems
- 5.1.1.1 Distributed Control System (DCS)
- 5.1.1.2 Programmable Logic Controller (PLC)
- 5.1.1.3 Supervisory Control and Data Acquisition (SCADA)
- 5.1.1.4 Product Lifecycle Management (PLM)
- 5.1.1.5 Human Machine Interface (HMI)
- 5.1.1.6 Manufacturing Execution System (MES)
- 5.1.2 Field Devices
- 5.1.2.1 Machine Vision Systems
- 5.1.2.2 Robotics (Industrial)
- 5.1.2.3 Sensors and Transmitters
- 5.1.2.4 Motors and Drives
- 5.1.2.5 Other Field Devices
- 5.1.1 Industrial Control Systems
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Deployment Mode
- 5.3.1 On-premise
- 5.3.2 Cloud
- 5.3.3 Edge
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Power and Utilities
- 5.4.4 Food and Beverages
- 5.4.5 Automotive
- 5.4.6 Metals and Mining
- 5.4.7 Pharmaceuticals
- 5.4.8 Other Industries
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Rockwell Automation Inc.
- 6.4.2 Siemens AG
- 6.4.3 Mitsubishi Electric Corporation
- 6.4.4 ABB Ltd.
- 6.4.5 Schneider Electric SE
- 6.4.6 Honeywell International Inc.
- 6.4.7 Emerson Electric Company
- 6.4.8 Omron Corporation
- 6.4.9 Yokogawa Electric Corporation
- 6.4.10 Yaskawa Electric Corporation
- 6.4.11 KUKA AG
- 6.4.12 Fanuc Corporation
- 6.4.13 Beckhoff Automation GmbH and Co. KG
- 6.4.14 Schneider Electric Motion USA Inc.
- 6.4.15 Regal Rexnord Corporation
- 6.4.16 Nidec Motor Corporation
- 6.4.17 Basler AG
- 6.4.18 Cognex Corporation
- 6.4.19 Bosch Rexroth AG
- 6.4.20 Parker Hannifin Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need assessment

 4U工業電腦市場-2026年至2032年全球市場預測
 2034 年工業自動化網路安全市場預測—按部署類型、安全類型、組件、服務類型、技術、應用、最終用戶和地區分類的全球分析
 工廠自動化與工業控制:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)美國工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)日本工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)歐洲工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)義大利工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)法國工廠自動化和工業控制:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)中國工廠自動化與工業控制:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)