


 |
市場調查報告書
商品編碼
2121518
英國塑膠包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)United Kingdom Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
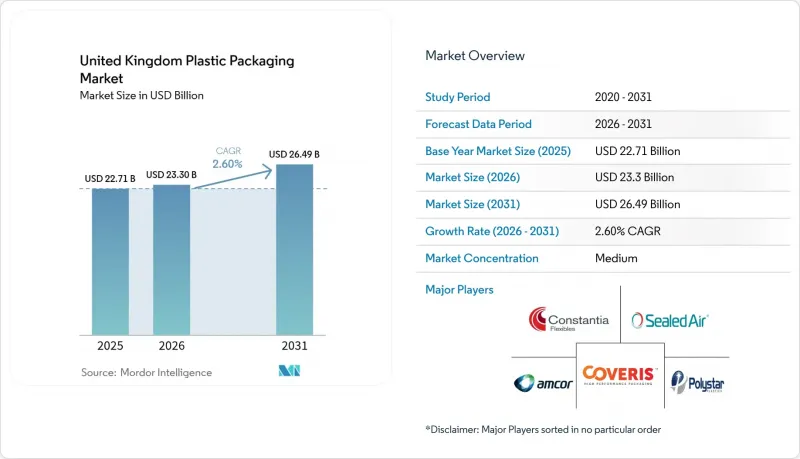
據 Mordor Intelligence 稱,英國塑膠包裝市場預計到 2026 年價值 233 億美元,高於 2025 年的 227.1 億美元,預計到 2031 年將達到 264.9 億美元。
預計 2026 年至 2031 年的複合年成長率為 2.6%。
本報告按材料類型(聚乙烯、聚丙烯等)、包裝類型(軟包裝、硬包裝等)、產品形狀(瓶/罐、托盤/容器等)、終端用戶行業(食品、飲料、醫藥/醫療等)和製造程序(擠出成型、射出成型等)進行分類。市場預測以美元計價。
英國塑膠包裝市場的趨勢與洞察
對輕便包裝的需求不斷成長。
都市區消費者優先考慮便攜性和份量控制,這使得與傳統硬質包裝相比,材料用量減少了15-20%。單份包裝正從零食擴展到藥品領域,有助於提高用藥依從性,同時降低污染風險。 2025年9月,Coveris推出了MonoFlexBP系列可重複密封托盤,該系列產品兼具易開啟性和可回收性(作為生活垃圾)。人口老化和日益繁忙的生活方式推動了對易用性包裝的持續需求,即使這意味著犧牲大規模生產的效率,這也支撐了包裝加工商利潤率的穩步成長,他們致力於最佳化更輕薄的包裝。
電子商務防護包裝的成長
線上訂單包裝在多次配送過程中會承受高強度的壓縮、穿刺和跌落衝擊。特製薄膜和填充系統兼顧強度和體積重量的降低,從而減少運輸成本和損壞索賠。 TekniPlex Healthcare 於 2025 年 3 月擴大產能,旨在滿足溫控防篡改藥品運輸的需求,凸顯了各個分銷管道的具體要求。物流最佳化設計能夠直接提升顧客滿意度與再購率。
樹脂價格波動與能源成本相關
由於乙烯和丙烯的生產成本約佔裂解裝置營運成本的60-70%,天然氣投入量的波動會對轉化裝置的獲利能力產生負面影響。英國塑膠聯合會報告稱,2025年7月聚乙烯(PE)和聚丙烯(PP)價格出現顯著波動,迫使買家採取避險措施並縮短合約期限,從而增加了管理負擔。進口商也面臨歐元和美元兌英鎊匯率波動的雙重風險,這使得成本預測和庫存策略更加複雜。
細分市場分析
2025年,低密度聚乙烯(LDPE)、線性低密度聚乙烯(LLDPE)和高密度聚乙烯(HDPE)等聚乙烯產品在英國塑膠包裝市場將維持38.74%的佔有率,這得益於其易於加工成薄膜且成本績效。聚對苯二甲酸乙二醇酯(PET)預計將以3.41%的複合年成長率成長,主要受輕質飲料容器和食品蒸餾PET(rPET)的努力。彩色聚丙烯的回收進展緩慢,限制了銷售量成長。雖然由於人們對一次性產品的批評日益增多,聚苯乙烯的使用量正在下降,但工程樹脂和新興生物聚合物佔據了特定的細分市場,在這些市場中,更優的功能性使其更高的成本也物有所值。
強制性再生材料含量要求正在推動聚烯技術的進步,例如添加除臭劑和相容劑,以提高消費後再生材料的混合品質。 2025年4月,Inovia Films推出了一款不含PVC的塗佈劑,可在保護對氧氣敏感的食品的同時,解決鹵素污染問題。從長遠來看,英國塑膠包裝市場的材料組合將反映監管風險、循環經濟合規性和特定應用性能要求之間的權衡。
預計到2025年,軟性包裝解決方案將佔銷售額的55.32%,並在2031年之前維持3.71%的複合年成長率。與同等規格的硬質包裝相比,單件自動成型密封包裝袋可減少高達70%的材料用量,進而降低運輸過程中的排放氣體和廢棄物處理成本。 Coveris公司於2025年8月推出的玉米餅的「MonoFlex Thermoform」包裝,將單一材料軟性包裝市場拓展至先前由硬托盤主導的領域。
硬質包裝在碳酸飲料、香水和高濃度化學品等需要自立穩定性和防篡改性能的領域仍然發揮著至關重要的作用,但掩埋稅和生產者延伸責任制約(EPR)費用限制了其成長。隨著多層薄膜回收技術的成熟,預計軟包裝將逐步滲透到化妝品和家用清潔劑行業,加速英國塑膠包裝市場向更高效的供應鏈轉型。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對輕鬆易用的包裝的需求日益成長。
- 電子商務防護包裝材料市場成長。
- 在30%的稅收優惠政策下,再生塑膠的推廣應用。
- 擴大化學回收的處理能力
- 英國的塑膠包裝稅加快了實施進程。
- 用於家庭垃圾收集的單材料高阻隔薄膜
- 市場限制因素
- 樹脂價格波動與能源成本相關
- 一次性塑膠製品的相關規定
- 零售商開展的鼓勵補充裝和重複使用項目的試點計劃正在減少原生包裝。
- 人們對微塑膠的強烈抵制正在影響再生材料的使用。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 依材料類型
- 聚乙烯(PE)
- 聚丙烯(PP)
- 聚對苯二甲酸乙二醇酯(PET)
- 聚苯乙烯(EPS)
- 其他類型的材料
- 按包裝類型
- 軟質塑膠包裝
- 硬質塑膠包裝
- 按產品形狀
- 瓶子罐
- 托盤和容器
- 小袋
- 包包
- 薄膜包裝
- 其他產品形狀
- 按最終用戶行業分類
- 食物
- 飲料
- 藥品和醫療保健
- 化妝品和個人護理
- 產業
- 其他終端用戶產業
- 透過製造程序
- 擠出成型
- 射出成型
- 吹塑成型
- 熱成型
- 其他製造程序
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Sealed Air Corporation
- Coveris Holdings SA
- Constantia Flexibles GmbH
- ALPLA Werke Alwin Lehner GmbH and Co KG
- Polystar Plastics Ltd
- Coda Plastics Ltd
- Charpak Ltd
- Wipak UK Ltd
- Sonoco Products Company
- Tyler Packaging Ltd(Macfarlane Group plc)
- National Flexible Ltd
- Clifton Packaging Group Ltd
- Greiner Packaging International GmbH
- Klockner Pentaplast Ltd
- International Paper Company
- Mondi plc
- Plastipak Packaging Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom plastic packaging market size in 2026 is estimated at USD 23.3 billion, growing from 2025 value of USD 22.71 billion with 2031 projections showing USD 26.49 billion, growing at 2.6% CAGR over 2026-2031.
This report is Segmented by Material Type (Polyethylene, Polypropylene, and More), Packaging Type (Flexible, and Rigid), Product Form (Bottles and Jars, Trays and Containers, and More), End-User Industry (Food, Beverage, Pharmaceuticals and Healthcare, and More), Manufacturing Process (Extrusion, Injection Molding, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Plastic Packaging Market Trends and Insights
Rising Demand for Lightweight Convenience Formats
Urban consumers prioritize portability and portion control, encouraging 15-20% material reductions versus legacy rigid packs. Single-dose formats extend from snacks to pharmaceuticals, lowering contamination risk while boosting adherence. Coveris introduced its MonoFlexBP resealable tray line in September 2025, merging easy-open functionality with curbside recyclability. Aging populations and busier lifestyles sustain demand for formats that trade bulk economics for usability, supporting steady margin expansion for converters that optimize downgauging.
Growth in E-commerce Protective Packaging
Online order volumes are subject packs to high compression, puncture, and drop forces across multiple shipping cycles. Engineered films and void-fill systems balance strength with dimensional-weight savings, cutting freight costs and damage claims. TekniPlex Healthcare's March 2025 capacity boost targets temperature-controlled and tamper-evident pharma shipments, underscoring channel-specific needs. Logistics-optimized designs translate directly into customer satisfaction metrics and repeat-purchase propensity.
Volatile Resin Prices Linked to Energy Costs
Ethylene and propylene production accounts for roughly 60-70% of cracker operating costs, so swings in natural-gas inputs distort converter margins. The British Plastics Federation recorded pronounced PE and PP price turbulence in July 2025, forcing buyers to adopt hedging tools and shorter contracts that raise administrative burden. Importers face dual exposure to euro and U.S.-dollar swings against sterling, complicating cost forecasting and inventory strategies.
Other drivers and restraints analyzed in the detailed report include:
- Uptake of Recycled-Content Plastics Under 30% Tax
- Chemical Recycling Capacity Scale-Up
- Single-Use Plastics Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene, spanning LDPE, LLDPE, and HDPE grades, retained 38.74 of % United Kingdom plastic packaging market share in 2025 because of processing ease and cost-performance balance in films. Polyethylene terephthalate is on course for a 3.41% CAGR with beverage lightweighting and ready-meal trays fueling demand. Converters value PET's clarity and gas barrier, paying the premium for thinner walls and hotter-fill tolerance. Mechanical recycling rates favor clear PET, catalyzing brand commitments to food-grade rPET integration. Polypropylene's colored variants lag recycling advances, limiting volume growth. Polystyrene use wanes under disposability scrutiny, while engineered resins and emerging biopolymers occupy specialized niches where functional gains justify higher costs.
Recycled-content mandates push polyolefin advancements such as odor-removal additives and compatibilizers that elevate post-consumer blend quality. Innovia Films debuted a PVC-free coater in April 2025 to eliminate halogen concerns while protecting oxygen-sensitive foods. Long term, material portfolios will reflect a disciplined trade-off between regulatory risk, circularity credentials, and application-specific performance needs within the United Kingdom plastic packaging market.
Flexible solutions delivered 55.32% revenue in 2025 and are projected to achieve a 3.71% CAGR to 2031. A single auto-form seal pouch can cut material use by up to 70% versus a comparable rigid option, reducing freight emissions and waste-handling charges. Coveris's August 2025 MonoFlex Thermoform pack for tortillas extends mono-material flexibles into categories once dominated by rigid trays.
Rigid containers remain relevant for carbonated beverages, fragrances, and heavy-duty chemicals requiring stand-up stability and tamper resistance, yet landfill levies and Extended Producer Responsibility fees constrain growth. As multilayer film recycling technologies mature, flexible adoption is expected to permeate cosmetics and household cleaners, accelerating the United Kingdom plastic packaging market transition toward leaner supply chains.
Complete Report Scope:
- By Material Type
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene and EPS
- Other Material Types
- By Packaging Type
- Flexible Plastic Packaging
- Rigid Plastic Packaging
- By Product Form
- Bottles and Jars
- Trays and Containers
- Pouches and Sachets
- Bags and Sacks
- Films and Wraps
- Other Product Forms
- By End-User Industry
- Food
- Beverage
- Pharmaceuticals and Healthcare
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
- By Manufacturing Process
- Extrusion
- Injection Molding
- Blow Molding
- Thermoforming
- Other Manufacturing Processes
List of Companies Covered in this Report:
- Amcor plc
- Sealed Air Corporation
- Coveris Holdings SA
- Constantia Flexibles GmbH
- ALPLA Werke Alwin Lehner GmbH and Co KG
- Polystar Plastics Ltd
- Coda Plastics Ltd
- Charpak Ltd
- Wipak UK Ltd
- Sonoco Products Company
- Tyler Packaging Ltd (Macfarlane Group plc)
- National Flexible Ltd
- Clifton Packaging Group Ltd
- Greiner Packaging International GmbH
- Klockner Pentaplast Ltd
- International Paper Company
- Mondi plc
- Plastipak Packaging Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for lightweight convenience formats
- 4.2.2 Growth in e-commerce protective packaging
- 4.2.3 Uptake of recycled-content plastics under 30 % tax
- 4.2.4 Chemical-recycling capacity scale-up
- 4.2.5 UK Plastics Packaging Tax accelerating adoption
- 4.2.6 Mono-material high-barrier films for curbside recycling
- 4.3 Market Restraints
- 4.3.1 Volatile resin prices linked to energy costs
- 4.3.2 Single-use plastics regulations
- 4.3.3 Retailer refill/re-use pilots reducing primary packs
- 4.3.4 Micro-plastics backlash impacting recycled feedstock
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porters Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polypropylene (PP)
- 5.1.3 Polyethylene Terephthalate (PET)
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Material Types
- 5.2 By Packaging Type
- 5.2.1 Flexible Plastic Packaging
- 5.2.2 Rigid Plastic Packaging
- 5.3 By Product Form
- 5.3.1 Bottles and Jars
- 5.3.2 Trays and Containers
- 5.3.3 Pouches and Sachets
- 5.3.4 Bags and Sacks
- 5.3.5 Films and Wraps
- 5.3.6 Other Product Forms
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceuticals and Healthcare
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Manufacturing Process
- 5.5.1 Extrusion
- 5.5.2 Injection Molding
- 5.5.3 Blow Molding
- 5.5.4 Thermoforming
- 5.5.5 Other Manufacturing Processes
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amcor plc
- 6.4.2 Sealed Air Corporation
- 6.4.3 Coveris Holdings SA
- 6.4.4 Constantia Flexibles GmbH
- 6.4.5 ALPLA Werke Alwin Lehner GmbH and Co KG
- 6.4.6 Polystar Plastics Ltd
- 6.4.7 Coda Plastics Ltd
- 6.4.8 Charpak Ltd
- 6.4.9 Wipak UK Ltd
- 6.4.10 Sonoco Products Company
- 6.4.11 Tyler Packaging Ltd (Macfarlane Group plc)
- 6.4.12 National Flexible Ltd
- 6.4.13 Clifton Packaging Group Ltd
- 6.4.14 Greiner Packaging International GmbH
- 6.4.15 Klockner Pentaplast Ltd
- 6.4.16 International Paper Company
- 6.4.17 Mondi plc
- 6.4.18 Plastipak Packaging Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026年全球聚苯乙烯包裝市場報告
 全球一次性塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 2035 年前食品飲料塑膠包裝市場分析與預測:類型、產品類型、技術、應用、材料類型、製造流程、最終用戶、功能中東和非洲塑膠包裝市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)亞太地區塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)全球塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)印度塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)日本塑膠包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印尼塑膠包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)