


 |
市場調查報告書
商品編碼
2121415
印度塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)India Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
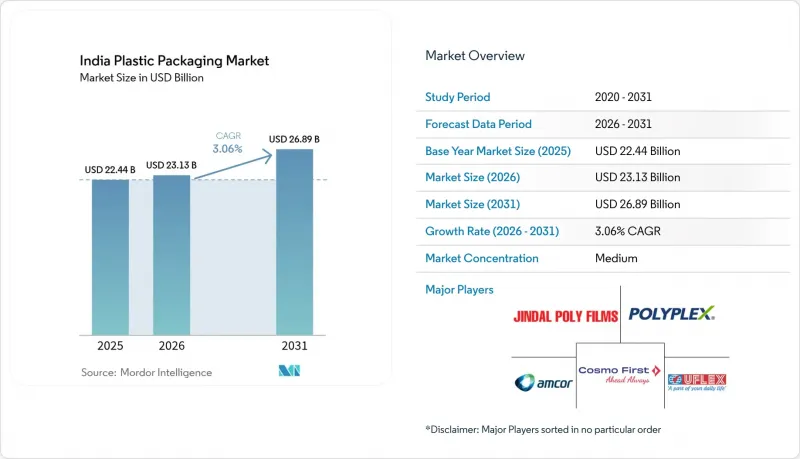
據 Mordor Intelligence 稱,2025 年印度塑膠包裝市場價值為 224.4 億美元,預計到 2031 年將達到 268.9 億美元,而 2026 年為 231.3 億美元,預測期(2026-2031 年)的複合年成長率為 3.06%。
[1] 印度環境、森林和氣候變遷部,《生產者延伸責任制(EPR)指南》,moef.gov.in。隨著2024年生產者延伸責任制(EPR)法規的實施,廢棄物處理責任現已轉移至品牌所有者,市場需求也從單純追求數量轉向追求更高附加價值的產品形式。這迫使加工商轉向使用含有再生材料的樹脂以及利潤率更高的阻隔技術。本報告按材料類型(聚乙烯、聚丙烯等)、包裝類型(軟包裝、硬包裝)、產品形式(瓶、罐、托盤、容器等)、終端用戶行業(食品、飲料等)和製造程序(擠出、射出成型、吹塑成型、熱成型等)進行分類。市場預測以美元計價。
印度塑膠包裝市場趨勢與洞察
電子商務和快速貿易的物流蓬勃發展
2024年,主要大都會圈15分鐘送達平台的包裹量增加了300%,推動了對防篡改包裝袋的需求,這種包裝袋即使經過多次搬運也能保持密封性。擁有自動化包裝袋生產線的加工商實現了每分鐘約200個包裝的生產週期,縮短了每天補貨三次的食品聚合商的前置作業時間。大型快速消費品公司正在透過將灌裝業務轉移到更靠近需求點的地方來應對這一需求。例如,一家大型飲料製造商將於2025年在阿薩姆邦運作一家工廠,這將使平均運輸距離縮短至450公里,並將二次包裝成本降低14%。這種轉變推動了對能夠承受最後一公里摩托車配送中常見的震動和溫度波動的超薄拉伸膜的需求。區域倉儲網路現在也指定使用水蒸氣透過率低於10克/平方公尺/天的防潮膜,以防止季風冷凝造成的損壞。因此,在印度塑膠包裝市場,小型阻隔性解決方案的訂單迅速增加,這些解決方案的價格高於傳統的 SKU,但不會降低填充率的經濟效益。
對輕便靈活包裝的需求
物流公司將燃油額外費用轉嫁給消費者,獎勵減輕包裝重量。因此,各大品牌紛紛從硬質包裝轉向單層複合材料,這種包裝重量減輕了40%,同時仍能滿足跌落測試標準。阻隔塗層基材如今已成功將氧氣透過率降低至1 cc/m²/天以下,使得常溫食品無需冷鏈即可長途運輸。隨著軟包裝袋取代複合罐用於粉狀飲料,加工商每100克包裝的樹脂用量最多可減少30%,從而減輕了生產者責任召回(EPR)費用的負擔,該費用與產品銷量成正比。過去用於乳製品容器的熱成型生產線現在正被改造用於生產模塑-填充-密封(FFS)杯的杯蓋,在新推出的高階優格產品中佔據了主導市場佔有率。雙向拉伸聚乙烯(BHI)薄膜在印度塑膠包裝市場也越來越受歡迎。此舉旨在實現所有合格單一材料回收流程的聚乙烯複合材料的回收。改造複合設備所需的資本投資平均每條生產線200萬美元,但中小企業正透過組成合作社,在政府支持的塑膠產業園內共用後加工設備,從而降低風險。
樹脂價格波動
2024年,原油價格波動導致聚乙烯(PE)和聚丙烯(PP)的合約價格上漲高達30%,但簽訂六個月供貨合約的加工商只能按季度調整價格,這使得他們的息稅折舊攤銷EBITDA獲利率)下降了近4個百分點。軟質塑膠加工商的庫存平均僅相當於20天的產量。價格的急劇上漲進一步加劇了營運資金融資的壓力,而營運資金融資的年利率已經高達11%。聚合物期貨避險仍處於起步階段,流動性不足使得有效避險超過月交易量5%的交易量變得困難。因此,在印度的塑膠包裝市場,合作社正在協商合作協定,以獲得批量採購折扣,並共用煉油廠儲罐區附近的倉儲空間。政府計劃對石化行業實施「生產連結獎勵計畫(PLI)」計劃,承諾給予關稅豁免,但產能的增加要到 2028 年或更晚才能實現,這使得短期前景容易受到全球原料價格波動的影響。
細分市場分析
預計到2025年,聚乙烯將在印度塑膠包裝市場佔據最大佔有率,達到37.78%。這主要得益於其具有競爭力的樹脂價格以及與全國範圍內已部署的吹膜和射出成型線的兼容性。聚乙烯在購物袋、農用薄膜和清潔劑包裝袋等大批量生產產品中的應用,支撐了產量,並使主要工廠的平均運轉率保持在80%以上。此外,國內生產商提供的靈活原料組合也有利於聚乙烯的生產,即使在全球供應中斷的情況下,也能確保單體的穩定供應,從而為本地加工商在與進口產品進行價格比較時提供了一個穩定的基準。同時,受品牌商對即飲飲料和調味品透明度、光澤度和優異阻隔性的需求推動,聚對苯二甲酸乙二醇酯(PET)預計到2031年將以4.18%的複合年成長率成長。 PET 的可回收性符合生產者延伸責任制 (EPR) 的目標,透過幾個正在進行的「瓶到瓶」項目,我們的目標是到 2027 年將印度食品級 rPET 薄片的市場規模擴大到每年 100 萬噸以上。
儘管PET市場成長迅速,但其過濾過濾製程仍面臨瓶頸,導致其資本密集度較高。由於PET生產需要固體縮聚和高壓注射拉伸工藝,因此其一體化生產線的成本比同類PE生產線高出20-25%。聚丙烯(PP)在一些需要剛性和耐熱性的特殊應用領域需求旺盛,例如微波爐適用托盤和藥蓋,但由於國內PP產能主要集中在紡織和汽車級產品,供應仍然緊張。聚苯乙烯(PS)和發泡聚苯乙烯(EPS)由於各邦政府禁止使用發泡餐具而逐漸減少,但在需要緩衝保護的家電內襯領域仍然存在需求,且人們對可回收性的擔憂超過了其面臨的挑戰。新興生物塑膠,例如在北方邦一項3.42億美元的待開發區項目支持下生產的生質塑膠(PLA),在可堆肥零食包裝方面具有潛力,但其廣泛應用取決於市政堆肥基礎設施能否從試點階段擴展到更大規模。隨著監管機構發布統一各種聚合物再生材料含量標準的指導方針草案,加工商正在尋求開發能夠平衡成本、性能和再生材料含量分配的多材料組合,這將在未來十年重塑印度塑膠包裝產業。
預計到2025年,軟包裝將佔據印度塑膠包裝市場54.05%的佔有率,充分展現了薄膜包裝系統的顯著經濟優勢。與硬質包裝相比,薄膜包裝可降低單位重量包裝的運輸成本30%。採用EVOH或AlOx塗層的多層複合材料可延長香氣阻隔層的使用壽命,並實現無需冷藏車的本地配送。致力於揭露碳足跡的品牌商更傾向於選擇軟包裝袋,因為生命週期評估(LCA)模型估計,與玻璃瓶相比,每公升軟包裝袋的溫室氣體排放量可減少60%。隨著快速消費的蓬勃發展,消費者對價格適宜衝動購買的一次性軟包裝袋的需求不斷成長,預計到2031年,軟包裝市場將以4.6%的複合年成長率成長。推動軟包裝市場主導的另一個因素是生產線的快速換型。無溶劑數位複合製程可在兩小時內固化,使加工商能夠應對區域獨家口味上市帶來的SKU激增。
硬質塑膠包裝在化妝品行業中仍然扮演著至關重要的角色,因為產品在螢幕上的呈現效果和觸感會顯著影響其高階定價。用於個人保健產品的擠出吹塑成型聚乙烯(HDPE)瓶現在採用近紅外線可分揀母粒,這不僅有利於下游回收利用,也使硬質包裝符合循環經濟的目標。射出拉伸吹塑成型成型聚對苯二甲酸乙二醇酯(PET)罐在營養保健品領域正不斷擴大市場佔有率,這得益於其38毫米的瓶頸設計,該設計可容納感應密封襯墊並保護易揮發成分。然而,隨著歐盟對瓶蓋的約束性要求影響全球設計,瓶蓋和封蓋用樹脂的消耗量趨於穩定,輕量化鉸鏈橋正在被廣泛應用。因此,印度塑膠包裝市場存在著一種微妙的共生關係。在電子商務的推動下,軟包裝正在成長,而硬質容器則在注重美觀和可重複使用的高階細分市場中保持著穩固的地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務的擴張和快速物流的快速發展。
- 對輕巧且高度柔軟性的規格的需求
- 再生塑膠的普及
- 促進與EPR相關的rPET/rHDPE在地化生產的運動
- 中小企業的人工智慧加工生產線
- 單劑量藥物包裝袋的需求正在激增。
- 市場限制因素
- 樹脂價格波動
- 一次性塑膠製品的相關法規與禁令
- 缺乏食品級PCR基礎設施
- 對依賴進口的高階薄膜製造設備進行資本投資。
- 監理情勢
- 技術展望
- 投資分析
- 產業價值鏈分析
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 材料類型
- 聚乙烯(PE)
- 聚丙烯(PP)
- 聚對苯二甲酸乙二醇酯(PET)
- 聚苯乙烯和EPS
- 其他材料類型
- 按包裝類型
- 軟塑膠包裝
- 硬質塑膠包裝
- 按產品形式
- 瓶子和罐子
- 托盤和容器
- 小袋和小袋
- 包包
- 薄膜和包裝
- 其他產品形式
- 按最終用戶行業分類
- 食物
- 飲料
- 藥品和醫療保健
- 化妝品和個人護理
- 產業
- 其他終端用戶產業
- 透過製造程序
- 擠壓
- 射出成型
- 吹塑成型
- 熱成型
- 其他製造程序
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- UFlex Limited
- Jindal Poly Films Limited
- Cosmo First Limited
- Polyplex Corporation Limited
- Manjushree Technopack Limited
- Hitech Corporation Limited
- TCPL Packaging Limited
- AptarGroup, Inc.
- Constantia Flexibles Group GmbH
- Mondi plc
- Sealed Air Corporation
- Huhtamaki India Limited
- Mold-Tek Packaging Limited
- ALPLA India Private Limited
- Garware Hi-Tech Films Limited
- Ester Industries Limited
- Chemco Plastic Industries Pvt. Ltd.
- Essel Propack Limited(EPL Ltd.)
- Sonoco Products Company
第7章 市場機會與未來展望
According to Mordor Intelligence, the India plastic packaging market size was valued at USD 22.44 billion in 2025 and estimated to grow from USD 23.13 billion in 2026 to reach USD 26.89 billion by 2031, at a CAGR of 3.06% during the forecast period (2026-2031).
[1] Ministry of Environment, Forest and Climate Change, "Extended Producer Responsibility Guidelines," moef.gov.in Demand pivots from pure volume to value-added formats as Extended Producer Responsibility (EPR) rules enacted in 2024 place the onus of post-consumer waste on brand owners, pushing converters toward recycled-content resins and higher-margin barrier technologies. This report is Segmented by Material Type (Polyethylene, Polypropylene, and More), Packaging Type (Flexible, Rigid), Product Form (Bottles and Jars, Trays and Containers, and More), End-User Industry (Food, Beverage, and More), Manufacturing Process (Extrusion, Injection Molding, Blow Molding, Thermoforming, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Plastic Packaging Market Trends and Insights
Growing e-commerce and quick-commerce logistics boom
Package volumes from 15-minute delivery platforms grew 300% in major metros during 2024, requiring tamper-proof pouches that preserve integrity across multiple handling points. Converters that deploy automated pouch lines achieve cycle times near 200 packs per minute, shortening lead times for grocery aggregators that refresh inventory thrice daily. FMCG majors have responded by relocating filling operations closer to demand centers; for example, a leading beverage maker commissioned a plant in Assam in 2025, trimming average transit distance to 450 km and cutting secondary packaging spend by 14%. This shift concentrates demand for low-gauge stretch films that withstand vibration and thermal fluctuations common in last-mile two-wheeler delivery. Regional warehousing networks now specify moisture-barrier films with WVTR below 10 g / m2 / day to avoid condensation damage during the monsoon. The India plastic packaging market, therefore, receives a rapid influx of orders for small-format, high-barrier solutions that command price premiums over legacy SKUs without eroding fill-rate economics.
Demand for lightweight flexible formats
Logistics providers levy fuel-surcharge pass-throughs that incentivize weight reduction, steering brands away from rigid packs toward mono-material laminates that are 40% lighter yet meet drop-test thresholds. Barrier-coated substrates now achieve oxygen transmission rates below 1 cc / m2 / day, allowing shelf-stable food to travel farther without a cold chain. As flexible pouches replace composite cans in powdered beverage mixes, converters save up to 30% resin weight per 100 g serving, easing EPR fee liabilities that scale with grammage. Thermoforming lines that once served dairy tubs now pivot to form-fill-seal cup lidding, capturing an outsized share of premium yogurt launches. The India plastic packaging market also witnesses bi-axially oriented PE films gaining traction because they allow all-PE laminates that qualify for single-material recycling streams. Capital outlay for retrofitting lamination equipment averages USD 2 million per line; SMEs mitigate risk by forming cooperatives that share finishing assets inside government-backed plastic parks.
Resin price volatility
Crude swings drove PE and PP contract prices up to 30% during 2024, yet converters locked into six-month supply agreements could only reprice quarterly, compressing EBITDA margins by nearly 4 percentage points. Flexible converters carry inventory covering just 20 production days on average; sudden price hikes strain working capital facilities that already carry 11% interest. Hedging via polymer futures remains nascent, with low liquidity restricting meaningful coverage beyond 5% of monthly volume. The India plastic packaging market, therefore, sees cooperatives negotiating pooled contracts to gain bulk discounts while sharing storage depots adjacent to refinery tank farms. Government plans for a Production-Linked Incentive (PLI) scheme in petrochemicals promise duty waivers, but capacity additions will not materialize until 2028, leaving the near-term outlook vulnerable to global feedstock volatility.
Other drivers and restraints analyzed in the detailed report include:
- Uptake of recycled-content plastics
- EPR-linked rPET / rHDPE localization push
- Single-use-plastic regulatory bans
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene commands the highest 37.78% share of the India plastic packaging market in 2025, underpinned by competitive resin pricing and compatibility with blown-film and injection-molding lines already installed nationwide. Its role in high-volume SKUs such as shopping bags, agricultural sheets, and detergent pouches sustains throughput that keeps average operating rates above 80% in major plants. PE also benefits from the flexible feedstock slate of domestic crackers, which maintains a steady monomer supply even during global disruptions, giving local converters stable price benchmarks against imported parity levels. However, polyethylene terephthalate is projected to grow at a 4.18% CAGR through 2031 as brands seek clarity, gloss, and superior barrier credentials for ready-to-drink beverages and condiments. PET's recyclability advantage dovetails with EPR targets, and multiple bottle-to-bottle projects under implementation aim to lift the India plastic packaging market size for food-grade rPET flakes to more than 1 million TPA by 2027.
In spite of its growth, PET faces melt-filtration bottlenecks that raise capital intensity; integrated PET lines cost 20-25% more than equivalent PE lines due to solid-state polycondensation and higher-pressure injection stretches. Polypropylene fills specialized slots where rigidity and heat resistance matter, such as microwaveable trays and pharma caps, but supply remains tight because domestic PP capacities favor fiber and automotive grades. Polystyrene and EPS gradually decline owing to state bans on foamed tableware, though niche demand persists in appliance liners where cushioning outweighs recyclability concerns. Emerging bioplastics like PLA, backed by a USD 342 million greenfield project in Uttar Pradesh, hold potential in compostable snack packs but remain contingent on municipal composting infrastructure scaling beyond pilot units. As regulators publish draft norms to equate recycled-content thresholds across polymers, converters anticipate a multi-material portfolio balancing cost, performance, and recycle-content quotas, reshaping the India plastic packaging industry over the next decade.
Flexible formats account for 54.05% share of the India plastic packaging market size in 2025, demonstrating the clear economic edge of film-based systems that deliver 30% lower transportation cost per unit of packed weight than rigid alternatives. Multi-layer laminates engineered with EVOH or AlOx coatings extend aroma barrier life, enabling rural distribution without refrigerated trucks. Brand owners pursuing carbon-footprint disclosures favor flexible pouches because life-cycle-assessment models credit them with 60% fewer greenhouse-gas emissions per liter of beverage compared with glass bottles. Flexible packaging is forecast to expand at a 4.6% CAGR through 2031 as quick-commerce spurts heighten demand for single-serve sachets that meet impulse-buy price points. Flexible's dominance also stems from rapid line changeovers; digital solventless lamination cures in under two hours, allowing converters to manage SKU proliferation from regional flavor launches.
Rigid plastic packaging retains relevance in cosmetics where shelf presence and tactile cues command premium price points. Extrusion-blow-molded HDPE bottles for personal-care products now feature near-infrared sortable masterbatches that ease downstream recycling, aligning rigid formats with circularity goals. Injection-stretch-blown PET jars gain share in nutraceuticals because 38-mm neck finishes accommodate induction-seal liners, preserving volatile ingredients. However, cap-and-closure resin consumption plateaus as tethered-cap EU requirements influence design globally, prompting material light-weighting of hinge bridges. The India plastic packaging market thus exhibits a nuanced co-existence: flexible growth rides on e-commerce cycles, while rigid solutions maintain foothold in premium niches that value aesthetics and reusability.
Complete Report Scope:
- By Material Type
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene and EPS
- Other Material Types
- By Packaging Type
- Flexible Plastic Packaging
- Rigid Plastic Packaging
- By Product Form
- Bottles and Jars
- Trays and Containers
- Pouches and Sachets
- Bags and Sacks
- Films and Wraps
- Other Product Forms
- By End-User Industry
- Food
- Beverage
- Pharmaceuticals and Healthcare
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
- By Manufacturing Process
- Extrusion
- Injection Molding
- Blow Molding
- Thermoforming
- Other Manufacturing Processes
List of Companies Covered in this Report:
- Amcor plc
- UFlex Limited
- Jindal Poly Films Limited
- Cosmo First Limited
- Polyplex Corporation Limited
- Manjushree Technopack Limited
- Hitech Corporation Limited
- TCPL Packaging Limited
- AptarGroup, Inc.
- Constantia Flexibles Group GmbH
- Mondi plc
- Sealed Air Corporation
- Huhtamaki India Limited
- Mold-Tek Packaging Limited
- ALPLA India Private Limited
- Garware Hi-Tech Films Limited
- Ester Industries Limited
- Chemco Plastic Industries Pvt. Ltd.
- Essel Propack Limited (EPL Ltd.)
- Sonoco Products Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing e-commerce and quick-commerce logistics boom
- 4.2.2 Demand for lightweight flexible formats
- 4.2.3 Uptake of recycled-content plastics
- 4.2.4 EPR-linked rPET/rHDPE localization push
- 4.2.5 AI-enabled converting lines for SMEs
- 4.2.6 Single-dose pharma pouch surge
- 4.3 Market Restraints
- 4.3.1 Resin price volatility
- 4.3.2 Single-use-plastic regulatory bans
- 4.3.3 Scarce food-grade PCR infrastructure
- 4.3.4 Import-dependent hi-end film machinery CAPEX
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Investment Analysis
- 4.7 Industry Value Chain Analysis
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polypropylene (PP)
- 5.1.3 Polyethylene Terephthalate (PET)
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Material Types
- 5.2 By Packaging Type
- 5.2.1 Flexible Plastic Packaging
- 5.2.2 Rigid Plastic Packaging
- 5.3 By Product Form
- 5.3.1 Bottles and Jars
- 5.3.2 Trays and Containers
- 5.3.3 Pouches and Sachets
- 5.3.4 Bags and Sacks
- 5.3.5 Films and Wraps
- 5.3.6 Other Product Forms
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceuticals and Healthcare
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Manufacturing Process
- 5.5.1 Extrusion
- 5.5.2 Injection Molding
- 5.5.3 Blow Molding
- 5.5.4 Thermoforming
- 5.5.5 Other Manufacturing Processes
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 UFlex Limited
- 6.4.3 Jindal Poly Films Limited
- 6.4.4 Cosmo First Limited
- 6.4.5 Polyplex Corporation Limited
- 6.4.6 Manjushree Technopack Limited
- 6.4.7 Hitech Corporation Limited
- 6.4.8 TCPL Packaging Limited
- 6.4.9 AptarGroup, Inc.
- 6.4.10 Constantia Flexibles Group GmbH
- 6.4.11 Mondi plc
- 6.4.12 Sealed Air Corporation
- 6.4.13 Huhtamaki India Limited
- 6.4.14 Mold-Tek Packaging Limited
- 6.4.15 ALPLA India Private Limited
- 6.4.16 Garware Hi-Tech Films Limited
- 6.4.17 Ester Industries Limited
- 6.4.18 Chemco Plastic Industries Pvt. Ltd.
- 6.4.19 Essel Propack Limited (EPL Ltd.)
- 6.4.20 Sonoco Products Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 2026年全球聚苯乙烯包裝市場報告
 全球一次性塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 2035 年前食品飲料塑膠包裝市場分析與預測:類型、產品類型、技術、應用、材料類型、製造流程、最終用戶、功能中東和非洲塑膠包裝市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)亞太地區塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)全球塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)日本塑膠包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國塑膠包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)英國塑膠包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼塑膠包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)