


 |
市場調查報告書
商品編碼
2125506
歐洲物流自動化:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Intralogistics Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,歐洲物流自動化市場規模將從 2025 年的 68.4 億美元成長到 2026 年的 77.2 億美元,到 2031 年達到 128.9 億美元,2026 年至 2031 年的複合年成長率為 10.79%。
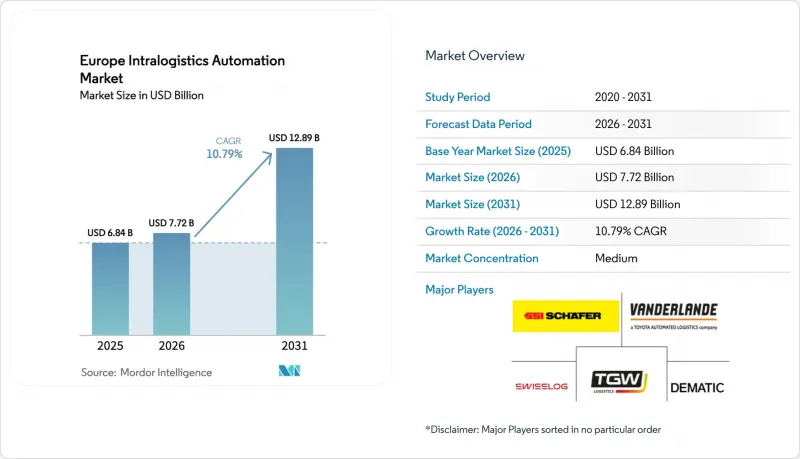
本報告按產品類型(移動機器人、自動化分類系統及其他)、終端用戶行業(機場、郵政和小包裹服務、一般製造業、汽車行業及其他)、組件(硬體、軟體、服務)、功能(存儲、揀貨和產品檢索及其他)以及地區(英國、德國及其他)進行細分。市場預測以美元計價。
歐洲物流自動化市場趨勢與洞察
電子商務的快速成長以及履約。
預計到2025年,西歐線上零售額將佔總銷售額的18.3%,將加劇高需求區域方圓20公里內的庫存競爭。微型倉配中心採用「產品到人」的穿梭系統,將訂單處理時間縮短至90秒,儲存密度提高四倍,使其能夠在一個5000平方米的「暗庫」中每天處理1萬個訂單。家樂福等食品零售巨頭已在人口密集的都市區部署了立方體形狀的儲存網格,並利用有限的占地面積作為最後一公里配送的集散地。高速分揀機每小時可處理多達5萬個小包裹,鑑於2025年跨境小包裹量預計將年增23%,這一產能至關重要。全通路工作流程需要即時分類演算法,而這只有透過自動化編配平台才能大規模執行。
歐盟27國勞動力短缺和工資上漲
結構性問題預計到2025年將導致210萬名物流工人缺口,使得19個成員國的每位全職員工(FTE)的總人事費用超過3.5萬歐元(3.955萬美元)。光是在德國,預計到2025年第四季就將出現38.7萬個工作崗位的缺口。引入自主機器人將使一名工人能夠管理8至12個工作站,從而有效地將生產力提高四倍。隨著薪資趨同消除了東歐的勞動成本優勢,一家波蘭第三方物流公司已於2025年開始測試和營運其機器人車隊。歐盟委員會預測,到2030年,物流業的勞動力供應將以每年0.3%的速度萎縮,這將進一步增加對自動化的需求。
大筆資本投入和較長的投資回收期
一個佔地 3 萬平方公尺的物流中心的承包立體倉庫 (AS/RS) 專案成本在 800 萬至 1,200 萬歐元(約 904 萬美元至 1,356 萬美元)之間,投資回收期為 4.5 至 6 年。中小企業佔歐洲倉儲容量的 64%,但往往難以獲得利率低於 3% 的貸款,儘管人事費用大幅降低,他們仍然會推遲採用自動化系統。機器人即服務 (RaaS) 的租賃價格為每台機器人每月 2500 至 4000 歐元(約 2825 至 4520 美元),降低了准入門檻,但仍需要簽訂三年合約並對設施維修。歐洲投資銀行 (EIB) 2025 年的一項調查發現,41% 的營運商將「需求不確定性」列為延遲採用自動化系統的原因。在南歐,分散的所有權結構會延遲董事會的批准,導致其採用率比北歐落後 30 到 40 個百分點。
細分市場分析
到了2025年,自動化倉庫系統(AS/RS)佔據歐洲物流自動化市場26.71%的佔有率。這反映了已建立的立方體儲存網格的普及,該網格可使都市區微型倉配中心的空間利用率提高四倍。然而,該細分市場屬於一次性使用,隨著處理產品類型的變化,其重新部署的柔軟性受到限制。預計到2031年,移動機器人將以11.91%的複合年成長率成長,超過歐洲整體物流自動化市場的成長速度。租賃模式支撐了這一成長,該模式允許營運商根據季節調整其設備規模,或在幾週內將設備在不同設施之間轉移。訂閱式定價簡化了董事會核准流程,並為業務擴張提供了資金保障。
移動機器人也受益於VDA 5050提供的互通性,這使得不同類型的機器人能夠共存,並最大限度地降低了曾經驅動企業投資於單一自動化立體倉庫(AS/RS)的供應商鎖定風險。在網路購物週高峰期,小包裹樞紐每小時需要處理5萬個小包裹,而自動化分類系統正逐漸成為主流。配備視覺引導抓手的碼垛單元可將包裹處理週期縮短至8秒。雖然自動化輸送機仍然是長距離內部輸送機的基礎,但運營商擴大將移動機器人與固定軌道相結合,創建靈活的“矩陣佈局”,這些佈局可以在一夜之間重新配置,以配合新產品的發布。
到2025年,零售、倉儲和配送將佔銷售額的29.43%,預計將以12.02%的複合年成長率引領成長,這主要得益於全通路企業致力於在人口密集的都市區實現兩小時送達。該領域依賴「單件揀貨」的特徵與移動機器人的優勢相契合,凸顯了其對歐洲物流自動化市場極為重要的貢獻。郵政和小包裹業者持續投資於交叉傳送帶分類機,這使得歐洲物流自動化市場規模在每個假期季節都得以擴大。
汽車零件供應商雖然只佔其銷售額的一小部分,但他們正在實施歐洲一些最先進的準時制生產系統,要求99.8%的準時交付率,而這僅靠人工貼標籤是無法實現的。食品飲料企業正在部署不銹鋼移動機器人來管理冷藏區域,雖然增加了單位成本,但降低了合規風險。一般製造業企業則傾向選擇投資報酬期不到四年的原料排序解決方案。同時,機場行李處理仍是一個高價值的細分市場,歐洲各大樞紐機場正競相將行李錯運率降低三分之一,以因應2028年即將到來的旅遊需求激增。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素對市場的影響
- 產業價值與價值鏈分析
- 市場促進因素
- 電子商務的快速成長以及履約。
- 歐盟27國勞動力短缺和工資上漲
- 人工智慧驅動的移動機器人和物聯網的快速發展。
- 透過部署 5G 和專用 LTE 實現即時編配。
- 歐盟綠色交易對低碳物流的獎勵
- 透過互通性標準(VDA 5050)實現多廠商整合
- 市場限制因素
- 大筆資本投入和較長的投資回收期
- 傳統IT與OT整合的複雜性
- 網路機器人面臨的網路安全威脅日益加劇
- 物流樞紐電力供應瓶頸
- 監理情勢
- 技術展望
- 波特五力分析
- 鄰近市場的影響分析
- 拉伸纏繞機市場
- 貨運電梯市場
第5章 市場規模與成長預測
- 依產品類型
- 移動機器人
- 自動化倉庫系統(AS/RS)
- 自動分類系統
- 碼垛和卸垛系統
- 自動輸送機
- 揀貨系統
- 按最終用戶行業分類
- 飛機場
- 郵件和小包裹
- 一般製造業
- 車
- 飲食
- 零售、倉儲和物流
- 其他
- 按組件
- 硬體
- 軟體
- 服務
- 按功能
- 貯存
- 揀貨和產品檢索
- 選擇和合併
- 包裝和托盤堆垛
- 運輸和配送
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Swisslog Holding AG
- TGW Logistics Group GmbH
- Vanderlande Industries BV
- SSI Schafer AG
- Dematic GmbH(KION Group)
- Daifuku Co., Ltd.
- Exotec SAS
- AutoStore ASA
- ABB Ltd.
- Honeywell International Inc.
- Interroll Holding AG
- Jungheinrich Aktiengesellschaft
- Kardex Holding AG
- BEUMER Group GmbH and Co. KG
- KNAPP AG
- KUKA Aktiengesellschaft
- Linde Material Handling GmbH
- Murata Machinery, Ltd.
- Ocado Group plc
- Toyota Industries Corporation
- Viastore Systems GmbH
- WITRON Logistik+Informatik GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe intralogistics automation market size is expected to increase from USD 6.84 billion in 2025 to USD 7.72 billion in 2026 and reach USD 12.89 billion by 2031, growing at a CAGR of 10.79% over 2026-2031.
This report is Segmented by Product Type (Mobile Robots, Automated Sorting Systems, and More), End-User Industry (Airport, Post and Parcel, General Manufacturing, Automotive, and More), Component (Hardware, Software, and Services), Function (Storage, Order Picking and Retrieval, and More), and Geography (United Kingdom, Germany, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Intralogistics Automation Market Trends and Insights
E-Commerce Boom And Omnichannel Fulfilment Pressure
Online retail penetration reached 18.3% of total Western European sales in 2025, intensifying the race to keep inventory within 20 kilometers of demand hotspots. Micro-fulfillment centers rely on goods-to-person shuttles that cut order cycle time to 90 seconds and raise storage density fourfold, enabling a single 5,000 m2 dark store to ship 10,000 daily orders. Grocery leaders such as Carrefour adopted cube-storage grids in dense urban nodes, freeing scarce floor space for last-mile staging. High-speed sorters now process up to 50,000 parcels per hour, a capability vital as cross-border parcel volumes grew 23% year-on-year in 2025. Omnichannel workflows require real-time slotting algorithms that only automated orchestration platforms can execute at scale.
Labour Shortages And Wage Inflation Across EU27
A structural shortfall of 2.1 million logistics workers in 2025 pushed fully loaded labor costs per FTE to over EUR 35,000 (USD 39,550) in 19 member states. Germany alone reported 387,000 vacancies in Q4 2025. Autonomous mobile robots allow one worker to supervise 8-12 stations, effectively quadrupling productivity. Wage convergence eroded Eastern Europe's labor arbitrage, prompting Polish 3PLs to pilot robot fleets in 2025. The European Commission projects logistics labor supply to contract 0.3% annually through 2030, widening the automation imperative.
High Capex And Long ROI Horizons
Turnkey AS/RS projects for a 30,000 m2 DC cost EUR 8-12 million (USD 9.04-13.56 million) and repay in 4.5-6 years. SMEs, which control 64% of European warehouse capacity, often lack access to sub-3% financing, delaying adoption despite strong labor-saving cases. Robotics-as-a-Service leases at EUR 2,500-4,000 (USD 2,825-4,520) per robot per month reduce barriers but still demand three-year commitments and facility retrofits. Forty-one percent of operators cited "uncertain demand" when deferring automation in the 2025 EIB survey. Southern Europe trails Northern peers by 30-40 percentage points in penetration as fragmented ownership structures slow board-level approvals.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Advances In AI-Powered Mobile Robotics And IoT
- 5G And Private-LTE Roll-Outs Enabling Real-Time Orchestration
- Legacy IT And OT Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automated storage and retrieval systems delivered 26.71% of Europe intralogistics automation market share in 2025, reflecting entrenched cube-storage grids that quadruple space efficiency in urban micro-fulfillment centers. Yet the segment's single-purpose nature limits redeployability when product profiles shift. Mobile robots are projected to surpass the overall Europe intralogistics automation market at an 11.91% CAGR through 2031, buoyed by lease-based models that let operators scale fleets seasonally and move assets between facilities in weeks. Subscription pricing simplifies board approvals and preserves capital for expansion initiatives.
Mobile robots also benefit from VDA 5050-driven interoperability, which allows heterogeneous fleets to coexist, minimizing the vendor-lock risk that once favored monolithic AS/RS investments. Automated sorting systems dominate parcel hubs that must process 50,000 parcels per hour during Cyber Week peaks, while palletizing cells with vision-guided grippers cut case cycle times to eight seconds. Although automated conveyors remain the backbone for long-haul internal transport, operators increasingly supplement fixed tracks with mobile robots to create flexible "matrix layouts" capable of overnight reconfiguration for new product launches.
Retail, warehousing, and distribution accounted for 29.43% of revenue in 2025 and will lead growth at a 12.02% CAGR, driven by omnichannel businesses striving for two-hour delivery in dense urban areas. The segment's dependence on piece-level picking aligns with mobile-robot advantages, reinforcing its outsized contribution to the Europe intralogistics automation market. Post-and-parcel operators continue to invest in cross-belt sorters that push Europe intralogistics automation market size upward each holiday season.
Automotive suppliers, while representing a smaller revenue slice, deploy some of the continent's most sophisticated just-in-sequence systems, demanding 99.8% on-time accuracy that manual tuggers cannot match. Food and beverage facilities add stainless-steel mobile robots to navigate chilled zones, raising unit-cost premiums but trimming compliance risk. General manufacturing favors raw-material sequencing solutions with sub-four-year paybacks, whereas airport baggage handling remains a high-value niche, as European hubs race to cut mishandled-bag rates by one-third ahead of the 2028 travel surge.
Complete Report Scope:
- By Product Type
- Mobile Robots
- Automated Storage and Retrieval Systems (AS/RS)
- Automated Sorting Systems
- Palletising and De-Palletising Systems
- Automated Conveyors
- Order-Picking Systems
- By End-User Industry
- Airport
- Post and Parcel
- General Manufacturing
- Automotive
- Food and Beverage
- Retail, Warehousing and Distribution
- Other End-User Industries
- By Component
- Hardware
- Software
- Services
- By Function
- Storage
- Order Picking and Retrieval
- Sorting and Consolidation
- Packaging and Palletising
- Transportation and Conveyance
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Swisslog Holding AG
- TGW Logistics Group GmbH
- Vanderlande Industries B.V.
- SSI Schafer AG
- Dematic GmbH (KION Group)
- Daifuku Co., Ltd.
- Exotec SAS
- AutoStore ASA
- ABB Ltd.
- Honeywell International Inc.
- Interroll Holding AG
- Jungheinrich Aktiengesellschaft
- Kardex Holding AG
- BEUMER Group GmbH and Co. KG
- KNAPP AG
- KUKA Aktiengesellschaft
- Linde Material Handling GmbH
- Murata Machinery, Ltd.
- Ocado Group plc
- Toyota Industries Corporation
- Viastore Systems GmbH
- WITRON Logistik + Informatik GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Industry Value / Supply-Chain Analysis
- 4.4 Market Drivers
- 4.4.1 E-Commerce Boom and Omnichannel Fulfilment Pressure
- 4.4.2 Labour Shortages and Wage Inflation Across EU27
- 4.4.3 Rapid Advances in AI-Powered Mobile Robotics and IoT
- 4.4.4 5G and Private-LTE Roll-Outs Enabling Real-Time Orchestration
- 4.4.5 EU Green Deal Incentives for Low-Carbon Intralogistics
- 4.4.6 Interoperability Standards (VDA 5050) Enabling Multi-Vendor Integration
- 4.5 Market Restraints
- 4.5.1 High Capex and Long ROI Horizons
- 4.5.2 Legacy IT and OT Integration Complexity
- 4.5.3 Rising Cyber-Security Threats to Networked Robotics
- 4.5.4 Grid Power Availability Bottlenecks in Logistics Hubs
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Adjacent Market Influence Analysis
- 4.9.1 Stretch-Wrapping Machines Market
- 4.9.2 Goods Elevator Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Mobile Robots
- 5.1.2 Automated Storage and Retrieval Systems (AS/RS)
- 5.1.3 Automated Sorting Systems
- 5.1.4 Palletising and De-Palletising Systems
- 5.1.5 Automated Conveyors
- 5.1.6 Order-Picking Systems
- 5.2 By End-User Industry
- 5.2.1 Airport
- 5.2.2 Post and Parcel
- 5.2.3 General Manufacturing
- 5.2.4 Automotive
- 5.2.5 Food and Beverage
- 5.2.6 Retail, Warehousing and Distribution
- 5.2.7 Other End-User Industries
- 5.3 By Component
- 5.3.1 Hardware
- 5.3.2 Software
- 5.3.3 Services
- 5.4 By Function
- 5.4.1 Storage
- 5.4.2 Order Picking and Retrieval
- 5.4.3 Sorting and Consolidation
- 5.4.4 Packaging and Palletising
- 5.4.5 Transportation and Conveyance
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Swisslog Holding AG
- 6.4.2 TGW Logistics Group GmbH
- 6.4.3 Vanderlande Industries B.V.
- 6.4.4 SSI Schafer AG
- 6.4.5 Dematic GmbH (KION Group)
- 6.4.6 Daifuku Co., Ltd.
- 6.4.7 Exotec SAS
- 6.4.8 AutoStore ASA
- 6.4.9 ABB Ltd.
- 6.4.10 Honeywell International Inc.
- 6.4.11 Interroll Holding AG
- 6.4.12 Jungheinrich Aktiengesellschaft
- 6.4.13 Kardex Holding AG
- 6.4.14 BEUMER Group GmbH and Co. KG
- 6.4.15 KNAPP AG
- 6.4.16 KUKA Aktiengesellschaft
- 6.4.17 Linde Material Handling GmbH
- 6.4.18 Murata Machinery, Ltd.
- 6.4.19 Ocado Group plc
- 6.4.20 Toyota Industries Corporation
- 6.4.21 Viastore Systems GmbH
- 6.4.22 WITRON Logistik + Informatik GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2026年全球物流自動化人工智慧(AI)市場報告
 物流自動化:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)貨櫃堆場物流:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)亞太地區貨櫃堆場物流:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)歐洲貨櫃堆場物流:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國貨櫃堆場物流:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 物流自動化市場預測至2034年-按組件、功能、技術、應用、最終用戶和地區分類的全球分析
 物流自動化市場:按組件、物流類型、技術、運作模式、部署類型、應用和最終用戶產業分類-2026-2032年全球市場預測北美物流自動化:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 物流自動化市場機會、成長要素、產業趨勢分析及2026-2035年預測