


 |
市場調查報告書
商品編碼
2124802
德國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Germany Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年德國設施管理市場價值為 909.6 億美元,預計到 2031 年將達到 1098.6 億美元,而 2026 年為 938.7 億美元,預測期(2026-2031 年)的複合年成長率為 3.20%。
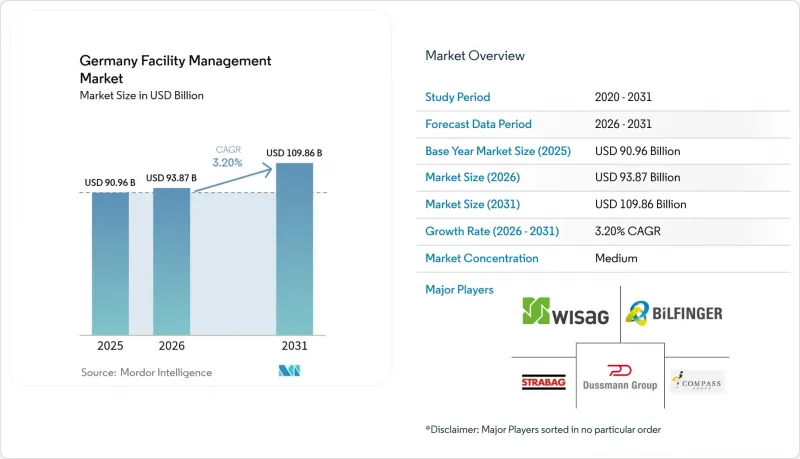
本報告按服務類型(硬服務和軟服務)、交付方式(內部交付和外包)以及最終用戶行業(商業、酒店、公共基礎設施、醫療保健、工業流程和其他最終用戶行業)進行分類。市場預測以美元計價。
德國設施管理市場的趨勢與洞察
嚴格的能源效率法規
《建築能源法》規定,2024年後安裝的暖氣系統必須至少65%的熱量來自再生能源來源,迫使業者更新鍋爐、冷卻器和管道網路。功率超過12千瓦的暖通空調設備必須定期接受認證專家的能源檢查,不合規的業主將面臨罰款。 《能源效率法》的補充規定也要求企業實施能源管理系統,涵蓋其90%的能源消耗,並公佈節能路線藍圖。這些義務推動了對監控感測器、分析儀錶板和節能績效合約服務的需求。能夠提供審計、性能再檢驗和資金籌措方案的服務供應商將在德國設施管理市場中獲得競爭優勢。
ESG合規的勢頭
預計到2026年,德國企業永續性報告指令將使編製非財務報告的德國企業數量增加兩倍,達到約15,000家。建築物約佔德國二氧化碳排放量的30%,因此設施管理是備受關注的高影響力領域。根據德國國家商業委員會(DGNB)的「雙重重要性」觀點,企業必須揭露其活動如何影響人類和地球,以及永續性風險如何影響其獲利能力。為此,服務供應商目前正將二氧化碳排放基準、可再生能源採購計畫和廢棄物減量關鍵績效指標(KPI)納入其服務水準協定(SLA)。一些引人注目的人事變動,例如ISS任命集團ESG主管,凸顯了這些績效指標如何影響競標評估和專案訂單。這些發展正推動德國設施管理市場向基於績效的定價模式轉型,該模式與檢驗的減排量掛鉤。
前期實施成本高
節能維修、先進感測器和現場可再生能源設施通常需要大量資本投資,這在經濟低迷時期會加劇預算壓力。 2023年,房地產交易量下降52%至317億歐元(369.4億美元),使得大規模維修的融資更加困難。業主擔心,德國能源監管局(GEG)強制要求的鍋爐更換將導致租金上漲、引發租戶不滿,並延誤工程核准。預計2025年建築支出將下降3.5%,因此分階段實施、租賃模式和公共津貼將成為重要的資金籌措選擇。如果沒有此類支持,一些營運商可能會推遲或縮減技術投資,這可能會在短期內減緩德國設施管理市場的成長潛力。
細分市場分析
2025年,硬性服務佔銷售額的56.62%。這是因為諸如暖通空調(HVAC)性能再檢驗和電氣安全檢查等合規性工作需要先進的工程技術。機械、電氣和管道團隊正在進行熱成像測量、平衡熱水循環迴路,並調整建築自動化邏輯以符合GEG基準值。資產管理顧問公司正在為老舊房地產制定生命週期計劃,其中60%的房地產房齡超過30年。隨著德國設施管理市場對硬性服務的規模要求因具有法律約束力的績效目標而日益嚴格,供應商正在投資基於感測器的工具包和雲端分析技術,以加快問題檢測並追蹤保固索賠。
預計「軟性服務」產業將以5.29%的複合年成長率成長,這反映出雇主越來越重視員工福祉。隨著清潔標準的日益完善,紫外線消毒機器人正被引入到下班後的清潔工作中;同時,飯店前台團隊正透過靈活的桌面管理應用程式來促進混合辦公體驗。保全人員擴大採用人工智慧影像分析系統來區分安全漏洞和日常事件。索迪斯的機器人廚房應用案例表明,自動化如何在不影響營養均衡的前提下提高醫療機構餐飲的處理能力。對技術整合型軟性服務日益成長的需求表明,到2031年,索迪斯在德國設施管理市場的佔有率將穩步成長,即便價值創造越來越依賴健康指標而非法律強制的合規標準。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 主要商業地產領域的當前運轉率
- 主要設施管理服務提供者的盈利基準
- 勞動指標-勞動參與率和技術工人數量
- 按服務類型分類的設施管理市場佔有率(%)
- 依硬體維修服務分類的設施管理市場佔有率(%)
- 軟性設施管理服務在設施管理市場佔有率(%)
- 主要大都會圈(柏林、慕尼黑、漢堡、科隆、法蘭克福)的都市化與人口成長
- 德國國家基礎設施計畫中的產業投資優先事項
- 勞動和安全標準方面的監管促進者
- 因素
- 嚴格的能源效率法規
- ESG合規的勢頭
- 數位轉型與智慧建築
- 勞動力自動化的勢頭
- 抑制因子
- 前期實施成本高
- 網路安全和資料隱私問題
- 價值鏈分析
- PESTLE分析
- 市場准入者的法規和法律體制
- 宏觀經濟指標對設施管理需求的影響。
- 波特五力分析
- 投資和資金籌措分析
第5章 市場規模與成長預測
- 按服務類型
- 硬服務
- 資產管理
- 機電及暖通空調服務
- 消防系統和安全
- 其他硬體維修服務
- 軟服務
- 辦公室支援和安全
- 清潔服務
- 餐飲服務
- 其他軟調頻服務
- 硬服務
- 按服務類型
- 內部
- 外包
- 單頻調頻
- 捆綁式調頻廣播
- 整合調頻
- 按最終用戶行業分類
- 商業(IT/電信、零售/倉儲)
- 飯店餐飲業(飯店、餐廳、餐廳)
- 公共和社會基礎設施(政府、教育、交通)
- 零售和倉儲
- 醫療保健(公立和私立機構)
- 工業和流程(製造業、能源業、採礦業)
- 其他終端用戶產業(多用戶住宅、娛樂、運動和休閒)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Strabag SE
- Bilfinger SE
- Dussmann Group
- Compass Group PLC
- Wisag Facility Service Holding GmbH
- Vinci SA
- Aramark
- ISS Facilities Services Inc.
- Sodexo
- Apleona GmbH
- Weidemann Gruppe GmbH
- Coor Group
- Ray Facility Management
- Gegenbauer Services GmbH
- SPIE Deutschland & Zentraleuropa
- Kluh Service Management GmbH
- Piepenbrock Dienstleistungen GmbH & Co. KG
- Sasse Group
- Hectas Facility Services
- Johnson Controls(Germany)
- Caverion Deutschland GmbH
- Engie Deutschland GmbH
- Siemens Smart Infrastructure
- CBRE GWS Germany
- Serco Limited(Germany)
- Mitie Deutschland
第7章 市場機會與未來展望
According to Mordor Intelligence, the Germany facility management market size was valued at USD 90.96 billion in 2025 and estimated to grow from USD 93.87 billion in 2026 to reach USD 109.86 billion by 2031, at a CAGR of 3.20% during the forecast period (2026-2031).
This report is Segmented by Service Type (Hard Services, and Soft Services), Offering Type (In-House, and Outsourced), End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Healthcare, Industrial and Process, and Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
Germany Facility Management Market Trends and Insights
Stringent Energy Efficiency Regulations
The Gebaudeenergiegesetz requires new heating systems installed from 2024 to derive at least 65% of heat from renewable sources, pushing operators to upgrade boilers, chillers, and distribution networks. HVAC units exceeding 12 kW must pass periodic energy inspections by certified experts, and owners face fines when deadlines lapse.Complementary rules under the Energy Efficiency Act oblige enterprises to deploy energy-management systems covering 90% of consumption and to publish reduction roadmaps. These mandates elevate demand for monitoring sensors, analytics dashboards, and performance contracting services that guarantee savings. Service providers able to bundle auditing, retro-commissioning, and financing options gain a competitive advantage in the Germany facility management market.
ESG Compliance Momentum
The Corporate Sustainable Reporting Directive will triple the number of German entities producing non-financial statements, reaching nearly 15,000 by 2026. Buildings contribute around 30% of national CO2 emissions, making facility operations a high-impact target. DGNB's "double materiality" lens obliges firms to disclose how their activities affect people and planet and how sustainability risks affect revenues. In response, providers now embed CO2 baselines, renewable sourcing plans, and waste-reduction KPIs into service-level agreements. High-profile appointments, such as ISS naming a Group Head of ESG, underline how credentials drive bid evaluation and project awards. This alignment is nudging the Germany facility management market toward outcome-based pricing tied to verified emissions cuts.
High Initial Implementation Costs
Energy-positive retrofits, advanced sensors, and on-site renewables often require capital outlays that stretch budgets during a downturn. The property sector saw deal volumes fall 52% to EUR 31.7 billion (USD 36.94 billion) in 2023, tightening credit for large upgrades. Owners worry that GEG-mandated boiler replacements might raise rents, provoking tenant resistance and delaying project approvals. Construction spending is projected to contract by 3.5% in 2025, so phased roll-outs, leasing models, and public grants become essential financing levers. Without these supports, some operators may defer or scale back technology investments, muting growth potential for the Germany facility management market in the near term.
Other drivers and restraints analyzed in the detailed report include:
- Digital Transformation and Smart Buildings
- Workforce Automation Momentum
- Cybersecurity and Data Privacy Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard Services contributed 56.62% of 2025 revenue because regulatory compliance tasks such as HVAC retro-commissioning and electrical safety inspections demand deep engineering know-how. Mechanical, electrical, and plumbing teams schedule thermographic surveys, balance hydronic circuits, and tune building-automation logic to align with GEG thresholds. Asset-management consultancies overlay life-cycle planning on an aging real-estate stock where 60% of properties exceed 30 years. As the Germany facility management market size for Hard Services tightens around legally enforceable performance targets, suppliers invest in sensor-equipped toolkits and cloud analytics that speed issue detection and track warranty claims.
Soft Services, forecast at a 5.29% CAGR, mirror employers' focus on occupant well-being. Heightened cleaning standards integrate UV-C disinfection robots for after-hours sweeps, while hospitality-grade front-of-house teams curate hybrid-work experiences through flex-desk management apps. Security guards increasingly deploy AI-enabled video analytics that distinguish safety breaches from routine events. Sodexo's robotic kitchen use case shows how automation raises throughput in healthcare catering without compromising nutrition. The growing appetite for tech-infused Soft Services suggests that their Germany facility management market share will rise steadily through 2031, even though value creation remains tethered to wellness metrics more than mandated compliance thresholds.
Complete Report Scope:
- By Service Type
- Hard Services
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- Soft Services
- Office Support and Security
- Cleaning Services
- Catering Services
- Other Soft FM Services
- Hard Services
- By Offering Type
- In-house
- Outsourced
- Single FM
- Bundled FM
- Integrated FM
- By End-user Industry
- Commercial (IT and Telecom, Retail and Warehousing)
- Hospitality (Hotels, Eateries, Restaurants)
- Institutional and Public Infrastructure (Govt, Education, Transport)
- Retail and Warehousing
- Healthcare (Public and Private Facilities)
- Industrial and Process (Manufacturing, Energy, Mining)
- Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
List of Companies Covered in this Report:
- Strabag SE
- Bilfinger SE
- Dussmann Group
- Compass Group PLC
- Wisag Facility Service Holding GmbH
- Vinci SA
- Aramark
- ISS Facilities Services Inc.
- Sodexo
- Apleona GmbH
- Weidemann Gruppe GmbH
- Coor Group
- Ray Facility Management
- Gegenbauer Services GmbH
- SPIE Deutschland & Zentraleuropa
- Kluh Service Management GmbH
- Piepenbrock Dienstleistungen GmbH & Co. KG
- Sasse Group
- Hectas Facility Services
- Johnson Controls (Germany)
- Caverion Deutschland GmbH
- Engie Deutschland GmbH
- Siemens Smart Infrastructure
- CBRE GWS Germany
- Serco Limited (Germany)
- Mitie Deutschland
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.1.1 Current Occupancy Rates in Key Commercial Real Estate Segments
- 4.1.2 Profitability Benchmarks of Major FM Providers
- 4.1.3 Workforce Indicators - Labour Participation and Skill Availability
- 4.1.4 Facility Management Market Share (%) by Service Type
- 4.1.5 Facility Management Market Share (%) by Hard FM Services
- 4.1.6 Facility Management Market Share (%) by Soft FM Services
- 4.1.7 Urbanisation and Population Growth in Top Metros (Berlin, Munich, Hamburg, Cologne, Frankfurt)
- 4.1.8 Sector Investment Priorities in Germany's National Infrastructure Pipeline
- 4.1.9 Regulatory Drivers Specific to Labour and Safety Standards
- 4.2 Drivers
- 4.2.1 Stringent Energy Efficiency Regulations
- 4.2.2 ESG Compliance Momentum
- 4.2.3 Digital Transformation and Smart Buildings
- 4.2.4 Workforce Automation Momentum
- 4.3 Restraints
- 4.3.1 High Initial Implementation Costs
- 4.3.2 Cybersecurity and Data Privacy Concerns
- 4.4 Value Chain Analysis
- 4.5 PESTEL Analysis
- 4.6 Regulatory and Legislative Framework for Market Entrants
- 4.7 Impact of Macroeconomic Indicators on Facility Management Demand
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Services
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Hard Services
- 5.1.1.1 Asset Management
- 5.1.1.2 MEP and HVAC Services
- 5.1.1.3 Fire Systems and Safety
- 5.1.1.4 Other Hard FM Services
- 5.1.2 Soft Services
- 5.1.2.1 Office Support and Security
- 5.1.2.2 Cleaning Services
- 5.1.2.3 Catering Services
- 5.1.2.4 Other Soft FM Services
- 5.1.1 Hard Services
- 5.2 By Offering Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.2.2.1 Single FM
- 5.2.2.2 Bundled FM
- 5.2.2.3 Integrated FM
- 5.3 By End-user Industry
- 5.3.1 Commercial (IT and Telecom, Retail and Warehousing)
- 5.3.2 Hospitality (Hotels, Eateries, Restaurants)
- 5.3.3 Institutional and Public Infrastructure (Govt, Education, Transport)
- 5.3.3.1 Retail and Warehousing
- 5.3.4 Healthcare (Public and Private Facilities)
- 5.3.5 Industrial and Process (Manufacturing, Energy, Mining)
- 5.3.6 Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Strabag SE
- 6.4.2 Bilfinger SE
- 6.4.3 Dussmann Group
- 6.4.4 Compass Group PLC
- 6.4.5 Wisag Facility Service Holding GmbH
- 6.4.6 Vinci SA
- 6.4.7 Aramark
- 6.4.8 ISS Facilities Services Inc.
- 6.4.9 Sodexo
- 6.4.10 Apleona GmbH
- 6.4.11 Weidemann Gruppe GmbH
- 6.4.12 Coor Group
- 6.4.13 Ray Facility Management
- 6.4.14 Gegenbauer Services GmbH
- 6.4.15 SPIE Deutschland & Zentraleuropa
- 6.4.16 Kluh Service Management GmbH
- 6.4.17 Piepenbrock Dienstleistungen GmbH & Co. KG
- 6.4.18 Sasse Group
- 6.4.19 Hectas Facility Services
- 6.4.20 Johnson Controls (Germany)
- 6.4.21 Caverion Deutschland GmbH
- 6.4.22 Engie Deutschland GmbH
- 6.4.23 Siemens Smart Infrastructure
- 6.4.24 CBRE GWS Germany
- 6.4.25 Serco Limited (Germany)
- 6.4.26 Mitie Deutschland
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Technology-led Integrated FM (IoT, BMS, AI-based Predictive Maintenance)
- 7.3 ESG-Compliant FM Solutions Demand
- 7.4 Future Service-Model Shifts (Outcome-Based Contracts)
- 7.5 Data-Driven Energy Optimisation and Carbon Reporting Services

 2026-2030年全球設施管理市場
 設施管理(FM)軟體:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)北美設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)亞太地區硬設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)硬設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)日本設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 Frost Radar™:泰國設施管理,2026 年中國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)新加坡設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)