


 |
市場調查報告書
商品編碼
2124846
新加坡設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Singapore Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 的數據,新加坡設施管理 (FM) 市場在 2025 年的價值為 36.9 億美元,預計到 2031 年將達到 42.6 億美元,而 2026 年為 37.8 億美元,預測期(2026-2031 年)的複合年成長率為 2.41%。
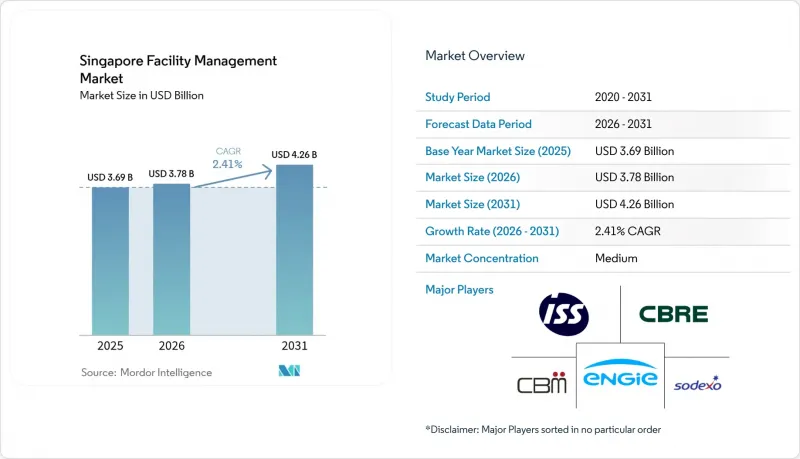
本報告按服務類型(硬性服務、軟性服務)、交付類型(內部交付、外包[單一設施管理、捆綁式設施管理、整合式設施管理])、最終用戶行業(商業、零售、餐飲、製造/工業、其他)、設施類型(商業建築、工業設施、其他)和地區進行細分。市場預測以美元計價。
新加坡設施管理市場趨勢與洞察
加速非核心業務外包
為了專注於核心收入來源,各機構紛紛將建築營運外包。自2020年5月起,所有公部門保全合約均須遵守「基於結果的安保合約」規定,要求競標不僅提供人員,更需證明其技術能力。凱德整合式的案例充分展現了外包的巨大潛力。該公司價值179億美元的物業組合由專業子公司負責管理,該子公司提供端到端的租賃、工程和永續發展專案營運服務。外包還能提供先進的分析技術、電腦視覺巡邏和預測性維護工具,而這些工具如果自行開發成本過高,則更有利於企業獲得這些服務。隨著環境資訊揭露法規日益嚴格,客戶也越來越依賴外部設施管理合作夥伴提供碳排放報告的專業知識。這些趨勢共同導致新加坡設施管理市場對服務供應商的需求不斷成長,同時也擴大了合約的範圍和期限。
地鐵沿線地區的基建發展蓬勃興旺
在新加坡,新的鐵路走廊正在陸續開發,每條線路都伴隨著長期的營運和維護(O&M)義務。陸路交通管理局(LTA)委託建設的價值3.552億美元的跨島線二期工程-馬朱站土木工程項目,以及授予新捷運(SBS Transit)和巴黎大眾運輸公司(RATP Dev)聯合體的九年裕廊區域線運營許可證,都要求從一開始就採用人工智慧驅動的狀態監測。因此,資產所有者正在儘早尋找綜合設施管理(FM)合作夥伴,從而確保那些精通鐵路沿線設施、車站公用設施和人流分析的供應商能夠獲得數十年的穩定收入。這種連鎖反應也延伸到圍繞新車站的零售、辦公和住宅項目,所有這些項目都需要整合建築系統來確保舒適的通勤體驗。這種以鐵路為中心的開發模式為新加坡設施管理市場的多元化服務和區域性連鎖成長奠定了基礎。
高度分散的本地供應商群體
由於新加坡有數百家小規模清潔和保全公司,合約管理十分複雜。隨著分包商數量的增加,執行時間、網路安全風險和介面風險也隨之增加,大規模業主整合供應商。儘管新加坡建設局(BCA)目前提供基於能力的認證體系,但公眾接受度仍然有限。在整合和認證加速推進之前,標準差異可能會阻礙新加坡設施管理市場效率的提升。
細分市場分析
在新加坡的設施管理市場,預計到2025年,硬性服務將佔總收入的53.62%。這主要是因為在潮濕的熱帶氣候下,機械、電氣和管道系統必須完美運作。消防安全認證和電梯維護記錄等監管要求也印證了這項基本需求。預測性維護的趨勢十分顯著,「綠色標誌」冷卻器入口網站就是一個典型的例子,它透過分析振動和溫度數據來預防停機。客戶越來越重視生命週期成本最佳化,而非被動維修,這推動了包含性能保證的硬體維修管理捆綁合約的普及。
隨著績效基本契約將定價與人員成本脫鉤,軟性服務正以2.99%的複合年成長率快速成長。在安保領域,績效基本契約正在重新定義人員配備模式,要求保全人員使用無人機、影像分析和事件報告應用程式。清潔服務供應商正在部署即時品質感測器,而租戶互動應用程式則在協調餐飲和禮賓服務。儘管軟性服務的絕對規模仍落後於硬性服務,但其技術驅動的復甦表明,新加坡的設施管理市場正從勞動密集的日常營運轉型為數據驅動的體驗式服務。
至2025年,外包將佔新加坡物業管理市場規模的62.98%。這是因為客戶更傾向於選擇一站式專業服務商,由其負責合規、品質保證管理和永續發展報告。整合工程、環境和飯店服務的綜合設施管理合約正蓬勃發展,凱德集團將租賃、技術和ESG服務打包,由單一供應商負責。自動化工單平台和服務等級協定(SLA)儀錶板確保了績效透明度,業主越來越重視這種透明度,將其視為風險轉移機制。
到2025年,內部營運雖然僅佔37.02%,但隨著資料中心營運商和政府機構對更強大的網路安全和關鍵系統管理的需求日益成長,預計其複合年成長率將達到3.88%。新加坡建設局學院(BCA Academy)推出的全新智慧建築課程旨在支持這一轉變,培養精通數位孿生、物聯網網路安全和故障診斷的認證工程師。此外,混合模式也正在興起:業主自行負責分析和策略制定,而將現場營運外包,這反映了新加坡設施管理市場需求模式的複雜性。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速非核心業務外包
- 地鐵沿線地區的基建發展蓬勃興旺
- 遵守 BCA 綠色標誌 Plus 的義務
- 需要進行生命週期維修的老舊商業地產。
- 新加坡「智慧國家」計畫中的智慧社區
- 公共醫療保健領域的綜合設施合約
- 市場限制因素
- 高度分散的本地供應商群體
- 更嚴格的外籍勞工引進配額和不斷上漲的人事費用
- 政府設施競標規則複雜
- 作為島國,其擴張受到限制
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 硬服務
- 資產管理
- 機電/暖通空調服務
- 消防系統和安全措施
- 其他硬體維修服務
- 軟服務
- 辦公室支援和安全
- 清潔服務
- 餐飲服務
- 其他軟調頻服務
- 硬服務
- 按服務類型
- 內部
- 外包
- 單頻調頻
- 捆綁式調頻廣播
- 整合調頻
- 按最終用戶行業分類
- 商業、零售和餐飲企業。
- 製造業和工業
- 政府、基礎建設、公共機構
- 機構
- 其他
- 依設施類型
- 商業建築
- 工業設施
- 公共基礎設施
- 公共設施
- 其他設施類型
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Abacus Property Management Pte. Ltd.
- ACMS Facilities Management Pte. Ltd.
- CBM Pte. Ltd.
- CBRE Group, Inc.
- Certis CISCO Security Pte. Ltd.
- Compass Group PLC
- Cushman and Wakefield PLC
- ENGIE Services Singapore Pte. Ltd.
- Exceltec Property Management Pte. Ltd.
- ISS A/S
- Jones Lang LaSalle Incorporated
- OCS Group International Limited
- Savills (Singapore) Pte. Ltd.
- Serco Group PLC
- Sodexo Singapore Pte. Ltd.
- United Tec Engineering Pte. Ltd.
- UTiZ Facilities Management Services Pte. Ltd.
- Vinci Facilities SAS
第7章 市場機會與未來展望
According to Mordor Intelligence, the Singapore facility management market size was valued at USD 3.69 billion in 2025 and estimated to grow from USD 3.78 billion in 2026 to reach USD 4.26 billion by 2031, at a CAGR of 2.41% during the forecast period (2026-2031).
This report is Segmented by Service Type (Hard Services, and Soft Services), Offering Type (In-House, and Outsourced [Single FM, Bundled FM, and Integrated FM]), End-User Industry (Commercial/Retail/Restaurants, Manufacturing/Industrial, and More), Facility Type (Commercial Buildings, Industrial Facilities, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Singapore Facility Management Market Trends and Insights
Outsourcing of Non-core Operations Accelerating
Organizations are handing off building operations so they can focus on core revenue drivers. Since May 2020, every public-sector contract for security has had to comply with Security Outcome-Based Contracting, forcing bidders to prove technology capabilities rather than supply headcount. CapitaLand Integrated Commercial Trust illustrates how extensive outsourcing can become: property management for its USD 17.9 billion portfolio is handled by specialist subsidiaries that run leasing, engineering, and sustainability programs end-to-end. Access to advanced analytics, computer-vision patrols, and predictive maintenance tools that would be cost-prohibitive to build in-house further strengthens the outsourcing rationale. As environmental disclosure rules tighten, clients also rely on external FM partners for carbon-reporting expertise. Collectively, these dynamics raise the bar for service providers while expanding contract scope and duration within the Singapore facility management market.
Infrastructure Boom in MRT-Linked Districts
Singapore is adding entire rail corridors, each embedding long-term O&M obligations. The Land Transport Authority's USD 355.2 million Maju station civil package for Cross Island Line Phase 2 and the nine-year Jurong Region Line operating license awarded to the SBS Transit and RATP Dev consortium require AI-driven condition monitoring from day one. Asset owners, therefore, lock in integrated FM partners early, guaranteeing multi-decade revenue streams for vendors proficient in track-side facilities, station utilities, and crowd-flow analytics. Knock-on effects spread to retail podiums, office towers, and residential projects clustered around new stations, all of which demand unified building systems to ensure a frictionless commuter experience. This rail-centric development model underpins service line diversification and regional spillover growth for the Singapore facility management market.
Highly Fragmented Local Vendor Base
Hundreds of micro-scale cleaning and security firms make contract administration cumbersome. Each additional subcontractor adds onboarding time, cybersecurity exposure, and interface risk, prompting large owners to consolidate suppliers. BCA now offers competency-based accreditations, but public-agency acceptance remains partial. Until aggregation or certification gains speed, disparate standards will temper efficiency gains in the Singapore facility management market.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory BCA Green Mark Plus Compliance
- Ageing Commercial Stock Requiring Lifecycle Upgrades
- Tight Foreign-Worker Quotas and Rising Labour Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard services represented 53.62% of 2025 revenue within the Singapore facility management market share because mechanical, electrical, and plumbing systems must operate flawlessly in a humid tropical climate. Regulatory obligations for fire-safety certifications and lift-maintenance logs sustain baseline demand. Momentum toward predictive analytics is palpable, exemplified by the Green Mark chiller portal that digests vibration and temperature data to prevent downtime. Clients increasingly value lifecycle-cost optimization over reactive fixes, prompting bundled hard-FM contracts with outcome guarantees.
Soft services are expanding at 2.99% CAGR as outcome-based contracting decouples pricing from headcount. Security Outcome-Based Contracting compels guards to use drones, video analytics, and incident-reporting apps, redefining manpower deployment. Cleaning vendors adopt real-time quality sensors, while tenant-engagement apps coordinate catering and concierge tasks. Although soft services still trail hard services in absolute value, their technology-enabled rebound illustrates how the Singapore facility management market evolves from labour-intensive routines to data-validated experiences.
Outsourcing held 62.98% of the Singapore facility management market size in 2025 because clients prefer one-stop specialists for compliance, warranty management, and sustainability reporting. Integrated FM contracts that fuse engineering, environmental, and hospitality tasks gain traction, with CapitaLand bundling leasing, technical, and ESG services under single-vendor accountability. Automated ticketing platforms and SLA dashboards lock in performance transparency, which owners increasingly treat as a risk-transfer mechanism.
In-house delivery, though just 37.02% in 2025, is forecast to grow 3.88% CAGR as data-center operators and government agencies seek tighter control over cybersecurity and critical systems. BCA Academy's new smart-building curricula underpin this shift by supplying certified engineers versed in digital twins, IoT cybersecurity, and fault diagnostics. Hybrid models are also emerging where owners retain analytics and strategy while outsourcing boots-on-ground execution, reflecting nuanced demand patterns in the Singapore facility management market.
Complete Report Scope:
- By Service Type
- Hard Services
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- Soft Services
- Office Support and Security
- Cleaning Services
- Catering Services
- Other Soft FM Services
- Hard Services
- By Offering Type
- In-house
- Outsourced
- Single FM
- Bundled FM
- Integrated FM
- By End-User Industry
- Commercial, Retail and Restaurants
- Manufacturing and Industrial
- Government, Infrastructure and Public Entities
- Institutional
- Other End-user Industries
- By Facility Type
- Commercial Buildings
- Industrial Facilities
- Public Infrastructure
- Institutional Buildings
- Other Facility Types
List of Companies Covered in this Report:
- Abacus Property Management Pte. Ltd.
- ACMS Facilities Management Pte. Ltd.
- CBM Pte. Ltd.
- CBRE Group, Inc.
- Certis CISCO Security Pte. Ltd.
- Compass Group PLC
- Cushman and Wakefield PLC
- ENGIE Services Singapore Pte. Ltd.
- Exceltec Property Management Pte. Ltd.
- ISS A/S
- Jones Lang LaSalle Incorporated
- OCS Group International Limited
- Savills (Singapore) Pte. Ltd.
- Serco Group PLC
- Sodexo Singapore Pte. Ltd.
- United Tec Engineering Pte. Ltd.
- UTiZ Facilities Management Services Pte. Ltd.
- Vinci Facilities S.A.S.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Outsourcing of Non-core Operations Accelerating
- 4.2.2 Infrastructure Boom in MRT-Linked Districts
- 4.2.3 Mandatory BCA Green Mark Plus Compliance
- 4.2.4 Ageing Commercial Stock Requiring Lifecycle Upgrades
- 4.2.5 Smart Estates under Singapore Smart Nation Drive
- 4.2.6 Integrated Facilities Contracts in Public Healthcare
- 4.3 Market Restraints
- 4.3.1 Highly Fragmented Local Vendor Base
- 4.3.2 Tight Foreign-Worker Quotas and Rising Labour Costs
- 4.3.3 Complex Tender Regulations for Government Sites
- 4.3.4 Limited Scalability in Island-State Geography
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products and Services
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Hard Services
- 5.1.1.1 Asset Management
- 5.1.1.2 MEP and HVAC Services
- 5.1.1.3 Fire Systems and Safety
- 5.1.1.4 Other Hard FM Services
- 5.1.2 Soft Services
- 5.1.2.1 Office Support and Security
- 5.1.2.2 Cleaning Services
- 5.1.2.3 Catering Services
- 5.1.2.4 Other Soft FM Services
- 5.1.1 Hard Services
- 5.2 By Offering Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.2.2.1 Single FM
- 5.2.2.2 Bundled FM
- 5.2.2.3 Integrated FM
- 5.3 By End-User Industry
- 5.3.1 Commercial, Retail and Restaurants
- 5.3.2 Manufacturing and Industrial
- 5.3.3 Government, Infrastructure and Public Entities
- 5.3.4 Institutional
- 5.3.5 Other End-user Industries
- 5.4 By Facility Type
- 5.4.1 Commercial Buildings
- 5.4.2 Industrial Facilities
- 5.4.3 Public Infrastructure
- 5.4.4 Institutional Buildings
- 5.4.5 Other Facility Types
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Abacus Property Management Pte. Ltd.
- 6.4.2 ACMS Facilities Management Pte. Ltd.
- 6.4.3 CBM Pte. Ltd.
- 6.4.4 CBRE Group, Inc.
- 6.4.5 Certis CISCO Security Pte. Ltd.
- 6.4.6 Compass Group PLC
- 6.4.7 Cushman and Wakefield PLC
- 6.4.8 ENGIE Services Singapore Pte. Ltd.
- 6.4.9 Exceltec Property Management Pte. Ltd.
- 6.4.10 ISS A/S
- 6.4.11 Jones Lang LaSalle Incorporated
- 6.4.12 OCS Group International Limited
- 6.4.13 Savills (Singapore) Pte. Ltd.
- 6.4.14 Serco Group PLC
- 6.4.15 Sodexo Singapore Pte. Ltd.
- 6.4.16 United Tec Engineering Pte. Ltd.
- 6.4.17 UTiZ Facilities Management Services Pte. Ltd.
- 6.4.18 Vinci Facilities S.A.S.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026-2030年全球設施管理市場
 設施管理(FM)軟體:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)北美設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)亞太地區硬設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)硬設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)日本設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 Frost Radar™:泰國設施管理,2026 年中國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)