


 |
市場調查報告書
商品編碼
2116929
亞太地區硬設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Asia-Pacific Hard Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
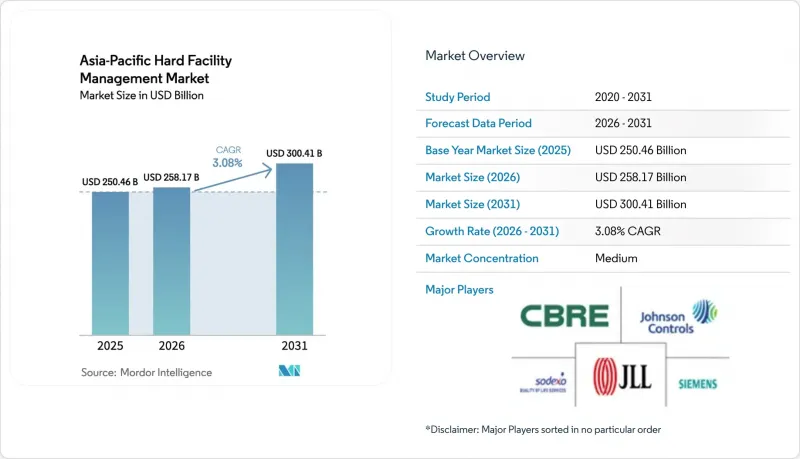
根據 Mordor Intelligence 預測,亞太地區硬設施管理市場規模預計將從 2025 年的 2,504.6 億美元成長到 2026 年的 2,581.7 億美元,到 2031 年將達到 3,004.1 億美元,2026 年至 2031 年的複合年成長率為 3.08%。
本報告按服務類型(例如,電氣設備維護、暖通空調(空調、通風、給排水)維護服務)、最終用戶(例如,商業設施、公共設施)、服務交付模式(例如,內部服務、單一服務外包)、設施類型(例如,醫療設施、飯店和休閒設施)以及國家/地區進行分類。市場預測以美元計價。
亞太地區硬設施管理市場的趨勢與洞察。
商業和工業建設活動的擴張
新興產業走廊正在重塑亞太地區的硬設施管理市場。預計2024年,中國二線城市的商業占地面積將成長18%,而越南、印尼和泰國的製造業將吸引420億美元的外國直接投資(FDI)。開發商擴大將三年的機電維護納入承包工程,縮短競標週期,並傾向於選擇擁有預先協商的供應商網路的整合商。服務供應商正在成都、浦那和河內等地設立衛星服務點,以確保在四小時內滿足服務等級協定(SLA)的要求。這導致了地域格局的重組,擁有區域物流規劃和本地授權經驗的公司將佔據優勢。那些無法走出傳統城市中心的公司,可能會錯失未來十年可能決定收入來源的機會。
對暖通空調和機電維護服務的需求不斷成長
由於熱帶高濕度和都市化導致製冷負荷不斷增加,暖通空調(HVAC)維護仍然是亞太地區硬設施管理市場的主要驅動力。然而,市場需求正從簡單的日常維護轉向更具技術性的要求。在新加坡的區域冷卻系統中,現在需要持續的冷媒洩漏檢測和遠端遙測,而傳統的預防性維護計畫無法滿足這些需求。在馬來西亞,冷卻器維修可確保節能,並將風險轉移給供應商。隨著物聯網診斷技術將48小時故障恢復標準化,供應商必須投資分析人員和備件庫存。如果缺乏這些能力,中型承包商將把主要客戶拱手讓給那些能夠保證性能的公司。
熟練技術人員短缺
勞動力短缺是亞太地區硬基礎設施管理市場面臨的最迫切障礙。新加坡預計到2024年,認證暖通空調工程師的缺口將達到12%。澳洲的電工面臨15%的薪資成長,而馬來西亞的建設產業則面臨15%的勞動力短缺。大型整合商已透過開設培訓學院來應對這項挑戰。 ISS計劃透過其新開設的東南亞中心,每年培養500名畢業生。中小企業缺乏複製這種模式的規模,而且員工流動率高,導致人才流向薪資更高的資料中心工作。這種技能缺口推高了服務成本,並威脅到服務等級協定(SLA)的合規性,因此買家越來越重視那些擁有正式人才發展計畫的供應商。
細分市場分析
亞太地區能源管理和電力系統的硬設施管理市場預計將以3.83%的複合年成長率成長,顯著超過傳統暖通空調(HVAC)服務。能源管理合約擴大納入現場可再生能源、電池儲能和預測負載波動的數位孿生技術。由於買家優先考慮已證實有效的成本節約方案,能夠提供測量、分析和性能保證一體化服務的供應商可以設定更高的價格。相較之下,到2025年,暖通空調維護仍將佔亞太地區硬設施管理市場佔有率的38.12%,但其成長速度正在放緩,因為許多已安裝的設備正在老化,等待分階段更換。機械和電氣設備的維護仍將是一個基礎領域,但隨著物聯網感測器的普及,定期檢查的需求減少,維護服務可能會趨於商品化。消防和生命安全系統的維護正獲得監管方面的支持,而管道服務在水資源保護地區的重要性日益凸顯。
諸如更換濾芯之類的常規任務正逐漸轉向基於績效的定價模式,這有利於那些投資遠端監控硬體的公司。江森自控在亞太地區2024年訂單保證合約數量增加了25%,顯示金融創新與市場佔有率之間存在關聯。無法保證節能效果的供應商將被財務基礎更雄厚的平台蠶食市場佔有率。因此,規模化整合商與精通液冷、再生水回收等高價值細分領域的專業公司之間的競爭格局正變得愈發清晰。
隨著價值鏈多元化加速工廠向越南、印尼和印度的轉移,工業和製造業客戶有望透過以4.18%的複合年成長率成長的額外支出創造顯著的附加價值。半導體製造廠和製藥廠需要無塵室空調、超純水和冗餘電源,因此每平方公尺的收入遠高於辦公大樓。儘管商業建築在2025年仍將佔支出的46.05%,但由於城市飽和和混合辦公模式的興起限制了對新空間的需求,其成長速度落後於其他產業。政府對醫院維修和科研園區的撥款增加了醫療保健和教育產業的預算,從而保護了現金流免受經濟週期的影響。
儘管住宅小區仍普遍採用內部管理模式,但新加坡和雪梨的豪華高層公寓正在試驗預測性維護外包,以提升其配套設施的差異化優勢。對於設施管理 (FM) 服務提供者而言,產業多元化催生了對區域部署基地、備件物流和專業認證的需求。那些早期投資培訓本地技術人員並與原始設備製造商 (OEM) 合作的公司,正獲得利潤率更高的多年期合約。而後發者則面臨陡峭的學習曲線,並可能被複雜產業細分市場拒之門外。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 商業和工業建設活動的擴張
- 對暖通空調和機電維護服務的需求不斷成長
- 向設施管理合約外包過渡
- 推廣節能與綠建築法規
- 超大規模資料中心建設的擴張正在推動關鍵設施管理需求的成長。
- 企業現場可再生能源部署目標與微電網維護
- 市場限制因素
- 技術工人短缺
- 能源和原料成本的波動給利潤率帶來了壓力。
- 亞太地區合規和認證格局分散
- 由於電網容量不足,該設施的移交工作被推遲。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 機械設備的維護與修理
- 電氣設備的維護和修理
- 暖通空調維護服務
- 消防和防災系統的維護
- 管道和水資源管理
- 建築物外牆和結構的維護
- 能源管理和電力系統
- 最終用戶
- 商業的
- 機構(教育和醫療保健)
- 通用/基礎設施
- 工業和製造業
- 住宅和混合用途
- 按服務交付模式
- 內部(由我公司實施)
- 單一服務的外包
- 綜合設施管理(IFM)
- 混合模式
- 依設施類型
- 辦公大樓和企業園區
- 工業和物流設施
- 資料中心和關鍵環境
- 醫療機構
- 飯店和休閒設施
- 交通樞紐和基礎設施
- 國家
- 澳洲
- 中國
- 印度
- 日本
- 印尼
- 馬來西亞
- 新加坡
- 韓國
- 台灣
- 泰國
- 其他亞太國家
第6章 競爭情勢
- 市場集中度分析
- 策略趨勢
- 市佔率分析
- 公司簡介
- Jones Lang LaSalle Incorporated
- CBRE Group, Inc.
- Sodexo SA
- ISS A/S
- Cushman and Wakefield plc
- Johnson Controls International plc
- Siemens AG
- Honeywell International Inc.
- Aden Group Limited
- Aeon Delight Co., Ltd.
- Ventia Services Group Limited
- OCS Group Limited
- Nippon Kanzai Co., Ltd.
- Brookfield Global Integrated Solutions Canada LP
- Downer Edi Limited(Facilities Management)
- Serco Group plc
- GDI Integrated Facility Services Inc.
- EMCOR Group, Inc.
- Atalian Global Services SAS
- Knight Facilities Management Ltd.
- BVG India Limited
- Sembcorp Facilities Management Pte Ltd.
- Mapletree Facilities Services Pte Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the asia-Pacific hard facility management market size is expected to grow from USD 250.46 billion in 2025 to USD 258.17 billion in 2026 and is forecast to reach USD 300.41 billion by 2031 at 3.08% CAGR over 2026-2031.
This report is Segmented by Service Type (Electrical Services Maintenance, HVAC Maintenance Services, and More), End User (Commercial, Institutional, and More), Service Delivery Model (In-House, Outsourced Single-Service, and More), Facility Type (Healthcare Facilities, Hospitality and Leisure Properties, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Hard Facility Management Market Trends and Insights
Expansion of Commercial and Industrial Construction Activity
Emerging industrial corridors are reshaping the Asia-Pacific hard facility management market. Commercial square footage in China's tier-2 cities increased 18% in 2024, and Vietnam, Indonesia, and Thailand attracted USD 42 billion of manufacturing FDI the same year. Developers often bundle three-year mechanical and electrical maintenance into turnkey packages, shortening the bid cycle and favoring integrators with pre-negotiated supplier networks. Providers are opening satellite depots in Chengdu, Pune, and Hanoi so they can meet service-level agreements within four hours. The result is a geographic realignment that rewards firms with regional logistics planning and local permitting expertise. Those unable to migrate beyond legacy urban cores risk missing a wave of opportunity that could define revenue pools for the rest of the decade.
Rising Demand for HVAC and MEP Maintenance Services
HVAC upkeep remains a key driver of the Asia-Pacific hard facility management market, as tropical humidity and dense urbanization increase cooling loads. Yet demand is becoming more technical than routine. Singapore's district-cooling systems now require continuous refrigerant-leak detection and remote telemetry, which legacy preventive schedules cannot address. Malaysia's chiller retrofits come with energy-savings guarantees that shift risk to service vendors. IoT-enabled diagnostics are normalizing forty-eight-hour fault remediation windows, so providers must invest in analytics talent and spare-parts inventory. Without that capability, mid-tier contractors lose premium accounts to firms that can underwrite performance.
Skilled Technical-Labor Shortage
Labor scarcity is the most immediate brake on the Asia-Pacific hard facility management market. Singapore reported a 12% deficit of certified HVAC engineers in 2024. Australian electricians experienced 15% wage inflation, while Malaysia's construction sector faced a 15% headcount shortfall. Large integrators responded by opening training academies; ISS targets 500 graduates a year through its newly launched Southeast Asia center. Smaller companies lack the scale to replicate that model, so staff attrition funnels talent toward higher-paying data-center posts. The skills gap raises service costs and threatens SLA compliance, pushing buyers to favor vendors with formal workforce pipelines.
Other drivers and restraints analyzed in the detailed report include:
- Outsourcing Shift Toward Integrated FM Contracts
- Energy-Efficiency and Green-Building Regulation Push
- Grid-Capacity Shortfalls Delaying Facility Handovers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Asia-Pacific hard facility management market size for energy management and power systems is poised to reach a significant value, advancing at a 3.83% CAGR, well ahead of legacy HVAC services. Energy-management contracts increasingly include on-site renewables, battery storage, and digital twins that predict load variance. Buyers value verified savings, so vendors who can bundle metering, analytics, and performance guarantees command premium prices. In contrast, HVAC maintenance, although still holding 38.12% of the Asia-Pacific hard facility management market share in 2025, faces slower growth because much of the installed base is aging equipment awaiting phased replacement. Mechanical and electrical maintenance will remain foundational, yet commoditization is likely as IoT sensors reduce the need for routine inspections. Fire and life-safety system upkeep is gaining regulatory tailwinds, while plumbing services climb the agenda in water-stressed geographies..
Routine tasks, such as filter changes, are migrating toward outcome-based pricing, rewarding firms that invest in remote-monitoring hardware. Johnson Controls recorded a 25% jump in Asia-Pacific bookings for performance-guaranteed contracts in 2024, illustrating the link between financial innovation and market capture. Providers that cannot underwrite energy savings will cede ground to platforms with stronger balance sheets. The battle lines are therefore drawn between scale-driven integrators and niche experts who master high-value micro-segments like liquid cooling or greywater recycling.
Industrial and manufacturing customers are poised to add notable value through incremental spending, growing at a 4.18% CAGR as supply-chain diversification prompts factories to relocate to Vietnam, Indonesia, and India. Semiconductor fabs and pharma plants require cleanroom HVAC, ultra-pure water, and redundant power, lifting per-square-meter revenue well above that of office towers. In 2025, commercial buildings still accounted for 46.05% of outlays; however, their expansion rate lags behind because saturated CBDs and hybrid work arrangements temper new space demand. Healthcare and education budgets are rising as governments fund hospital refurbishments and research campuses, a trend that insulates cash flows from economic cycles.
Residential complexes remain largely in-house managed, though luxury towers in Singapore and Sydney are trialing predictive-maintenance outsourcing to differentiate amenities. For FM providers, industrial diversification creates a need for regional dispatch hubs, spare parts logistics, and specialized certifications. Those who invested early in local technician training and OEM partnerships are winning multi-year contracts at higher margins. Late movers face a steep learning curve and risk being locked out of complex industrial niches.
Complete Report Scope:
- By Service Type
- Mechanical Services Maintenance
- Electrical Services Maintenance
- HVAC Maintenance Services
- Fire and Life-Safety Systems Maintenance
- Plumbing and Water Management
- Building Fabric and Structural Maintenance
- Energy Management and Power Systems
- By End User
- Commercial
- Institutional (Education and Healthcare)
- Public / Infrastructure
- Industrial and Manufacturing
- Residential and Mixed-Use
- By Service Delivery Model
- In-House (Self-Performed)
- Outsourced Single-Service
- Integrated Facilities Management (IFM)
- Hybrid Models
- By Facility Type
- Office and Corporate Campuses
- Industrial and Logistics Facilities
- Data Centres and Critical Environments
- Healthcare Facilities
- Hospitality and Leisure Properties
- Transportation Hubs and Infrastructure
- By Country
- Australia
- China
- India
- Japan
- Indonesia
- Malaysia
- Singapore
- South Korea
- Taiwan
- Thailand
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Jones Lang LaSalle Incorporated
- CBRE Group, Inc.
- Sodexo S.A.
- ISS A/S
- Cushman and Wakefield plc
- Johnson Controls International plc
- Siemens AG
- Honeywell International Inc.
- Aden Group Limited
- Aeon Delight Co., Ltd.
- Ventia Services Group Limited
- OCS Group Limited
- Nippon Kanzai Co., Ltd.
- Brookfield Global Integrated Solutions Canada LP
- Downer Edi Limited (Facilities Management)
- Serco Group plc
- GDI Integrated Facility Services Inc.
- EMCOR Group, Inc.
- Atalian Global Services SAS
- Knight Facilities Management Ltd.
- BVG India Limited
- Sembcorp Facilities Management Pte Ltd.
- Mapletree Facilities Services Pte Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion Of Commercial And Industrial Construction Activity
- 4.2.2 Rising Demand For HVAC And MEP Maintenance Services
- 4.2.3 Outsourcing Shift Toward Integrated FM Contracts
- 4.2.4 Energy-Efficiency And Green-Building Regulation Push
- 4.2.5 Hyperscale Data-Centre Build-Out Driving Critical FM Needs
- 4.2.6 Corporate On-Site Renewable Targets And Micro-Grid Upkeep
- 4.3 Market Restraints
- 4.3.1 Skilled Technical-Labour Shortage
- 4.3.2 Volatile Energy And Materials Costs Squeezing Margins
- 4.3.3 Fragmented Asia-Pacific Compliance And Certification Landscape
- 4.3.4 Grid-Capacity Shortfalls Delaying Facility Handovers
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Mechanical Services Maintenance
- 5.1.2 Electrical Services Maintenance
- 5.1.3 HVAC Maintenance Services
- 5.1.4 Fire and Life-Safety Systems Maintenance
- 5.1.5 Plumbing and Water Management
- 5.1.6 Building Fabric and Structural Maintenance
- 5.1.7 Energy Management and Power Systems
- 5.2 By End User
- 5.2.1 Commercial
- 5.2.2 Institutional (Education and Healthcare)
- 5.2.3 Public / Infrastructure
- 5.2.4 Industrial and Manufacturing
- 5.2.5 Residential and Mixed-Use
- 5.3 By Service Delivery Model
- 5.3.1 In-House (Self-Performed)
- 5.3.2 Outsourced Single-Service
- 5.3.3 Integrated Facilities Management (IFM)
- 5.3.4 Hybrid Models
- 5.4 By Facility Type
- 5.4.1 Office and Corporate Campuses
- 5.4.2 Industrial and Logistics Facilities
- 5.4.3 Data Centres and Critical Environments
- 5.4.4 Healthcare Facilities
- 5.4.5 Hospitality and Leisure Properties
- 5.4.6 Transportation Hubs and Infrastructure
- 5.5 By Country
- 5.5.1 Australia
- 5.5.2 China
- 5.5.3 India
- 5.5.4 Japan
- 5.5.5 Indonesia
- 5.5.6 Malaysia
- 5.5.7 Singapore
- 5.5.8 South Korea
- 5.5.9 Taiwan
- 5.5.10 Thailand
- 5.5.11 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration Analysis
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Jones Lang LaSalle Incorporated
- 6.4.2 CBRE Group, Inc.
- 6.4.3 Sodexo S.A.
- 6.4.4 ISS A/S
- 6.4.5 Cushman and Wakefield plc
- 6.4.6 Johnson Controls International plc
- 6.4.7 Siemens AG
- 6.4.8 Honeywell International Inc.
- 6.4.9 Aden Group Limited
- 6.4.10 Aeon Delight Co., Ltd.
- 6.4.11 Ventia Services Group Limited
- 6.4.12 OCS Group Limited
- 6.4.13 Nippon Kanzai Co., Ltd.
- 6.4.14 Brookfield Global Integrated Solutions Canada LP
- 6.4.15 Downer Edi Limited (Facilities Management)
- 6.4.16 Serco Group plc
- 6.4.17 GDI Integrated Facility Services Inc.
- 6.4.18 EMCOR Group, Inc.
- 6.4.19 Atalian Global Services SAS
- 6.4.20 Knight Facilities Management Ltd.
- 6.4.21 BVG India Limited
- 6.4.22 Sembcorp Facilities Management Pte Ltd.
- 6.4.23 Mapletree Facilities Services Pte Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026-2030年全球設施管理市場
 設施管理(FM)軟體:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)北美設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)硬設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)日本設施管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 Frost Radar™:泰國設施管理,2026 年中國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)印尼設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)新加坡設施管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)