


 |
市場調查報告書
商品編碼
2124283
IT人員配備服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)IT Staffing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
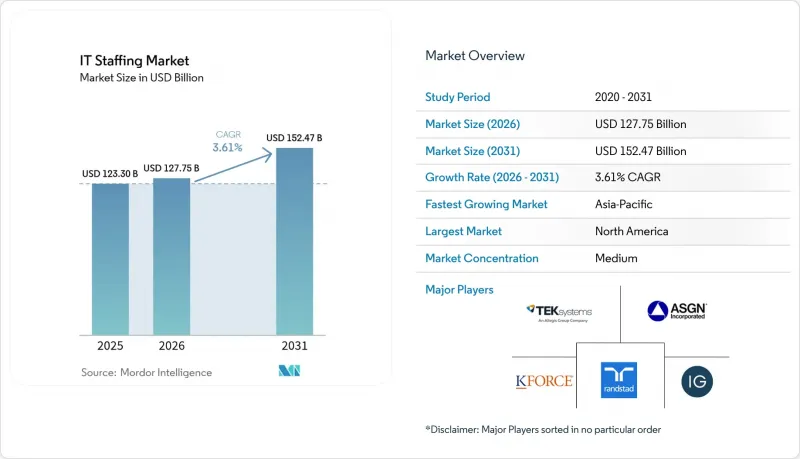
根據 Mordor Intelligence 預測,IT 人員配置市場規模將從 2025 年的 1,233 億美元成長到 2026 年的 1,277.5 億美元,然後在 2031 年達到 1,524.7 億美元,2026 年至 2031 年的複合年成長率為 3.61%。
本報告按技能類別(軟體開發人員、測試人員/品質保證工程師、系統分析師、技術支援負責人、網路安全專家等)、最終用戶產業(電信、銀行、金融服務和保險等)、人員配備服務類型(合約人員配備等)、公司規模(大型企業、中小企業)和地區進行細分。市場預測以美元計價。
全球IT人員配置市場的趨勢與洞察
加速採用以人工智慧、雲端運算和物聯網為中心的數位轉型(DX)專案。
目前,全球14%的技術相關職位招募資訊要求具備人工智慧或機器學習技能,高於去年同期的9%。雲端遷移需要專業的DevOps工程師和安全架構師,而預計到2030年將達到1,395.8億美元的邊緣運算投資,則需要同時具備基礎設施和物聯網能力的人才。 NTT DATA公司所進行的20萬名員工生成式人工智慧培訓項目,進一步凸顯了持續再學習的規模。因此,能夠連接人工智慧演算法、雲端資源和設備網路的跨學科企劃團隊,正在推動IT人才市場的持續成長。
遠距和混合工作模式的擴展需要分散式人才
戴爾科技公司65%的員工採用正式的彈性工作安排,顯示以地域為基礎的招募模式正逐漸普及。雇主在獲得更廣泛的人才庫的同時,也必須應對跨境合規問題以及日益成長的縮小薪資差距的期望。根據萬寶盛華集團(ManpowerGroup)發布的2025年展望報告,41%的公司計劃擴大員工規模,其中技術職位的需求量位居榜首。隨著跨洲競爭競標和薪資水準的不斷提高,招聘機構不得不加強人才保留策略,而這些策略的考量也不僅限於薪資。
全球小眾技術領域的技能短缺問題依然存在。
預計到2034年,尚未解決的數位技能缺口將對全球經濟造成重大損失,凸顯了量子技術、先進人工智慧和零信任安全等領域專業人才的結構性供應限制。大學在更新課程方面進展緩慢,導致應屆畢業生進入這些專業領域需要數年時間。人才短缺迫使企業投入大量資源進行技能再舉措,而隨著薪資待遇的提高和專案週期的延長,這些投入會降低短期投資報酬率。
細分市場分析
到2025年,軟體開發人員將佔IT人員市場37.05%的佔有率,這反映了成熟的應用現代化專案。生成式人工智慧工程師預計到2031年將以11.75%的複合年成長率成長,凸顯了對快速設計、模型審計和LLM微調日益成長的需求。隨著邊緣雲端管道的擴展,數據和人工智慧工程領域的IT人員市場規模預計將快速成長。薪資水準反映了服務提供者在提供混合人工智慧開發專業知識時可以收取的溢價。
傳統測試人員和品質保證負責人正面臨自動化帶來的挑戰,許多專家正在轉向使用人工智慧驅動的檢驗工具。系統分析師正朝著整合架構方向發展,網路專家也正在提升自身在人工智慧驅動的威脅監控方面的技能。新興技能(量子開發、區塊鏈架構、物聯網設備安全)雖然整體規模仍然較小,但卻是IT人才市場中快速成長的領域。
銀行、金融和保險(BFSI)產業仍是最大的應用產業,預計到2025年將佔據24.15%的市場佔有率,這主要得益於開放銀行合規性和金融科技平台的升級。醫療保健產業則成為成長最快的產業,複合年成長率(CAGR)達到10.25%,這主要得益於電子健康記錄的現代化和人工智慧診斷技術的進步。隨著遠端醫療和患者資料互通性標準的逐步建立,醫療保健項目IT人員配備市場預計將會擴大。
在製造業領域,採用需要物聯網和預測性維修技能的智慧工廠是當務之急。零售和電子商務產業持續拓展全通路策略,而公共機構則為網路安全和公共服務的數位化分配預算。 「其他」類別涵蓋能源、汽車和智慧城市項目,每個領域都需要獨特的技能組合,並為IT人才市場提供多元化的人才供應。
區域分析
北美憑藉著強大的科技生態系統、巨額的數位化預算和嚴格的安全要求,在2025年維持了44.05%的市場佔有率。簽證政策的不斷變化和工資的上漲使得人才獲取更加困難,導致越來越多的業務外包到加拿大和拉丁美洲。美國憑藉矽谷的軟體專案和華爾街的雲端現代化改造推動了市場需求,而加拿大則在多倫多和蒙特婁等地提供了具有成本競爭力的樞紐。
亞太地區是成長最快的地區,年複合成長率達8.15%,這主要得益於印度IT服務業務的擴張、日本的技能再培訓舉措以及新加坡對區域總部的吸引力。隨著跨國公司採購管道的多元化,預計到2024年,該地區管理服務的年度合約價值將增加32%。中國平台業務的復甦以及韓國半導體研發的蓬勃發展,進一步推動了對技術人才的需求。
在歐洲,儘管東歐的中心已從單純的成本套利中心發展成為利基專業中心,但德國和英國的需求仍保持穩定。由於一般資料保護規則,網路安全採用率仍然很高。中東和非洲雖然成長滯後,但也保持穩定成長,其中沙烏地阿拉伯的智慧城市計畫和南非的英語服務中心是顯著的需求熱點。這些市場外匯調整後的薪資差距影響全球IT人員配置市場供應商的利潤率策略。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場洞察
- 市場概覽
- 市場促進因素
- 以人工智慧、雲端運算和物聯網為中心的數位轉型專案正在加速推進。
- 遠距和混合工作模式的擴展需要分散式人才
- 隨著網路保險成為強制性保險,對網路安全防護專業人員的需求激增。
- 疫情後數位轉型預算的恢復,正在推動對人才的需求成長。
- 監督生成式人工智慧(提示工程師、模型負責人)的角色正在逐漸形成。
- 為全球企業(多達 2,000 家企業)提供服務的供應商之間的整合正在推動 MSP主導的大規模交易的擴張。
- 市場限制因素
- 全球小眾科技領域的人才短缺問題依然存在。
- 薪資上漲給託管服務提供者 (MSP) 的計費利潤率帶來了壓力。
- 人工智慧驅動的自助招聘平台消除了招聘機構的中間環節。
- 更嚴格的資料主權法律限制了跨境人才的部署。
- 價值鏈分析
- 監理情勢
- 技術展望
- 五力分析
- 供應商的議價能力
- 買方的議價能力
- 新進入者的威脅
- 替代品的威脅
- 競爭公司之間的競爭
- 產業生態系分析
- 主要用例和範例
- 宏觀經濟趨勢評估
- 投資分析
第5章 市場區隔
- 按技能集
- 軟體開發者
- 測試員/品質保證工程師
- 系統分析師/業務分析師
- 技術支援負責人
- 網路安全專家
- 數據與人工智慧工程師
- 其他技能
- 按最終用戶行業分類
- 溝通
- 銀行、金融服務和保險(BFSI)
- 醫療保健和生命科學
- 製造業
- 零售與電子商務
- 政府/公共部門
- 其他
- 按臨時人員配備服務類型
- 臨時人員配備及合約制人員派遣
- 全職員工安置
- 工作說明書(SOW)/企劃為基礎
- 託管服務供應商(MSP) / 外包型人員配備
- 按公司規模
- 大公司
- 小型企業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 澳洲
- 新加坡
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- TEKsystems Inc.(Allegis Group Holdings Inc.)
- ASGN Incorporated
- Insight Global LLC
- Randstad NV
- Kforce Inc.
- Artech Information Systems LLC
- Consulting Solutions International Inc.
- MATRIX Resources Inc.
- NTT DATA Corporation
- Beacon Hill Staffing Group LLC
- Experis IT(ManpowerGroup Global Inc.)
- Akkodis(Adecco Group AG)
- Kelly Services Inc.
- Motion Recruitment Partners LLC
- Robert Half International Inc.
- Genesis10 Inc.
- Collabera LLC
- PERSOL Holdings Co., Ltd.
- Aquent LLC
- CGI Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the IT staffing market size is expected to grow from USD 123.30 billion in 2025 to USD 127.75 billion in 2026 and is forecast to reach USD 152.47 billion by 2031 at 3.61% CAGR over 2026-2031.
This report is Segmented by Skill Set (Software Developer, Testers and QA Engineers, Systems Analyst, Technical Support Professionals, Networking and Security Experts, and More), End-User Industry (Telecom, BFSI, and More), Staffing Service Type (Contract Staffing, and More), Enterprise Size (Large Enterprises, and SMEs), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global IT Staffing Market Trends and Insights
Accelerated Adoption of AI-, Cloud- and IoT-Centric Digital-Transformation Projects
Fourteen percent of global tech job postings now demand AI or machine-learning skills, up from 9% a year earlier . Cloud migrations call for specialized DevOps engineers and security architects, while edge-computing investments that are projected to reach USD 139.58 billion by 2030 require blended infrastructure-plus-IoT talent. NTT DATA's program to train 200,000 employees in generative AI further underscores the scale of reskilling underway . Interdisciplinary project teams that connect AI algorithms, cloud resources, and device networks are therefore driving sustained expansion in the IT staffing market.
Expansion of Remote and Hybrid Work Models Requiring Distributed Talent
Sixty-five percent of Dell Technologies personnel use formal flexibility arrangements, signaling lasting normalization of location-agnostic hiring. Employers gain access to broader talent pools, yet must navigate cross-border compliance and rising pay parity expectations. ManpowerGroup's 2025 outlook shows 41% of firms plan to add headcount, with technology roles topping demand charts. Competitive bidding now spans continents, increasing compensation levels and compelling agencies to enhance retention packages that extend beyond salary.
Persistent Global Skill Shortages in Niche Technologies
It is estimates that unresolved digital-skills gaps could cost the global economy by 2034, underscoring structural supply constraints for quantum, advanced AI, and zero-trust security expertise. Universities have not kept curriculum pace, creating multiyear lags before new graduates enter these specializations. The scarcity elevates compensation packages and lengthens project timelines, compelling enterprises to bankroll intensive reskilling initiatives that erode near-term ROI.
Other drivers and restraints analyzed in the detailed report include:
- Surging Demand for Cyber-Resilience Staff Driven by Cyber-Insurance Mandates
- Digital-Transformation Budget Rebound Post-Pandemic Fuels Staff-Augmentation Demand
- Wage Inflation Compressing MSP Bill-Rate Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software developers accounted for 37.05% of IT staffing market share in 2025, reflecting entrenched application modernization projects. Generative-AI engineers are projected to register a 11.75% CAGR through 2031, underscoring growing demand for prompt design, model auditing, and LLM fine-tuning. The IT staffing market size for data and AI engineering is projected to escalate sharply as edge-cloud pipelines scale. Salary corridors signal premium pricing that providers can command when supplying hybrid AI-development expertise.
Traditional testers and QA roles face automation headwinds, pushing many professionals toward AI-enabled verification tools. Systems analysts are pivoting to integration architecture, and network specialists are upskilling in AI-driven threat monitoring. Emerging skills-quantum development, blockchain architecture, and IoT device security-collectively remain a small but rapidly expanding slice of the IT staffing market.
BFSI remained the largest adopter with 24.15% share in 2025, driven by open-banking compliance and fintech platform upgrades. Healthcare emerges as the fastest-growing vertical at 10.25% CAGR, propelled by electronic-health-record modernization and AI-assisted diagnostics. The IT staffing market size for healthcare projects is expected to widen as telemedicine and patient-data interoperability standards take hold.
Manufacturing prioritizes smart-factory deployments requiring IoT and predictive-maintenance talent. Retail and e-commerce continue omnichannel build-outs, while public sector agencies earmark cybersecurity and citizen-service digitization budgets. Energy, automotive, and smart-city programs fill the "Other Industries" category, each demanding bespoke skill combinations and feeding diverse pipelines for the IT staffing market.
Complete Report Scope:
- By Skill Set
- Software Developers
- Testers and QA Engineers
- Systems Analysts / Business Analysts
- Technical Support Professionals
- Networking and Security Experts
- Data and AI Engineers
- Other Skill Sets
- By End-User Industry
- Telecom
- Banking, Financial Services and Insurance (BFSI)
- Healthcare and Life Sciences
- Manufacturing
- Retail and e-Commerce
- Government and Public Sector
- Other Industries
- By Staffing Service Type
- Temporary / Contract Staffing
- Permanent Placement
- Statement-of-Work (SOW) / Project-based
- Managed Service Provider (MSP) / Outsourced Staffing
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Singapore
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 44.05% share in 2025, supported by deep tech ecosystems, large digital budgets, and rigorous security mandates. Continuous visa policy shifts and wage escalation challenge talent availability, prompting more near-shoring to Canada and Latin America. The United States leads demand due to Silicon Valley software projects and Wall Street cloud overhauls, while Canada provides cost-advantaged hubs in Toronto and Montreal.
Asia-Pacific is the fastest-growing region at an 8.15% CAGR, buoyed by India's IT services scale-up, Japanese reskilling initiatives, and Singapore's regional headquarters attraction. Managed-services annual contract value in the region rose 32% in 2024 as multinationals diversified sourcing. China's platform rebound and Korea's semiconductor R&D add further pull on specialist headcount.
Europe posts stable demand in Germany and the United Kingdom, even as Eastern European destinations evolve from pure cost-arbitrage to niche specialist centers. GDPR compliance maintains high cybersecurity uptake. Middle East and Africa trail but register steady growth; Saudi Arabia's smart-city projects and South Africa's English-language service hubs are notable demand pockets. Currency-adjusted wage differentials across these markets shape provider margin strategies within the global IT staffing market.
- TEKsystems Inc. (Allegis Group Holdings Inc.)
- ASGN Incorporated
- Insight Global LLC
- Randstad N.V.
- Kforce Inc.
- Artech Information Systems LLC
- Consulting Solutions International Inc.
- MATRIX Resources Inc.
- NTT DATA Corporation
- Beacon Hill Staffing Group LLC
- Experis IT (ManpowerGroup Global Inc.)
- Akkodis (Adecco Group AG)
- Kelly Services Inc.
- Motion Recruitment Partners LLC
- Robert Half International Inc.
- Genesis10 Inc.
- Collabera LLC
- PERSOL Holdings Co., Ltd.
- Aquent LLC
- CGI Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET INSIGHTS
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated adoption of AI-, Cloud- and IoT-centric digital-transformation projects
- 4.2.2 Expansion of remote and hybrid work models requiring distributed talent
- 4.2.3 Surging demand for cyber-resilience staff driven by cyber-insurance mandates
- 4.2.4 Digital-transformation budget rebound post-pandemic fuels staff-augmentation demand
- 4.2.5 Generative-AI supervision roles (prompt engineers, model auditors) emerge
- 4.2.6 Vendor consolidation among Global-2000 clients boosts MSP-led volume deals
- 4.3 Market Restraints
- 4.3.1 Persistent global skill shortages in niche technologies
- 4.3.2 Wage inflation compressing MSP bill-rate margins
- 4.3.3 AI-based self-service hiring platforms disintermediate agencies
- 4.3.4 Tightening data-sovereignty laws restrict cross-border staff deployment
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porterss Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Industry Ecosystem Analysis
- 4.9 Key Use Cases and Case Studies
- 4.10 Assessment of Macroeconomic Trends
- 4.11 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Skill Set
- 5.1.1 Software Developers
- 5.1.2 Testers and QA Engineers
- 5.1.3 Systems Analysts / Business Analysts
- 5.1.4 Technical Support Professionals
- 5.1.5 Networking and Security Experts
- 5.1.6 Data and AI Engineers
- 5.1.7 Other Skill Sets
- 5.2 By End-User Industry
- 5.2.1 Telecom
- 5.2.2 Banking, Financial Services and Insurance (BFSI)
- 5.2.3 Healthcare and Life Sciences
- 5.2.4 Manufacturing
- 5.2.5 Retail and e-Commerce
- 5.2.6 Government and Public Sector
- 5.2.7 Other Industries
- 5.3 By Staffing Service Type
- 5.3.1 Temporary / Contract Staffing
- 5.3.2 Permanent Placement
- 5.3.3 Statement-of-Work (SOW) / Project-based
- 5.3.4 Managed Service Provider (MSP) / Outsourced Staffing
- 5.4 By Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Netherlands
- 5.5.3.8 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 Singapore
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 TEKsystems Inc. (Allegis Group Holdings Inc.)
- 6.4.2 ASGN Incorporated
- 6.4.3 Insight Global LLC
- 6.4.4 Randstad N.V.
- 6.4.5 Kforce Inc.
- 6.4.6 Artech Information Systems LLC
- 6.4.7 Consulting Solutions International Inc.
- 6.4.8 MATRIX Resources Inc.
- 6.4.9 NTT DATA Corporation
- 6.4.10 Beacon Hill Staffing Group LLC
- 6.4.11 Experis IT (ManpowerGroup Global Inc.)
- 6.4.12 Akkodis (Adecco Group AG)
- 6.4.13 Kelly Services Inc.
- 6.4.14 Motion Recruitment Partners LLC
- 6.4.15 Robert Half International Inc.
- 6.4.16 Genesis10 Inc.
- 6.4.17 Collabera LLC
- 6.4.18 PERSOL Holdings Co., Ltd.
- 6.4.19 Aquent LLC
- 6.4.20 CGI Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 醫療人員強化與外派市場:策略性洞察與預測(2026-2031)
 人才招聘軟體:市佔率分析、產業趨勢與統計、成長預測(2026-2031)歐洲IT人員配置:市場佔有率分析、產業趨勢與統計數據以及成長預測(2026-2031年)
 數位人才招聘市場:按組件、技術類型、最終用戶、部署模式、產業和應用分類-2026-2032年全球市場預測IT永續發展人才與培訓平台:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)亞太地區人才招聘軟體:市佔率分析、產業趨勢與統計及成長預測(2026-2031)北美人才招聘軟體:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)醫療保健產業人才招聘:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)銀行、金融服務和保險 (BFSI) 市場的人才招聘:市場佔有率分析、行業趨勢和統計數據以及成長預測 (2026-2031)
 人才招募技術與服務市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶與功能分類