


 |
市場調查報告書
商品編碼
2121443
農業灌溉機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Agricultural Irrigation Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
2025年農業灌溉機械市場價值為76億美元,預計從2026年的80.1億美元成長到2031年的103.9億美元,預測期(2026-2031年)複合年成長率預計為5.34%。
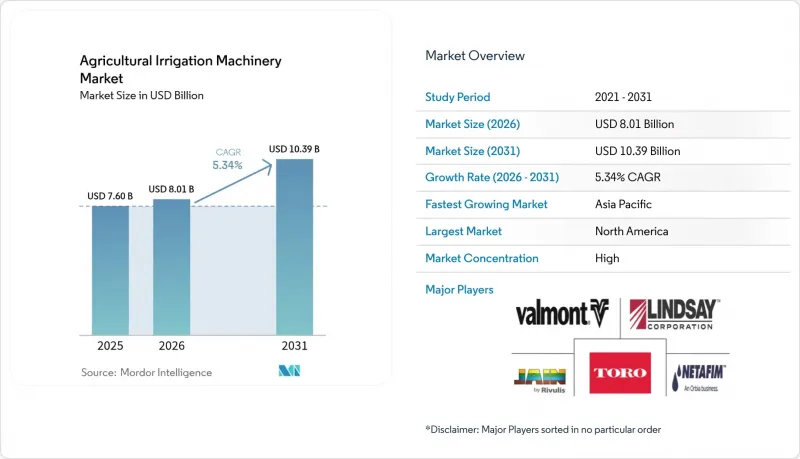
本報告按灌溉方式(噴水灌溉、滴灌、中心支軸式噴灌及其他灌溉方式)、應用領域(穀物、豆類和油籽、水果和蔬菜及其他應用領域)以及地區(北美、歐洲、亞太、南美以及中東和非洲)進行細分。市場預測以美元計價。
全球農業灌溉機械市場趨勢及洞察
政府對推廣微灌技術提供補貼
聯邦政府增加的保護資金降低了中型農戶的前期成本。在2024會計年度,美國農業部(USDA)的環境品質獎勵計畫(EQIP)為節能改造舉措提供了高達75%的系統維修成本補貼。通膨控制法案提供的多年期擔保鼓勵製造商擴大產能,而基於結果的指標則確保供應商的產品符合政策目標。該計劃著重可衡量的節水效果,這與製造商的精密農業技術相契合,使技術整合解決方案具有競爭優勢。這些獎勵顯著提高了發送器供應商的年度訂單,預示著農業灌溉機械市場將持續受益。
水資源短缺日益嚴重,推動了對精準灌溉的需求不斷成長。
隨著節水措施從自願性到強制性報告的轉變,配備感測器的系統變得至關重要。由於許多地區正在實施更嚴格的用水報告要求,經濟因素已不再局限於水費,而是擴展到合規性。能提供詳細用水量分析的精準灌溉系統,不僅成為提高效率的選擇,更成為合規的必備工具。結合田間試驗以及地下滴灌作為蒸散量(ET)替代方案的節水效果,越來越多的經驗數據正在積累,為精準灌溉提案的農藝價值和監管價值提供有力支撐。
樞軸系統的初始投資成本高
中心支軸式噴灌機每台造價超過10萬美元,安裝成本還要額外增加30%,這造成了巨大的資金缺口,傳統融資方式很難承擔。尤其是在二手設備市場不發達的地區,殘值的不確定性導致租賃使用率低於15%。這些資金壁壘促使人們關注將中心支軸式噴灌系統與側向滴灌結合的混合系統。這種混合系統允許生產者在多個生長季節分階段進行投資,並隨著土地所有權的穩定靈活調整灌溉覆蓋範圍。此外,混合系統具有高度擴充性性,使農民無需預付資金即可逐步擴大灌溉擁有情形,從而成為資源有限的生產者更現實的選擇。
細分市場分析
滴灌佔最大佔有率,預計到2025年將佔農業灌溉機械市場46.0%的佔有率,遠超市場平均水準。加州鼓勵計量灌溉的報告法規以及印度對發送器、管道和過濾器的補貼是推動滴灌市場成長的主要因素。包括滴灌組件在內的農業灌溉機械市場預計將持續擴張,這主要得益於對濕度感測器和變數控制器的需求不斷成長。雖然發送器和管道仍佔據大部分銷售額,但隨著農場從均勻灌溉轉向數據驅動的灌溉調度,感測器已成為成長最快的細分市場。
噴水灌溉是成長最快的細分市場,預計到2031年將以8.0%的複合年成長率成長。成熟的分銷網路有助於維持銷售量,而新增銷售額正轉向整合土壤探針和流量計的可變流量配置。美國中西部地區的田間試驗表明,將中心支軸式噴灌系統從固定供水改為可變供水,可以在不降低產量的情況下節水15%至25%。組件創新主要集中在快速連接接頭和自清潔過濾器上,這些創新可將安裝時間縮短30%至40%。同時,隨著水資源短缺措施日益嚴格,其他灌溉方式(如地表灌溉和溝渠灌溉)的總合佔有率已不足10%。
區域分析
北美是最大的市場區域,預計到2025年將佔全球32.1%。由於大部分可灌溉農地已接上中心支軸式噴灌系統,系統升級改造十分普遍。加州參議院第88號法案等監管合規要求正在推動維修,以整合流量計和遙測系統。亞利桑那州的津貼有助於彌補額外感測器的資金缺口,並在中心支軸式噴灌系統銷售量停滯不前的情況下維持其獲利能力。預計加拿大草原省份和墨西哥巴希奧地區的市場將逐步成長,但這些地區的市場需求仍僅占美國總需求的一小部分。
預計到2031年,亞太地區將以8.0%的複合年成長率成為所有地區中成長最快的地區。由於小規模農場的多樣化程度不斷提高,每公頃售價低於800美元的模組化滴灌設備的銷售量是大型中心支軸式噴灌系統的四倍。日本溫室種植業的蓬勃發展也為市場帶來了利好,推動了對高壓滴灌和施肥灌溉控制器的需求,這些設備在農業灌溉機械市場中利潤豐厚。
在歐洲,通用農業政策(CAP)的環境部分認可精準灌溉是一項永續活動,並符合綠色金融的條件,因此精準灌溉正穩定成長。在地中海地區,反覆的乾旱加速了地下灌溉系統的普及,而荷蘭和德國等國則專注於封閉回路型溫室灌溉系統。在中東和非洲,政府支持的大型農場和氣候智慧型農業走廊正在推動市場需求。同時,在南美洲的大豆產區,為緩解降雨波動,對中心支軸式噴灌系統的投資不斷增加,有助於農業灌溉機械市場形成地域多元化的收入來源。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府對推廣微灌技術提供補貼
- 水資源短缺日益嚴重,精準灌溉的需求也隨之增加。
- 由於人手不足,中型農場的機械化正在加速。
- 物聯網感測器的整合實現了基於成長的收費模式。
- 環境、社會和管治(ESG) 相關金融正在促進對水資源效率的投資。
- 節水科技的排碳權計畫激增。
- 市場限制因素
- 樞軸式旋轉系統的初始資本投資成本相對較高。
- 在開發中國家,土地所有權的分散限制了資本投資的報酬率(ROI)。
- 人們越來越關注滴灌管產生的塑膠廢棄物
- 互聯灌溉網路中的網路漏洞
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過灌溉法
- 噴水灌溉
- 水泵設備
- 管道
- 耦合器
- 噴頭或噴灌頭
- 配件和附件
- 感應器
- 控制器
- 注射器
- 流量計
- 滴灌
- 閥門
- 回流防止裝置
- 壓力調節器
- 篩選
- 發送器
- 管道
- 其他滴灌組件
- 中心支線灌溉
- 其他灌溉方法
- 噴水灌溉
- 按應用程式類型
- 穀物和穀類
- 豆類和油籽
- 水果和蔬菜
- 其他用途
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 其他北美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 荷蘭
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 柬埔寨
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 秘魯
- 其他南美國家
- 中東
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Netafim Ltd.(Orbia Advance Corporation)
- Valmont Industries, Inc.(Valley Irrigation)
- Lindsay Corporation
- Jain Irrigation Systems Limited(Rivulis Irrigation Limited)
- The Toro Company
- Nelson Irrigation Corporation
- Rain Bird Corporation
- Mahindra & Mahindra Limited
- Hunter Industries Incorporated
- Reinke Manufacturing Company, Inc.
- Ningbo Rainfine Irrigation Co., Ltd.
- TL Irrigation Company
- Sistemas Azud, SA
- Antelco Pty Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the agricultural irrigation machinery market size was valued at USD 7.60 billion in 2025 and estimated to grow from USD 8.01 billion in 2026 to reach USD 10.39 billion by 2031, at a CAGR of 5.34% during the forecast period (2026-2031).
This report is Segmented by Irrigation Type (Sprinkler Irrigation, Drip Irrigation, Pivot Irrigation, and Other Irrigation Types), by Application Type (Grains and Cereals, Pulses and Oilseeds, Fruits and Vegetables, and Other Applications), and by Geography (North America, Europe, Asia-Pacific, South America, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Agricultural Irrigation Machinery Market Trends and Insights
Government Subsidies for Micro-irrigation Adoption
Increased federal conservation funding has made upfront costs more manageable for medium-scale growers. In fiscal year 2024, the United States Department of Agriculture (USDA) Environmental Quality Incentives Program covered up to 75% of system expenses to efficiency initiatives upgrades. The multi-year guarantees provided by the Inflation Reduction Act encourage manufacturers to expand production capacity, while outcome-based metrics align vendor offerings with policy objectives. The program's focus on measurable water-saving outcomes aligns with manufacturers' precision agriculture capabilities, offering a competitive advantage for technology-integrated solutions. These incentives have sparked significant annual order growth among emitter suppliers, signaling durable tailwinds for the agricultural irrigation machinery market.
Rising Water Scarcity Pushing Demand for Precision Irrigation
Mandatory reporting is replacing voluntary conservation, making sensor-equipped systems indispensable. The economic considerations extend beyond water costs to encompass regulatory compliance, as many jurisdictions enforce stricter water-use reporting requirements. The precision irrigation systems' ability to deliver detailed consumption analytics makes them essential tools for compliance rather than optional efficiency enhancements. Coupled with field trials, water savings from subsurface drip Evapotranspiration (ET) replacement, the evidence base now supports both agronomic and regulatory value propositions.
High Upfront Capital Cost for Pivot Systems
Center pivots surpass USD 100,000 per unit, and installation can add another 30%, creating a financing gap that traditional credit seldom fills. Leasing uptake is under 15% because residual values remain opaque, especially in markets lacking secondary equipment exchanges. The capital barrier is also driving interest in hybrid systems that combine pivot infrastructure with drip laterals, allowing growers to phase investment over multiple growing seasons while maintaining flexibility to adjust coverage area as land tenure stabilizes. These systems enable growers to spread investments across multiple growing seasons while retaining the flexibility to modify coverage areas as land tenure becomes more stable. Additionally, hybrid systems offer a scalable approach, allowing farmers to gradually expand irrigation coverage without committing to the full cost upfront, making them a more viable option for resource-constrained growers.
Other drivers and restraints analyzed in the detailed report include:
- Labor Shortages are Accelerating the Mechanization of Mid-size Farms
- Integration of IoT Sensors Enabling Pay-as-You-Grow Service Models
- Growing Concern over Plastic Waste from Drip Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Drip irrigation held the largest share, accounting for 46.0% of the agricultural irrigation machinery market in 2025, well above the market average. Drip irrigation's market growth is supported by California's reporting regulations favoring metered delivery and India's subsidies for emitters, tubing, and filters. The agricultural irrigation machinery market for drip irrigation components is anticipated to expand, fueled by increasing demand for moisture sensors and variable-rate controllers. While emitters and tubing continue to generate the majority of revenue, sensors represent the fastest-growing segment as farms transition from uniform to data-driven irrigation scheduling.
Sprinkler irrigation is the fastest-growing segment, projected to advance at an 8.0% CAGR through 2031, while mature dealer networks help preserve volumes, new sales skew toward variable-rate configurations that integrate soil probes and flow meters. Field trials in the United States Midwest show 15%-25% water cutbacks without yield loss when pivots shift from fixed to variable-rate application . Component innovation focuses on quick-connect couplers and self-cleaning filters, trimming installation labor by 30%-40%. Other methods, such as surface and furrow, are slipping below 10% combined share as water-scarcity policies tighten.
Complete Report Scope:
- By Irrigation Type
- Sprinkler Irrigation
- Pumping Unit
- Tubing
- Couplers
- Spray or Sprinkler Heads
- Fittings and Accessories
- Sensors
- Controllers
- Injectors
- Flow Meters
- Drip Irrigation
- Valves
- Backflow Preventers
- Pressure Regulators
- Filters
- Emitters
- Tubing
- Other Drip Irrigation Components
- Pivot Irrigation
- Other Irrigation Types
- Sprinkler Irrigation
- By Application Type
- Grains and Cereals
- Pulses and Oilseeds
- Fruits and Vegetables
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Netherlands
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Cambodia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Peru
- Rest of South America
- Middle East
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America was the largest region, with 32.1% in 2025. Upgrades dominate because most irrigable acreage is already networked with pivots. Compliance mandates such as California's Senate Bill 88 fuel retrofits that integrate flow meters and telemetry. Arizona's grants are bridging the capital gap for sensor add-ons, sustaining pivot margins even as unit volumes plateau. Canada's Prairie Provinces and Mexico's Bajio region offer incremental growth but still account for only a fraction of the United States' demand.
Asia-Pacific is set to log the fastest-growing regional CAGR at 8.0% through 2031. Smallholder fragmentation means modular drip kits priced under USD 800 per hectare outsell large pivots by 4:1. Japan's greenhouse boom is another tailwind, driving demand for high-pressure drip and fertigation controllers that command premium margins in the agricultural irrigation machinery market.
Europe is experiencing steady growth under the environmental pillar of the Common Agricultural Policy, which recognizes precision irrigation as a sustainable activity eligible for green financing. In the Mediterranean region, recurring droughts are accelerating the adoption of subsurface irrigation systems, while countries like the Netherlands and Germany focus on closed-loop greenhouse irrigation systems. In the Middle East and Africa, demand is driven by state-supported megafarms and climate-smart agricultural corridors. Meanwhile, South America's soybean-producing regions are investing in pivot irrigation systems to mitigate rainfall variability, contributing to a geographically diversified revenue stream within the agricultural irrigation machinery market.
- Netafim Ltd. (Orbia Advance Corporation)
- Valmont Industries, Inc. (Valley Irrigation)
- Lindsay Corporation
- Jain Irrigation Systems Limited (Rivulis Irrigation Limited)
- The Toro Company
- Nelson Irrigation Corporation
- Rain Bird Corporation
- Mahindra & Mahindra Limited
- Hunter Industries Incorporated
- Reinke Manufacturing Company, Inc.
- Ningbo Rainfine Irrigation Co., Ltd.
- T-L Irrigation Company
- Sistemas Azud, S.A.
- Antelco Pty Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government subsidies for micro-irrigation adoption
- 4.2.2 Rising water scarcity is pushing demand for precision irrigation
- 4.2.3 Labor shortages are accelerating the mechanization of mid-size farms
- 4.2.4 Integration of IoT sensors enabling pay-as-you-grow service models
- 4.2.5 Environmental, Social, and Governance (ESG)-linked finance rewarding water-efficiency investments
- 4.2.6 Surge in carbon-credit schemes for water-saving technologies
- 4.3 Market Restraints
- 4.3.1 High upfront capital cost for pivot systems
- 4.3.2 Fragmented land holdings limiting equipment Return on investment (ROI) in developing countries
- 4.3.3 Growing concern over plastic waste from drip lines
- 4.3.4 Cyber-vulnerability of connected irrigation networks
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of Substitute Products
- 4.6.4 Threat of New Entrants
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Irrigation Type
- 5.1.1 Sprinkler Irrigation
- 5.1.1.1 Pumping Unit
- 5.1.1.2 Tubing
- 5.1.1.3 Couplers
- 5.1.1.4 Spray or Sprinkler Heads
- 5.1.1.5 Fittings and Accessories
- 5.1.1.6 Sensors
- 5.1.1.7 Controllers
- 5.1.1.8 Injectors
- 5.1.1.9 Flow Meters
- 5.1.2 Drip Irrigation
- 5.1.2.1 Valves
- 5.1.2.2 Backflow Preventers
- 5.1.2.3 Pressure Regulators
- 5.1.2.4 Filters
- 5.1.2.5 Emitters
- 5.1.2.6 Tubing
- 5.1.2.7 Other Drip Irrigation Components
- 5.1.3 Pivot Irrigation
- 5.1.4 Other Irrigation Types
- 5.1.1 Sprinkler Irrigation
- 5.2 By Application Type
- 5.2.1 Grains and Cereals
- 5.2.2 Pulses and Oilseeds
- 5.2.3 Fruits and Vegetables
- 5.2.4 Other Applications
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.1.4 Rest of North America
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Netherlands
- 5.3.2.6 Russia
- 5.3.2.7 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 Cambodia
- 5.3.3.5 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Peru
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Turkey
- 5.3.5.3 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Egypt
- 5.3.6.3 Rest of Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-level Overview, Market-level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank or Share, Products and Services, and Recent Developments)
- 6.4.1 Netafim Ltd. (Orbia Advance Corporation)
- 6.4.2 Valmont Industries, Inc. (Valley Irrigation)
- 6.4.3 Lindsay Corporation
- 6.4.4 Jain Irrigation Systems Limited (Rivulis Irrigation Limited)
- 6.4.5 The Toro Company
- 6.4.6 Nelson Irrigation Corporation
- 6.4.7 Rain Bird Corporation
- 6.4.8 Mahindra & Mahindra Limited
- 6.4.9 Hunter Industries Incorporated
- 6.4.10 Reinke Manufacturing Company, Inc.
- 6.4.11 Ningbo Rainfine Irrigation Co., Ltd.
- 6.4.12 T-L Irrigation Company
- 6.4.13 Sistemas Azud, S.A.
- 6.4.14 Antelco Pty Ltd.
7 Market Opportunities and Future Outlook

 2026-2030年全球自動化灌溉系統市場
 人工智慧驅動的灌溉控制系統市場預測至2034年-全球分析(按感測器類型、灌溉系統、農場類型、應用、最終用戶和地區分類)
 噴水灌溉系統市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 美國農業灌溉機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)非洲農業灌溉機械:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)德國農業灌溉機械:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美農業灌溉機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 噴水灌溉系統市場:按類型、組件、移動性、作物類型、自動化程度、水源、最終用戶和分銷管道分類-2026-2032年全球市場預測自主灌溉控制系統市場預測至2034年:全球分析(按組件、灌溉方式、農場類型、技術、應用、最終用戶和地區分類)
 灌溉機械市場:按類型、應用和地區分類