


 |
市場調查報告書
商品編碼
2119863
越南資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Vietnam Data Center Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
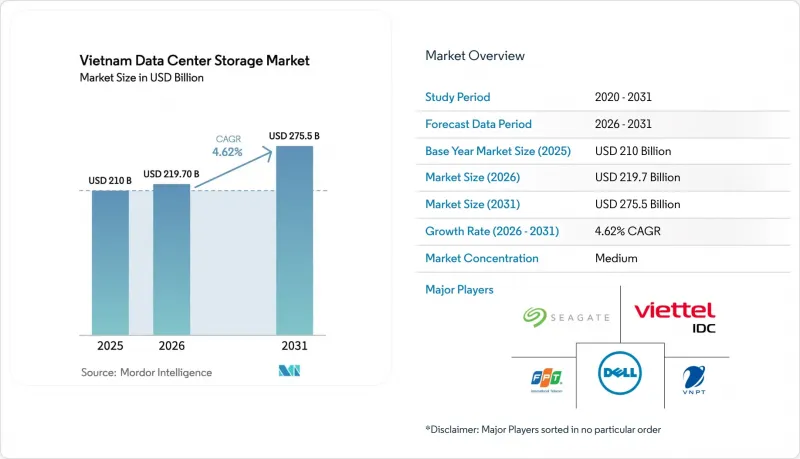
根據 Mordor Intelligence 預測,越南資料中心儲存市場規模將從 2025 年的 2.1 億美元成長到 2026 年的 2.197 億美元,然後在 2031 年達到 2.755 億美元,2026 年至 2031 年的複合年成長率為 4.62%。
本報告按儲存技術(網路附加儲存 (NAS) 等)、儲存類型(傳統儲存等)、資料中心類型(託管機房等)、外形規格(機架式等)、介面(SAS/SATA 等)和最終用戶(IT 和通訊等)對產業進行分類。市場預測以美元 (USD) 為單位。
越南資料中心儲存市場趨勢與洞察
IT基礎設施和寬頻的擴展
越南的「國家數位轉型計畫」旨在2025年實現80%家庭寬頻覆蓋,這一目標刺激了對邊緣和核心儲存系統的需求。計畫於2030年新增的10條海底光纜將使總容量擴展至350Tbps,從而持續推動對登陸點高密度邊緣設備的持續需求。 VTI等公司報告稱,遷移到雲端後成本降低了70%,這推動了混合儲存技術在分析和備份作業中的應用。製造業和物流行業的企業正在採用工業4.0工作流程,這需要低延遲、近流程儲存來支援機器人和即時品管。汽車OEM廠商和電子產品出口商是利用機架級快閃記憶體儲存來維持生產車間隨線分析的先驅。基礎設施建設的這種勢頭正在支撐越南資料中心儲存市場的長期成長。
增加對超大規模資料中心的投資
Viettel位於Tan Phu Trung的140兆瓦資料中心是越南首個容量超過100兆瓦的資料中心,其機架運作高達10千瓦(是全國平均水準的2.5倍),這推動了對NVMe加速的高密度陣列的需求。西貢資產管理公司投資15億美元興建的150兆瓦「SAM DigitalHub」專案也反映了市場對超大規模資料中心的強勁需求。投資者致力於透過熱水冷卻和後門冷卻將PUE值控制在1.4以下,這催生了對軟體定義儲存的需求,該儲存能夠最佳化分散式節點間的工作負載部署。隨著營運商對高效能運算架構進行標準化以滿足區域人工智慧需求,能夠提供可水平擴展且最大限度降低機架電力消耗的平台的供應商正在獲得競爭優勢。
三級/四級設施需要較高的初始資本投入。
Tier III認證要求透過雙通道實現電源、冷卻和儲存的冗餘。Delta電子在和樂的EPC合約顯示該項目屬於高資本密集項目,這意味著開發商將承擔較長的投資回報期。像CMC Telecom這樣的越南本土企業,作為越南首家獲得四級資訊安全認證的機構,需要符合全球標準才能吸引跨國公司客戶。資金籌措限制迫使營運商採用廠商資助的模組化組件和超融合設備,以降低初始投資。這種限制減緩了新建設速度,同時刺激了對預整合解決方案的需求,從而減少了現場工程工作。
細分市場分析
預計到2025年,SAN解決方案將佔越南資料中心儲存市場總收入的33.92%,這反映了企業對關鍵業務核心環境中低延遲、區塊級服務的需求。這一佔有率確立了SAN在越南資料中心儲存市場效能基礎的地位。 NAS正以6.58%的複合年成長率成長,這得益於中小企業的雲端計劃,這些計劃鼓勵採用經濟高效的以乙太網路為基礎部署。預計到2031年,越南資料中心儲存市場的NAS市場規模將超過1億美元,主要得益於政府獎勵的推動。直連儲存和物件儲存系統完善了符合新資料保存法規的專用邊緣和歸檔工作負載。
隨著 Viettel IDC 整合 Cloudian HyperStore,混合部署的趨勢正在加速發展。此方案在單一設備上提供物件和檔案服務,將 SAN 層級的事務性工作負載吞吐量與 NAS 的分析可擴充性結合。軟體定義疊加層模糊了協定邊界,支援在區塊、檔案和物件 API 之間動態選擇。這使企業能夠在最佳化整體擁有成本 (TCO) 的同時,進行面向未來的投資,從而在所有技術類別中保持強勁的需求。
由於每GB成本優勢顯著,硬碟陣列在2025年將佔總支出的42.55%。全快閃記憶體以9.12%的複合年成長率成為成長最快的儲存方案,正滿足人工智慧推理、即時分析和數位銀行等領域的尖峰需求。預計到2031年,全Flash陣列在越南資料中心儲存市場的佔有率將超過31.2%。混合配置方案將繼續被應用於容量和效能需求波動較大的中階負載場景。
Techcombank 向 IBM DS8886 的遷移就是一個快閃記憶體應用日益普及的例子。此舉使尖峰時段交易吞吐量提升了四倍,同時減少了機架面積。此外,金士頓 DC600M SSD 系列兼顧混合流量和能源效率,體現了永續 IT 的發展趨勢。同時,能源相關的獎勵也使快閃記憶體成為那些力求獲得碳中和認證的企業在總體擁有成本 (TCO) 計算中更具優勢的選擇。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- IT基礎設施的擴展和網際網路普及率的提高
- 增加對超大規模資料中心的投資
- 政府關於數位轉型和數據主權的指南
- 中小企業對雲端技術的採用激增,推動了對網路附加儲存 (NAS) 的需求成長。
- 人工智慧/機器學習工作負載的不斷成長正在加速對全快閃儲存的需求。
- 資料中心100%外資所有權的自由化
- 市場限制因素
- 三級/四級設施需要較高的初始資本投入。
- 熟練的倉儲工程師短缺
- 高密度機架內的電網限制
- 熱帶氣候導致空調費用高昂
- 價值供應鏈分析
- 監理情勢
- 技術趨勢(快閃記憶體、NVMe-oF、軟體定義儲存)
- 波特五力模型
- 評估宏觀經濟趨勢對市場的影響
第5章 市場規模與成長預測
- 儲存技術
- 網路附加儲存 (NAS)
- 儲存區域網路(SAN)
- 直接附加儲存(DAS)
- 物件存儲/磁帶存儲
- 依儲存類型
- 傳統硬碟陣列
- 全Flash陣列(AFA)
- 混合儲存
- 依資料中心類型
- 託管設施
- 超大規模資料中心業者雲端服務供應商
- 企業邊緣
- 最終用戶
- 資訊科技/通訊
- BFSI
- 政府/公共部門
- 媒體與娛樂
- 醫療保健和生命科學
- 製造業
- 按外形規格
- 機架安裝型
- 刀片模組化
- 可分離類型/可組合類型
- 透過介面
- SAS/SATA
- NVMe
- 光纖通道 iSCSI
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Dell Technologies Inc.
- NetApp Inc.
- Kingston Technology Company Inc.
- Lenovo Group Ltd.
- Fujitsu Ltd.
- Oracle Corporation
- Seagate Technology Holdings plc
- Western Digital Corporation
- Infortrend Technology Inc.
- Intel Corporation
- Viettel IDC Co. Ltd.
- VNPT VinaData Co. Ltd.
- FPT Telecom International
- CMC Telecom Infrastructure Co. Ltd.
- VDO Data Center
- ST Telemedia Global Data Centres Vietnam
- NTT Global Data Centers Vietnam
- Equinix Inc.
- Digital Realty Trust Inc.
- Schneider Electric SE
第7章 市場機會與未來展望
According to Mordor Intelligence, the Vietnam data center storage market size is expected to grow from USD 210 million in 2025 to USD 219.7 million in 2026 and is forecast to reach USD 275.5 million by 2031 at 4.62% CAGR over 2026-2031.
This report Segments the Industry Into Storage Technology (Network Attached Storage (NAS), and More), Storage Type (Traditional Storage, and More), Data Center Type (Colocation Facilities and More), Form Factor(Rack-Mounted and More), Interface(sas / SATA, and More)and End User (IT and Telecommunication, and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Data Center Storage Market Trends and Insights
Expansion of IT Infrastructure and Broadband
Vietnam's target of 80% household broadband coverage by 2025 under the National Digital Transformation Program is stimulating demand for edge and core storage systems. Ten additional submarine cables planned by 2030 will lift total capacity to 350 Tbps, generating sustained requirements for high-density edge appliances along landing points. Enterprises such as VTI report 70% cost savings after cloud migration, reinforcing hybrid storage uptake for analytics and backup operations vti. Manufacturing and logistics adopters are installing Industry 4.0 workflows that necessitate low-latency, compute-proximate storage for robotics and real-time quality control. Automotive OEMs and electronics exporters are notable early movers, using rack-scale flash to sustain inline analytics on production floors. This infrastructural momentum anchors long-run growth for the Vietnam data center storage market.
Rising Investments in Hyperscale Data Centers
Viettel's 140 MW Tan Phu Trung build represents Vietnam's inaugural 100 MW-plus data center, operating at 10 kW per rack-2.5X the national mean-thereby catalyzing demand for NVMe-accelerated, high-density arrays. Saigon Asset Management's USD 1.5 billion, 150 MW SAM DigitalHub signals strong capital appetite for hyperscale footprints. Investors target PUE levels below 1.4 through warm-water and rear-door cooling, creating openings for software-defined storage that optimizes workload placement across distributed nodes. Vendors offering horizontally scalable platforms that minimize rack power draw gain a competitive edge as operators standardize on high-performance compute fabrics to serve regional AI demand.
High Upfront Capex for Tier III/IV Facilities
Tier III certification demands dual-path power, cooling and storage redundancy. Delta Electronics' EPC contract in Hoa Lac illustrates capital intensity, with developers absorbing long ROI timelines delta. Domestic firms such as CMC Telecom must match global benchmarks to win multinational clients after becoming Vietnam's first Level 4 Information Security-accredited site cmc. Financing constraints push operators toward vendor-financed, modular blocks and hyper-converged appliances that compress initial outlays. While the restraint suppresses greenfield pace, it stimulates demand for pre-integrated solutions that reduce on-site engineering effort.
Other drivers and restraints analyzed in the detailed report include:
- Government Digital-Transformation and Data-Sovereignty Mandates
- Surge in SME Cloud Adoption Driving NAS
- Shortage of Skilled Storage Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SAN solutions delivered 33.92% of 2025 revenues, reflecting enterprise demand for low-latency, block-level services in mission-critical cores. This share positions SAN as the performance backbone of the Vietnam data center storage market. NAS, climbing at 6.58% CAGR, benefits from SME cloud programs that reward cost-effective, Ethernet-based deployments. The Vietnam data center storage market size for NAS is projected to cross USD 0.1 billion by 2031, aided by government incentives. Direct-attached and object systems supplement specialized edge and archival workloads governed by emerging data-retention rules.
Hybrid adoption patterns intensify as Viettel IDC integrates Cloudian HyperStore to offer object and file services on a unified appliance, combining SAN-grade throughput for transactional workloads with NAS scalability for analytics datacenternews. Software-defined overlays blur protocol boundaries, enabling dynamic selection between block, file and object APIs. Enterprises thus future-proof investments while optimizing TCO, sustaining robust demand across all technology categories.
HDD arrays accounted for 42.55% of spending in 2025 due to favorable USD per-GB economics. All-flash, the fastest-growing at 9.12% CAGR, captures AI inference, real-time analytics and digital banking peaks. Vietnam data center storage market share for all-flash arrays is slated to climb beyond 31.2% by 2031. Hybrid tiers persist for mid-range workloads that fluctuate between capacity and performance needs.
Flash traction is underscored by Techcombank's migration to IBM DS8886, quadrupling peak transaction throughput while shrinking rack footprint ibm. Kingston's DC600M SSD line addresses mixed-use traffic and power efficiency, echoing policy emphasis on sustainable IT kingston. Energy incentives further tilt TCO calculus in favor of flash for operators seeking carbon neutrality certifications.
Complete Report Scope:
- By Storage Technology
- Network Attached Storage (NAS)
- Storage Area Network (SAN)
- Direct Attached Storage (DAS)
- Object and Tape Storage
- By Storage Type
- Traditional HDD Arrays
- All-Flash Arrays (AFA)
- Hybrid Storage
- By Data Center Type
- Colocation Facilities
- Hyperscalers/Cloud Service Providers
- Enterprise and Edge
- By End User
- IT and Telecommunication
- BFSI
- Government and Public Sector
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing
- By Form Factor
- Rack-mounted
- Blade and Modular
- Disaggregated / Composable
- By Interface
- SAS / SATA
- NVMe
- Fibre Channel and iSCSI
List of Companies Covered in this Report:
- Dell Technologies Inc.
- NetApp Inc.
- Kingston Technology Company Inc.
- Lenovo Group Ltd.
- Fujitsu Ltd.
- Oracle Corporation
- Seagate Technology Holdings plc
- Western Digital Corporation
- Infortrend Technology Inc.
- Intel Corporation
- Viettel IDC Co. Ltd.
- VNPT VinaData Co. Ltd.
- FPT Telecom International
- CMC Telecom Infrastructure Co. Ltd.
- VDO Data Center
- ST Telemedia Global Data Centres Vietnam
- NTT Global Data Centers Vietnam
- Equinix Inc.
- Digital Realty Trust Inc.
- Schneider Electric SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of IT infrastructure and internet penetration
- 4.2.2 Rising investments in hyperscale data centers
- 4.2.3 Government digital-transformation and data-sovereignty mandates
- 4.2.4 Surge in SME cloud adoption driving network-attached storage
- 4.2.5 AI/ML workload growth accelerating all-flash storage demand
- 4.2.6 Liberalization of 100 % foreign ownership for data centers
- 4.3 Market Restraints
- 4.3.1 High upfront capex for Tier III/IV facilities
- 4.3.2 Shortage of skilled storage engineers
- 4.3.3 Grid-energy constraints for high-density racks
- 4.3.4 Rising cooling costs from tropical climate
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (flash, NVMe-oF, software-defined storage)
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of the impact of Macro Economic Trends on the Market
5 Market Size and Growth Forecasts (Value)
- 5.1 By Storage Technology
- 5.1.1 Network Attached Storage (NAS)
- 5.1.2 Storage Area Network (SAN)
- 5.1.3 Direct Attached Storage (DAS)
- 5.1.4 Object and Tape Storage
- 5.2 By Storage Type
- 5.2.1 Traditional HDD Arrays
- 5.2.2 All-Flash Arrays (AFA)
- 5.2.3 Hybrid Storage
- 5.3 By Data Center Type
- 5.3.1 Colocation Facilities
- 5.3.2 Hyperscalers/Cloud Service Providers
- 5.3.3 Enterprise and Edge
- 5.4 By End User
- 5.4.1 IT and Telecommunication
- 5.4.2 BFSI
- 5.4.3 Government and Public Sector
- 5.4.4 Media and Entertainment
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Manufacturing
- 5.5 By Form Factor
- 5.5.1 Rack-mounted
- 5.5.2 Blade and Modular
- 5.5.3 Disaggregated / Composable
- 5.6 By Interface
- 5.6.1 SAS / SATA
- 5.6.2 NVMe
- 5.6.3 Fibre Channel and iSCSI
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Technologies Inc.
- 6.4.2 NetApp Inc.
- 6.4.3 Kingston Technology Company Inc.
- 6.4.4 Lenovo Group Ltd.
- 6.4.5 Fujitsu Ltd.
- 6.4.6 Oracle Corporation
- 6.4.7 Seagate Technology Holdings plc
- 6.4.8 Western Digital Corporation
- 6.4.9 Infortrend Technology Inc.
- 6.4.10 Intel Corporation
- 6.4.11 Viettel IDC Co. Ltd.
- 6.4.12 VNPT VinaData Co. Ltd.
- 6.4.13 FPT Telecom International
- 6.4.14 CMC Telecom Infrastructure Co. Ltd.
- 6.4.15 VDO Data Center
- 6.4.16 ST Telemedia Global Data Centres Vietnam
- 6.4.17 NTT Global Data Centers Vietnam
- 6.4.18 Equinix Inc.
- 6.4.19 Digital Realty Trust Inc.
- 6.4.20 Schneider Electric SE
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 中國資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印尼資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032)德國資料中心儲存:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)新加坡資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)菲律賓資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)馬來西亞資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026-2030年全球伺服器儲存市場
 資料中心儲存市場-2026-2032年全球市場預測
 2026年全球儲存架構市場報告