


 |
市場調查報告書
商品編碼
2119809
菲律賓資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Philippines Data Center Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
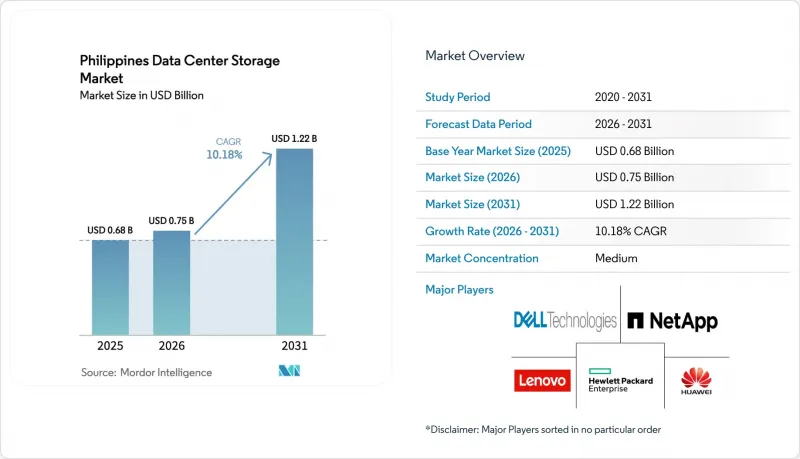
據 Mordor Intelligence 稱,菲律賓資料中心儲存市場在 2025 年的價值為 6.8 億美元,預計到 2031 年將達到 12.2 億美元,而 2026 年為 7.5 億美元,預測期(2026-2031 年)的複合年成長率為 10.18%。
本報告按儲存技術(網路附加儲存 (NAS)、儲存區域網路(SAN)、其他)、儲存類型(傳統硬碟陣列、其他)、最終用戶(IT 和通訊、銀行、金融服務和保險 (BFSI)、政府、其他)、外形規格(機架式、其他)和介面(SAS/SATA、其他)進行細分。所有細分市場的規模和預測均以美元 (USD) 表示。
菲律賓資料中心儲存市場趨勢及洞察
IT基礎設施擴展與數位轉型
預計到2024年,數位經濟規模將達到450億美元,佔GDP的8.5%,到2030年可望創造5兆菲律賓披索的價值。隨著企業從孤立的儲存陣列轉向彈性、可擴展的雲端原生平台,這項國家轉型正在推動儲存架構的根本性變革。馬尼拉水務公司實施的基於雲端的水資源管理系統就是一個關鍵任務部署的典範,它最大限度地降低了資料遺失的風險,同時確保了2,700萬居民的供水服務連續性。政府的「數位菲律賓宣傳活動」和「國家寬頻計畫」等項目促使85%的企業計畫在2026年前將工作負載遷移到雲端,加速了混合式儲存技術在本地、邊緣和超大規模設施的應用。此外,貿易和工業部對400多家工廠進行的「智慧產業準備指數」調查進一步推動了對支援即時分析的邊緣儲存的需求。
超大規模資料中心和託管資料中心投資激增
由於人工智慧機架所需的功率密度是傳統機架的兩倍以上,超大規模業者僅在2024年就在菲律賓投資47億美元用於設施建設。 Equinix斥資1億美元收購馬尼拉三個場地並新增1,000個營運商中立機櫃,體現了國際社會對其的高度信任。 PLDT已啟用一座50兆瓦的超大規模資料中心,並正在考慮以10億美元的價格上市房地產投資信託基金(REIT),而Globe Telecom也已破土動工建設一座124兆瓦的園區。位於新克拉克城奈良科技園區的300兆瓦綠色資料中心正在興建中,建成後將成為菲律賓最大的資料中心。這些專案都需要基於NVMe的全Flash陣列,以提供低延遲的吞吐量,滿足人工智慧推理工作負載的需求。
企業級儲存的高額資本投入
儘管預期快閃記憶體價格每年下降15%,QLC快閃記憶體價格在2022年至2025年間更是下降60%,但快閃記憶體的價格仍比硬碟高出5-7倍。中小企業難以負擔冗餘陣列、備份設備以及資料隱私法要求的合規管理費用。在馬尼拉大都會區以外,由於租賃和信貸額度有限,資金籌措更大。訂閱模式正在興起。 Pure Storage的「Evergreen」產品組合預計在2025會計年度第三季訂閱營收將成長22%,該產品組合提供基於營運成本資金籌措(OPEX)的選項,可減少前期現金支出。
細分市場分析
2025年,儲存區域網路(SAN)將佔總營收的43.75%,為關鍵業務核心銀行系統和電信業者的OSS/BSS工作負載提供可靠性保障。物件儲存和磁帶儲存是成長最快的領域,複合年成長率(CAGR)達12.02%,這主要得益於人工智慧、媒體串流和物聯網數據,它們在扁平命名空間架構上提供了卓越的可擴展性。網路附加儲存系統(NAS)在優先考慮檔案級便利性的中小型企業中保持著強勁的地位,而直連式配置則滿足實驗室高效能運算(HPC)叢集。隨著Google等超超大規模資料中心業者儲存市場規模預計將迅速擴張。戴爾等廠商正在將S3相容服務整合到PowerStore中,從而在單一裝置中統一區塊、檔案和物件協定。
營運商正擴大利用人工智慧驅動的分層儲存技術,將不常用的資料集遷移到磁帶庫或雲端儲存桶,同時保留SAN快閃記憶體用於對延遲敏感的分析處理。這種最佳化既節省了資金,也符合菲律賓銀行和服務提供者(BSP)的資料保存規則。因此,菲律賓資料中心儲存市場正受益於銀行、金融和保險(BFSI)以及媒體公司日益成長的混合部署,這些公司在追求每GB成本控制的同時,也注重效能。
即使到了2025年,HDD陣列仍將佔據41.60%的銷售額,主要服務於媒體存檔和備份庫等對每Terabyte成本要求極高的場景。然而,隨著人工智慧推理工作負載對微秒響應時間的需求日益成長,預計到2031年,全Flash陣列的複合年成長率將達到12.85%。因此,隨著NVMe技術的普及,全閃存在菲律賓資料中心儲存市場的佔有率預計將大幅提升。希捷的30TB熱輔助磁記錄(HAMR)硬碟展現了HDD領域的創新,而西部資料的分拆則預示著磁碟和快閃記憶體的未來出現分歧。由於快閃記憶體價格每年下降15%,將SSD層與高容量機械硬碟結合的混合陣列,為通訊和金融科技產業租戶的事務型資料庫需求提供了一種折衷方案。
在菲律賓資訊通訊技術部 (DICT) 的「雲端優先」政策下,隨著 SaaS 和 PaaS 架構對傳統 HDD SAN 無法達到的 IOPS 密度需求,向快閃記憶體儲存的轉型正在加速。此外,資料在地化法規要求將大規模資料集保存在國內,這增加了對高效快閃記憶體去重技術的需求,以便有效利用馬尼拉大都會區有限的占地面積。因此,在整個預測期內,菲律賓資料中心儲存市場預計將繼續以 NVMe 和 QLC SSD 為主。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- IT基礎設施擴展與數位轉型
- 超大規模資料中心和託管資料中心投資激增
- 雲和混合雲端的快速普及
- 政府對CREATE和DICT綠色資料中心的獎勵措施
- BSP第1122號通告:強制資料本地化
- 由於 NVMe 快閃記憶體的廣泛應用,人工智慧驅動的分析工作負載激增。
- 市場限制因素
- 企業儲存領域的高資本投入
- 認證儲存工程師短缺
- 島際光纖和電力供應可靠性有差異。
- 比索披索推高了進口快件的成本。
- 價值供應鏈分析
- 監管情勢(以菲律賓為例)
- 技術趨勢(人工智慧、邊緣/NVMe、SDS)
- 波特五力模型
- 市場宏觀經濟趨勢的評估
第5章 市場規模與成長預測
- 儲存技術
- 網路附加儲存 (NAS)
- 儲存區域網路(SAN)
- 直接附加儲存(DAS)
- 物件存儲/磁帶存儲
- 依儲存類型
- 傳統硬碟陣列
- 全Flash陣列(AFA)
- 混合儲存
- 依資料中心類型
- 託管設施
- 超大規模資料中心業者雲端服務供應商
- 企業邊緣
- 最終用戶
- 資訊科技/通訊
- BFSI
- 政府/公共部門
- 媒體與娛樂
- 醫療保健和生命科學
- 製造業
- 按外形規格
- 機架安裝型
- 刀片模組化
- 可分離和可組合
- 透過介面
- SAS/SATA
- NVMe
- 光纖通道 iSCSI
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Dell Inc.
- Huawei Technologies Co., Ltd.
- Hewlett Packard Enterprise Company
- Lenovo Group Limited
- NetApp, Inc.
- Fujitsu Limited
- Oracle Corporation
- Seagate Technology Holdings PLC
- Western Digital Corporation
- Infortrend Technology, Inc.
- Pure Storage, Inc.
- Hitachi Vantara LLC
- IBM Corporation
- Synology Inc.
- Toshiba Electronic Devices and Storage Corp.
- Nutanix, Inc.
- NEC Corporation
- Netgear, Inc.
- Overland-Tandberg Holdings AB
- Kingston Technology Company, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Philippines data center storage market size was valued at USD 0.68 billion in 2025 and estimated to grow from USD 0.75 billion in 2026 to reach USD 1.22 billion by 2031, at a CAGR of 10.18% during the forecast period (2026-2031).
This report is Segmented Into Storage Technology (Network Attached Storage (NAS), Storage Area Network (SAN) and More), Storage Type (Traditional Storage, and More), and End-User (IT & Telecommunication, BFSI, Government, and More). Form Factor (Rack-Mounted and More), Interface (SAS / SATA and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD) for all the Segments.
Philippines Data Center Storage Market Trends and Insights
Expansion of IT infrastructure and digital transformation
The digital economy reached USD 45 billion in 2024, equating to 8.5% of GDP, and could unlock PHP 5 trillion in value by 2030. This national pivot is overhauling storage architectures as enterprises move from siloed arrays to cloud-native platforms that scale elastically. Manila Water's cloud-based water-management rollout illustrates mission-critical adoption, safeguarding service continuity for 27 million residents while minimizing data-loss risk. Government programs such as the Digital Philippines Campaign and the National Broadband Plan mean 85% of firms intend to migrate workloads to cloud by 2026, spurring uptake of hybrid storage that spans on-premises, edge, and hyperscale facilities. The Department of Trade and Industry's Smart Industry Readiness Index across 400+ factories is further prompting demand for edge storage that enables real-time analytics.
Surge in hyperscale and colocation investments
Hyperscalers are allocating USD 4.7 billion to Philippine builds in 2024 alone, as AI racks require more than double traditional power density. Equinix's USD 100 million purchase of three Manila sites adds 1,000 carrier-neutral cabinets, demonstrating foreign confidence. PLDT opened a 50 MW hyperscale facility and is weighing a USD 1 billion REIT listing, while Globe Telecom has broken ground on a 124 MW campus . Narra Technology Park's 300 MW green data-center build in New Clark City will be the country's largest. These projects demand NVMe-based all-flash arrays that deliver low-latency throughput for AI inference workloads.
High capex for enterprise-grade storage
Flash media retains a 5-7X price premium to HDD despite 15% annual declines and a projected 60% QLC price crash between 2022-2025. SMEs struggle to fund redundant arrays, backup appliances, and compliance controls mandated by the Data Privacy Act. Financing gaps are wider outside Metro Manila, where leasing and credit lines are limited. Subscription models are gaining ground-Pure Storage's Evergreen portfolio drove 22% subscription revenue expansion in Q3 FY 2025-offering opex options that soften initial cash outlays.
Other drivers and restraints analyzed in the detailed report include:
- Rapid cloud and hybrid-cloud adoption
- Government CREATE and DICT green-DC incentives
- Shortage of certified storage engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Storage Area Networks led revenue with 43.75% share in 2025, underscoring their reliability for mission-critical core-banking and telco OSS/BSS workloads. Object and Tape Storage is the fastest riser at 12.02% CAGR, propelled by AI, media streaming, and IoT data that scale better on flat-namespace architectures. Network-attached systems retain footholds among SMEs that favor file-level simplicity, while direct-attached setups cater to HPC clusters in research labs. The Philippines data center storage market size for object storage will expand swiftly as hyperscalers like Google deploy TPU cables delivering 260 Tbps capacity and flooding local nodes with unstructured content Vendors such as Dell have embedded S3-compatible services in PowerStore, aligning block, file, and object protocols inside a single appliance.
Operators increasingly apply AI-infused tiering to shuttle cold datasets into tape libraries or cloud buckets while reserving SAN flash for latency-sensitive analytics. This optimization preserves capital and aligns with BSP retention rules. In turn, the Philippines data center storage market benefits from widening hybrid adoption across BFSI and media enterprises pursuing cost-per-GB discipline without sacrificing performance.
HDD arrays still captured 41.60% revenue in 2025, servicing media archives and backup vaults that value USD/terabyte. Yet all-flash arrays will post a 12.85% CAGR through 2031 as AI inference workloads require microsecond response times. The Philippines data center storage market share of all-flash will thus rise sharply alongside NVMe penetration. Seagate's 30 TB Heat-Assisted Magnetic Recording drives underscore HDD innovation, yet Western Digital's corporate split indicates divergent futures for disk and flash. As flash price curves drop 15% yearly, hybrid arrays offer a compromise, combining SSD tiers with high-capacity spindles to serve transactional databases across telecom and fintech tenants.
Migration to flash accelerates under DICT's cloud-first policy because SaaS and PaaS stacks expect IOPS densities unattainable on legacy HDD SANs. Data-localization rules also keep large datasets on-shore, lifting demand for efficient flash-based deduplication that stretches scarce floor space in Metro Manila. Consequently, the Philippines data center storage market continues to skew toward NVMe and QLC SSD deployments over the forecast horizon.
Complete Report Scope:
- By Storage Technology
- Network Attached Storage (NAS)
- Storage Area Network (SAN)
- Direct Attached Storage (DAS)
- Object and Tape Storage
- By Storage Type
- Traditional HDD Arrays
- All-Flash Arrays (AFA)
- Hybrid Storage
- By Data Center Type
- Colocation Facilities
- Hyperscalers/Cloud Service Providers
- Enterprise and Edge
- By End User
- IT and Telecommunication
- BFSI
- Government and Public Sector
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing
- By Form Factor
- Rack-mounted
- Blade and Modular
- Disaggregated / Composable
- By Interface
- SAS / SATA
- NVMe
- Fibre Channel and iSCSI
List of Companies Covered in this Report:
- Dell Inc.
- Huawei Technologies Co., Ltd.
- Hewlett Packard Enterprise Company
- Lenovo Group Limited
- NetApp, Inc.
- Fujitsu Limited
- Oracle Corporation
- Seagate Technology Holdings PLC
- Western Digital Corporation
- Infortrend Technology, Inc.
- Pure Storage, Inc.
- Hitachi Vantara LLC
- IBM Corporation
- Synology Inc.
- Toshiba Electronic Devices and Storage Corp.
- Nutanix, Inc.
- NEC Corporation
- Netgear, Inc.
- Overland-Tandberg Holdings AB
- Kingston Technology Company, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of IT infrastructure and digital transformation
- 4.2.2 Surge in hyperscale and colocation investments
- 4.2.3 Rapid cloud and hybrid-cloud adoption
- 4.2.4 Government CREATE and DICT green-DC incentives
- 4.2.5 BSP Circular 1122 data-localization mandate
- 4.2.6 AI-driven analytics workload boom (NVMe flash uptake)
- 4.3 Market Restraints
- 4.3.1 High capex for enterprise-grade storage
- 4.3.2 Shortage of certified storage engineers
- 4.3.3 Inter-island fibre and power reliability gaps
- 4.3.4 Peso depreciation inflating imported flash costs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape (PH-specific)
- 4.6 Technological Outlook (AI/Edge/NVMe, SDS)
- 4.7 Porters Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 Market Size and Growth Forecasts (Value)
- 5.1 By Storage Technology
- 5.1.1 Network Attached Storage (NAS)
- 5.1.2 Storage Area Network (SAN)
- 5.1.3 Direct Attached Storage (DAS)
- 5.1.4 Object and Tape Storage
- 5.2 By Storage Type
- 5.2.1 Traditional HDD Arrays
- 5.2.2 All-Flash Arrays (AFA)
- 5.2.3 Hybrid Storage
- 5.3 By Data Center Type
- 5.3.1 Colocation Facilities
- 5.3.2 Hyperscalers/Cloud Service Providers
- 5.3.3 Enterprise and Edge
- 5.4 By End User
- 5.4.1 IT and Telecommunication
- 5.4.2 BFSI
- 5.4.3 Government and Public Sector
- 5.4.4 Media and Entertainment
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Manufacturing
- 5.5 By Form Factor
- 5.5.1 Rack-mounted
- 5.5.2 Blade and Modular
- 5.5.3 Disaggregated / Composable
- 5.6 By Interface
- 5.6.1 SAS / SATA
- 5.6.2 NVMe
- 5.6.3 Fibre Channel and iSCSI
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Inc.
- 6.4.2 Huawei Technologies Co., Ltd.
- 6.4.3 Hewlett Packard Enterprise Company
- 6.4.4 Lenovo Group Limited
- 6.4.5 NetApp, Inc.
- 6.4.6 Fujitsu Limited
- 6.4.7 Oracle Corporation
- 6.4.8 Seagate Technology Holdings PLC
- 6.4.9 Western Digital Corporation
- 6.4.10 Infortrend Technology, Inc.
- 6.4.11 Pure Storage, Inc.
- 6.4.12 Hitachi Vantara LLC
- 6.4.13 IBM Corporation
- 6.4.14 Synology Inc.
- 6.4.15 Toshiba Electronic Devices and Storage Corp.
- 6.4.16 Nutanix, Inc.
- 6.4.17 NEC Corporation
- 6.4.18 Netgear, Inc.
- 6.4.19 Overland-Tandberg Holdings AB
- 6.4.20 Kingston Technology Company, Inc.
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 中國資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印尼資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032)德國資料中心儲存:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)新加坡資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)越南資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞資料中心儲存:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026-2030年全球伺服器儲存市場
 資料中心儲存市場-2026-2032年全球市場預測
 2026年全球儲存架構市場報告