


 |
市場調查報告書
商品編碼
2119754
歐洲資料中心伺服器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Data Center Server - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
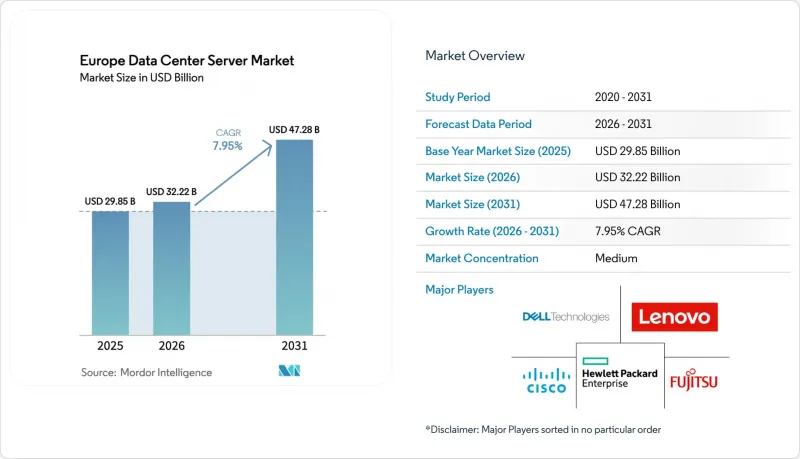
根據 Mordor Intelligence 預測,歐洲資料中心伺服器市場規模將從 2025 年的 298.5 億美元成長到 2026 年的 322.2 億美元,然後在 2031 年達到 472.8 億美元,2026 年至 2031 年的複合年成長率為 7.95%。
本報告按資料中心層級(Tier 1、Tier 2、其他)、外形規格(半高刀片、全高刀片、其他)、應用領域(虛擬化和私有雲端、高效能運算、其他)、資料中心類型(超大規模資料中心業者資料中心供應商、其他)、最終用戶產業(銀行、金融服務和保險 (BFSI)、其他)以及國家/地區進行細分。以上所有細分市場的規模和預測均以美元 (USD) 為單位。
歐洲資料中心伺服器市場趨勢與洞察
雲端運算和X即服務(XaaS)的採用
超大規模資料中心業者正在建構區域專屬的可用區,從而持續推動對機架級伺服器的需求。微軟已確認在法國北部新建三個資料中心,而亞馬遜雲端服務(AWS)也已成立獨立的歐洲主權雲端營業單位,以滿足居住要求(aws.amazon.com)。據一家荷蘭業者稱,這些活動目前約佔國內生產總值(GDP)的7.6%。在像Uniper這樣的公司將1萬名員工遷移到Azure後,IT事件減少了50%,其案例研究表明,這種模式帶來了切實的營運效益。
5G部署和邊緣節點
在歐盟邊緣運算觀測計畫 (Edge Observatory Programme) 的支援下,電信業者正在基地台部署微型資料中心,以實現低於 20 毫秒的延遲目標。愛立信在希臘 Karpac太陽熱能發電發電廠部署的專用 5G 網路展示了製造業的應用案例,而德國邊緣雲端則為 Rittal 的工業 4.0 工廠提供支持,該工廠擁有超過 250 台聯網機器。
新設施的資本支出(CapEx)激增。
到2025年,一級資料中心樞紐50英畝土地的價格將上漲23%,電力分配的等待時間將超過36個月。 Vantage Data Centres展示了一種創新的資金籌措方式,利用7.2億歐元(8.2916億美元)的證券化資金為德國的四個建設項目提供資金籌措。人手不足也推高了預算,促使開發人員將目光轉向波蘭和西班牙,因為這些國家的成本仍然低15-20%。
細分市場分析
到2025年,Tier 3級資料中心將佔據歐洲資料中心伺服器市場71.62%的佔有率,這充分展現了其在成本和容錯能力方面的卓越平衡。近期系統故障頻傳後,金融機構加快了升級步伐,紛紛採用Tier 3級資料中心來處理交易關鍵型工作負載。德國中央銀行(DZ BANK)部署了日立Vantara EverFlex伺服器,進一步推動了這一趨勢,確保運作始終在線。隨著人工智慧和主權雲端服務供應商對容錯正常運作的需求日益成長,預計歐洲資料中心伺服器市場的Tier 4級資料中心將以每年9.98%的速度成長。政府主導的超級電腦項目,例如塞爾維亞的「Eviden」項目,也進一步凸顯了Tier 4級資料中心日益成長的吸引力。
邊緣部署在開發環境中仍然有限地使用 Tier 1/2 套件,因為在這些環境中,接近性比冗餘性更為重要。然而,歐盟關於事件報告的更嚴格的指令可能會逐步促使即使是邊緣站點也升級到 Tier 3 認證,這將推動整個歐洲資料中心伺服器市場規範要求的結構性改進。
即使到了2025年,半高刀鋒伺服器仍將佔據63.85%的銷售量,繼續為傳統的虛擬化環境提供支援。聯想基於英特爾至強6處理器的ThinkSystem V4系列正在革新這一主流細分市場。在歐洲資料中心伺服器市場,四分之一高刀片伺服器市場成長最為迅猛,複合年成長率高達8.35%,這主要得益於營運商在零售店和行動電話基地台部署微型邊緣節點。
全高刀鋒伺服器對於GPU叢集仍然至關重要。思科UCS C845A在4RU機架空間內整合了8個NVIDIA GPU,滿足了嚴格的機架電源預算要求。 NVIDIA MGX等模組化參考架構允許營運商無需更改電源軌即可插入新的加速卡,從而延長資產使用壽命並降低整體擁有成本。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 雲端運算和「X即服務」的採用
- 5G和邊緣節點的快速商用部署
- GPU/AI 伺服器的超大規模刷新週期
- 歐盟綠色新政對水冷機架的獎勵
- 主權人工智慧/歐盟資料法旨在促進區域內運算發展
- 模組化和預製微型資料中心的興起
- 市場限制因素
- 增加對新設施的資本投資
- 波動的電力價格和碳價格
- 尖端GPU和CPU的供應鏈緊張
- 加強對廢熱再利用和PUE的監管
- 供應鏈分析
- 監管環境(GDPR、歐盟資料法、生態設計)
- 科技趨勢(人工智慧加速器、CXL、水冷)
- 波特五力分析
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 資料中心層級
- 一級和二級
- 三級
- 第四級
- 按外形規格
- 半高刀片
- 全高刀片
- 四分之一高度/微刀片
- 按應用程式/工作負載
- 虛擬化和私有雲端
- 高效能運算(HPC)
- 人工智慧/機器學習和數據分析
- 以儲存為中心
- 邊緣/物聯網閘道器
- 依資料中心類型
- 超大規模資料中心業者雲端服務供應商/雲端服務供應商
- 託管設施
- 企業和邊緣運算
- 按最終用途行業分類
- BFSI
- 資訊科技/通訊
- 醫療保健和生命科學
- 製造業和工業4.0
- 能源公用事業
- 政府/國防
- 按地區
- 奧地利
- 比利時
- 丹麥
- 法國
- 德國
- 愛爾蘭
- 義大利
- 荷蘭
- 挪威
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略性舉措(併購、合資、資金籌措)
- 市佔率分析
- 公司簡介
- Dell Technologies
- Hewlett Packard Enterprise
- Lenovo Group
- Cisco Systems
- Fujitsu
- Huawei Technologies
- Inspur Group
- International Business Machines(IBM)
- Quanta Computer
- Super Micro Computer
- Atos SE
- Advanced Micro Devices(AMD)
- Intel Corporation
- Nvidia Corp.
- Foxconn/Hon Hai(including QCT)
- Gigabyte Technology
- MiTAC/TYAN
- ASRock Rack
- Inventec
- Kingston Technology
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe data center server market size is expected to grow from USD 29.85 billion in 2025 to USD 32.22 billion in 2026 and is forecast to reach USD 47.28 billion by 2031 at 7.95% CAGR over 2026-2031.
This report is Segmented by Data Center Tier(Tier 1 and 2, and More), Form Factor(Half-Height Blades, Full-Height Blades and More), Application(virtualisation and Private Cloud, High-Performance Computing and More), Data Center Type(Hyperscalers Provider and More), End User Industry(BFSI and More)and by Country. The Market Sizes and Forecasts are Provided in Terms of Value (USD) for all the Above Segments.
Europe Data Center Server Market Trends and Insights
Cloud computing & X-as-a-Service adoption
Hyperscalers are building region-specific availability zones, driving sustained demand for rack-scale servers. Microsoft confirmed three new data centers in Northern France, while AWS formed a standalone European Sovereign Cloud entity to satisfy residency rules aws.amazon.com. Dutch operators estimate that data centers now add 7.6% to the national GDP due to such activity. Enterprise case studies, such as Uniper's migration of 10,000 employees to Azure, resulting in 50% fewer IT incidents, illustrate tangible operational gains.
5G rollout & edge nodes
Operators deploy micro-data-centers at base-station sites to meet sub-20 ms latency targets under the EU Edge Observatory program. Ericsson's private 5G network at Calpak's Greek solar-heater plant shows manufacturing use cases, while German Edge Cloud powers Rittal's Industry 4.0 factory with 250+ networked machines.
Escalating CapEx for new facilities
Land costs for 50-acre plots in tier-1 hubs climbed 23% in 2025, while power-allocation queues exceed 36 months.Vantage Data Centers tapped a EUR 720 million (USD 829.16 million) securitization to fund four German builds, showcasing creative financing. Labor scarcity also inflates budgets, prompting developers to pivot toward Poland and Spain where costs remain 15-20% lower.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscale refresh toward GPU/AI servers
- EU Green Deal incentives for liquid cooling
- Supply-chain squeeze on advanced GPUs/CPUs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 facilities accounted for 71.62% of Europe data center server market share in 2025, a testament to their cost-to-resilience balance. Financial institutions accelerated upgrades after recent outages, adopting Tier 3 for transaction-critical workloads. DZ BANK deployed Hitachi Vantara EverFlex to secure always-on storage, reinforcing this preference. The Europe data center server market size for Tier 4 is projected to expand 9.98% annually as AI and sovereign-cloud operators demand fault-tolerant uptime. Government supercomputer projects, such as Serbia's Eviden contract, validate the rising appeal of Tier 4.
Edge rollouts sustain limited use of Tier 1/2 suites for development environments where proximity matters more than redundancy. However, stricter EU directives on incident reporting could gradually shift even peripheral sites toward Tier 3 certification, underpinning a structural uplift in specification requirements across the Europe data center server market.
Half-height blades retained 63.85% revenue in 2025, anchoring legacy virtualization estates. Lenovo's ThinkSystem V4 line, built on Intel Xeon 6, refreshes this mainstream segment. Europe data center server market size for quarter-height blades is rising fastest at 8.35% CAGR as operators outfit micro-edge nodes inside retail outlets and cell towers.
Full-height blades remain vital for GPU clusters; Cisco's UCS C845A packs eight NVIDIA GPUs within 4 RU, meeting tight rack-power budgets. Modular reference architectures such as NVIDIA MGX allow operators to drop new accelerator cards without replacing rails, extending asset life and lowering TCO.
Complete Report Scope:
- By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
- By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
- By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
- By Geography
- Austria
- Belgium
- Denmark
- France
- Germany
- Ireland
- Italy
- Netherlands
- Norway
- Rest of Europe
List of Companies Covered in this Report:
- Dell Technologies
- Hewlett Packard Enterprise
- Lenovo Group
- Cisco Systems
- Fujitsu
- Huawei Technologies
- Inspur Group
- International Business Machines (IBM)
- Quanta Computer
- Super Micro Computer
- Atos SE
- Advanced Micro Devices (AMD)
- Intel Corporation
- Nvidia Corp.
- Foxconn / Hon Hai (including QCT)
- Gigabyte Technology
- MiTAC / TYAN
- ASRock Rack
- Inventec
- Kingston Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Adoption of cloud computing and X-as-a-Service
- 4.2.2 Rapid commercial roll-out of 5G and edge nodes
- 4.2.3 Hyperscale refresh cycle toward GPU/AI servers
- 4.2.4 EU Green Deal incentives for liquid-cooled racks
- 4.2.5 Sovereign AI / EU Data Act pushing in-region compute
- 4.2.6 Rise of modular, prefabricated micro-data-centers
- 4.3 Market Restraints
- 4.3.1 Escalating CapEx for new facilities
- 4.3.2 Volatile electricity and carbon prices
- 4.3.3 Supply-chain squeeze on advanced GPUs/CPUs
- 4.3.4 Stricter waste-heat reuse and PUE regulations
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape (GDPR, EU Data Act, Eco-design)
- 4.6 Technological Outlook (AI accelerators, CXL, liquid cooling)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Data-Center Tier
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Form Factor
- 5.2.1 Half-height Blades
- 5.2.2 Full-height Blades
- 5.2.3 Quarter-height / Micro-blades
- 5.3 By Application / Workload
- 5.3.1 Virtualisation and Private Cloud
- 5.3.2 High-Performance Computing (HPC)
- 5.3.3 Artificial Intelligence/Machine Learning and Data Analytics
- 5.3.4 Storage-centric
- 5.3.5 Edge / IoT Gateways
- 5.4 By Data Center Type
- 5.4.1 Hyperscalers/Cloud Service Provider
- 5.4.2 Colocation Facilities
- 5.4.3 Enterprise and Edge
- 5.5 By End-use Industry
- 5.5.1 BFSI
- 5.5.2 IT and Telecom
- 5.5.3 Healthcare and Life-Sciences
- 5.5.4 Manufacturing and Industry 4.0
- 5.5.5 Energy and Utilities
- 5.5.6 Government and Defence
- 5.6 By Geography
- 5.6.1 Austria
- 5.6.2 Belgium
- 5.6.3 Denmark
- 5.6.4 France
- 5.6.5 Germany
- 5.6.6 Ireland
- 5.6.7 Italy
- 5.6.8 Netherlands
- 5.6.9 Norway
- 5.6.10 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, JVs, Funding)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Technologies
- 6.4.2 Hewlett Packard Enterprise
- 6.4.3 Lenovo Group
- 6.4.4 Cisco Systems
- 6.4.5 Fujitsu
- 6.4.6 Huawei Technologies
- 6.4.7 Inspur Group
- 6.4.8 International Business Machines (IBM)
- 6.4.9 Quanta Computer
- 6.4.10 Super Micro Computer
- 6.4.11 Atos SE
- 6.4.12 Advanced Micro Devices (AMD)
- 6.4.13 Intel Corporation
- 6.4.14 Nvidia Corp.
- 6.4.15 Foxconn / Hon Hai (including QCT)
- 6.4.16 Gigabyte Technology
- 6.4.17 MiTAC / TYAN
- 6.4.18 ASRock Rack
- 6.4.19 Inventec
- 6.4.20 Kingston Technology
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026年全球資料中心和伺服器半導體市場報告
 中國資料中心伺服器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美資料中心伺服器:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)印度資料中心伺服器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2032 年)日本資料中心伺服器:市佔率分析、產業趨勢與統計及成長預測(2026-2031)美國資料中心伺服器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)越南資料中心伺服器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞資料中心伺服器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 資料中心和伺服器半導體市場報告:趨勢、預測和競爭分析(至2035年)
 資料中心伺服器市場規模、佔有率、成長率、全球產業分析、區域趨勢以及 2026 年至 2034 年的預測。