


 |
市場調查報告書
商品編碼
2116665
義大利二手車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031)Italy Used Car - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
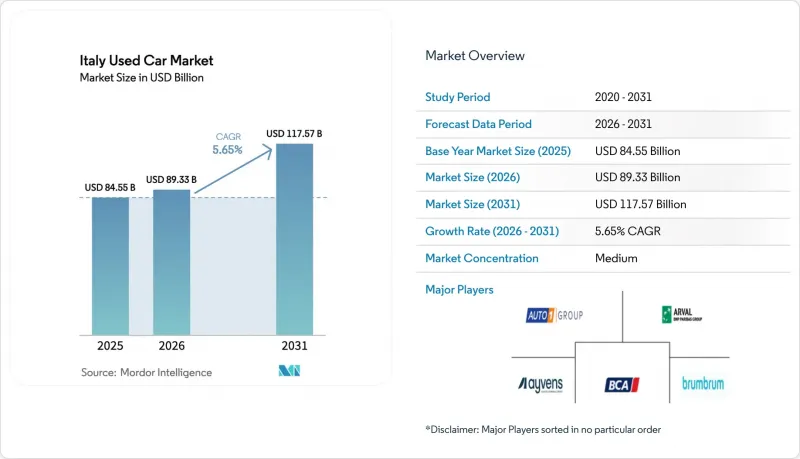
根據 Mordor Intelligence 估計,義大利二手車市場在 2026 年的價值將達到 893.3 億美元,高於 2025 年的 845.5 億美元,預計到 2031 年將達到 1,175.7 億美元。
預計 2026 年至 2031 年的複合年成長率為 5.65%。
本報告按車輛類型(掀背車、轎車、SUV、MPV、豪華車和跑車)、驅動方式(內燃機、混合動力、電動、液化石油氣和壓縮天然氣)、供應商類型(正規供應商和非正規供應商)、銷售管道(線上和線下)以及車輛年份(0-3年、4-6年和更久)進行細分。市場預測以美元計價。
義大利二手車市場的趨勢與洞察
由於新車價格飆升,市場需求正轉向二手車。
2025年初,由於汽車製造商優先生產利潤更高的車型,二手車註冊量與新車註冊量的比例上升,導致許多家庭難以負擔新車。這種需求轉變使得售價在9,000歐元至15,000歐元之間的符合歐盟6排放標準的汽油車和輕度混合動力車更受歡迎,因為該價位區間的庫存流動性較高。這種轉變在Lombardia和Piemonte地區尤為明顯,這兩個地區受2025年柴油車排放法規的影響最為嚴重,預計這種趨勢將持續推動義大利二手車市場在2026年之前的整體成長。
線上二手車平台激增
數位市場為本地經銷商提供了以往難以企及的全國性曝光機會,一家大型入口網站預計到2024年用戶將達到100萬人。點擊式轉換工具、內建貸款模擬器和檢驗的賣家評級,在縮短交易時間的同時,也提高了交易透明度。最熟悉數位購物的都市區千禧世代,正在將義大利的二手車市場拓展到區域之外,並加速南北地區二手車價格的趨同。
缺乏標準化的車輛歷史資料庫
在義大利,由於缺乏統一的全國車輛所有權登記系統,消費者仍然依賴分散的車輛服務記錄,這造成了資訊鴻溝,削弱了買家對純線上交易的信心。雖然利用人工智慧影像識別技術檢驗車輛外觀損傷的保險科技工具正在湧現,但其廣泛應用取決於監管協調和經銷商的合作(mdpi.com)。在此之前,義大利二手車市場的成長將持續緩慢,因為謹慎的買家會限制預算,並且只選擇經過認證的車輛。
細分市場分析
SUV正在引領高階市場的發展。預計到2025年,SUV將佔義大利汽車總銷量的41.25%,年複合成長率達7.12%,並有望繼續保持在義大利二手車市場的領先地位。像Jeep Avenger這樣的緊湊型跨界車,既能滿足都市區的實用性,又能滿足消費者對高離地間隙和安全感的追求。
以飛雅特熊貓為代表的掀背車仍然是注重預算的買家的首選,但其市場佔有率正被SUV蠶食,後者正在縮小兩車在燃油效率方面的差距。在高階市場,瑪莎拉蒂和阿爾法羅密歐的車型受到產量波動的影響,但它們依然秉承著義大利的卓越性能傳統,並支撐著一個規模小規模但利潤豐厚的細分市場。同時,MPV滿足了大家庭的需求,但正面臨來自SUV的競爭,這進一步加劇了義大利二手車市場車輛偏好兩極化的現狀。
電動車的激增將挑戰內燃機汽車的主導地位。到2025年,內燃機汽車仍將佔交易量的84.10%,但電池式電動車(BEV)預計將以17.54%的複合年成長率成長,超過所有其他動力傳動系統。混合動力汽車憑藉著Stellantis的領先優勢,受到受低排放氣體法規限制的都市區通勤者的青睞,因為它們既能提供純電動駕駛功能,又無需擔心續航里程。穩定的殘值、不斷擴展的充電基礎設施和延長的電池保固降低了擁有風險。液化石油氣(LPG)和壓縮天然氣(CNG)汽車在注重成本的農村駕駛者中仍然有需求,但它們正面臨基礎設施萎縮的困境,其在義大利二手車市場整體佔有率正在逐漸下降。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 由於新車價格飆升,市場需求正轉向二手車。
- 線上二手車平台激增
- 擴大 OEM 認證二手車計劃
- 租賃到期導致車輛歸還數量激增,從而推高了車輛供應。
- 這項以環保獎勵為基礎的以舊換新計劃,正在增加價格適中的內燃機 (ICE) 汽車的庫存。
- 基於遠端資訊處理的車輛評估可增強買家信心。
- 市場限制因素
- 缺乏標準化的車輛歷史資料庫
- 低排放氣體區會抑制老舊柴油車的銷售。
- 藍籌股流向東歐
- 人手不足導致回收成本上升
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按車輛類型
- 掀背車
- 轎車
- SUV
- MPV
- 豪華轎車和跑車
- 透過推進力
- 內燃機(汽油/柴油)
- 混合
- 電的
- LPG/CNG
- 依供應商類型
- 分類
- 非組織性的
- 透過分銷管道
- 線上
- 離線
- 按車輛年齡
- 0-3歲
- 4-6年
- 7-10歲
- 超過10年
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Auto1 Group Italy
- Penske Automotive Italy
- Brumbrum
- Cavauto Group
- BCA Italia
- Arval Italia
- ALD Automotive Italia
- LeasePlan Italia
- Subito Motors
- AutoScout24 Italia
- Carvago
- Denicar FCA
- Das WeltAuto Italy
- Renault Selection Italy
- Toyota Plus Italia
- Stellantis SPOTICAR Italy
第7章 市場機會與未來展望
According to Mordor Intelligence, Italy used car market size in 2026 is estimated at USD 89.33 billion, growing from 2025 value of USD 84.55 billion with 2031 projections showing USD 117.57 billion, growing at 5.65% CAGR over 2026-2031.
This report is Segmented by Car Type (Hatchback, Sedan, SUV, MPV, and Luxury and Sports), Propulsion (Internal Combustion Engine, Hybrid, Electric, and LPG and CNG), Vendor Type (Organized and Unorganized), Distribution Channel (Online and Offline), and Vehicle Age (0-3 Years, 4-6 Years, and More). The Market Forecasts are Provided in Terms of Value (USD).
Italy Used Car Market Trends and Insights
Rising New-Car Prices Shift Demand to Used
The ratio of used-to-new registrations climbed in early 2025 as OEMs prioritized higher-margin models, pricing many households out of factory-fresh vehicles . This redirected demand favors Euro 6 petrol and mild-hybrid cars listed between EUR 9,000 and EUR 15,000, a price corridor where inventory remains fluid. The shift has been strongest in Lombardy and Piedmont, regions hit hardest by 2025 diesel restrictions, and is expected to sustain headline growth in the Italy used car market into 2026.
Proliferation of Online Used-Car Platforms
Digital marketplaces deliver national exposure previously unavailable to local dealers, with one leading portal counting of million users in 2024. Click-to-lead conversion tools, embedded financing calculators, and verified seller ratings compress transaction times while raising transparency. Urban millennials, the cohort most comfortable with digital buying, are extending the Italy used car market beyond regional boundaries, hastening price convergence among northern and southern provinces.
Limited Standardized Vehicle-History Databases
Italy relies on piecemeal service records instead of a unified national title registry, leaving gaps that erode buyer confidence during purely online transactions. Insurtech tools using AI image recognition to validate exterior damage are emerging, yet mass adoption hinges on regulatory harmonization and dealer cooperation mdpi.com. Until that occurs, cautious shoppers may restrict budgets or select certified stock only, modestly capping expansion in the Italy used car market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of OEM Certified-Pre-Owned Programs
- Surging Off-Lease Returns Fuel Supply
- Low-Emission Zones Discourage Older Diesel Purchases
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SUVs Drive Premium Positioning SUVs generated 41.25% of total 2025 sales and are forecast to advance at a 7.12% CAGR, retaining the top perch in the Italy used car market. Compact crossovers such as the Jeep Avenger benefit from urban practicality while matching lifestyle aspirations for ground clearance and perceived safety.
Hatchbacks, represented by the Fiat Panda's remain crucial for budget-oriented shoppers yet cede share to SUVs that narrow the efficiency gap. On the premium end, Maserati and Alfa Romeo vehicles fall victim to volatile production flows but uphold Italy's performance heritage, supporting a small high-margin niche. Meanwhile, MPVs cater to larger families but confront SUV cannibalization, reinforcing the two-tier demand curve that defines car-type preferences across the Italy used car market.
Electric Surge Challenges ICE Dominance ICE units delivered 84.10% of 2025 transactions, yet BEVs post a 17.54% forecast CAGR that outpaces every other powertrain. Hybrids leverage Stellantis leadership, adding electric operating capability without range concerns and winning urban commuters constrained by low-emission zones.Residual-value stabilization, expanded charging infrastructure, and extended battery warranties reduce ownership risk. LPG and CNG stay relevant among cost-conscious rural drivers but face infrastructure erosion, gradually compressing their footprint within the broader Italy used car market.
Complete Report Scope:
- By Car Type
- Hatchback
- Sedan
- SUV
- MPV
- Luxury & Sports
- By Propulsion
- Internal Combustion Engine (Petrol/Diesel)
- Hybrid
- Electric
- LPG/CNG
- By Vendor Type
- Organized
- Unorganized
- By Distribution Channel
- Online
- Offline
- By Vehicle Age
- 0-3 Years
- 4-6 Years
- 7-10 Years
- More than 10 Years
List of Companies Covered in this Report:
- Auto1 Group Italy
- Penske Automotive Italy
- Brumbrum
- Cavauto Group
- BCA Italia
- Arval Italia
- ALD Automotive Italia
- LeasePlan Italia
- Subito Motors
- AutoScout24 Italia
- Carvago
- Denicar FCA
- Das WeltAuto Italy
- Renault Selection Italy
- Toyota Plus Italia
- Stellantis SPOTICAR Italy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising New-Car Prices Shift Demand to Used
- 4.2.2 Proliferation of Online Used-Car Platforms
- 4.2.3 Expansion of OEM Certified-Pre-Owned Programs
- 4.2.4 Surging Off-Lease Returns Fuel Supply
- 4.2.5 Eco-Incentive Trade-Ins Boost Affordable ICE Stock
- 4.2.6 Telematics-Based Vehicle Scoring Lifts Buyer Trust
- 4.3 Market Restraints
- 4.3.1 Limited Standardized Vehicle-History Databases
- 4.3.2 Low-Emission Zones Discourage Older Diesel Purchases
- 4.3.3 Export Outflow of Quality Stock to Eastern Europe
- 4.3.4 Rising Reconditioning Cost from Labour Shortages
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD Billion)
- 5.1 By Car Type
- 5.1.1 Hatchback
- 5.1.2 Sedan
- 5.1.3 SUV
- 5.1.4 MPV
- 5.1.5 Luxury & Sports
- 5.2 By Propulsion
- 5.2.1 Internal Combustion Engine (Petrol/Diesel)
- 5.2.2 Hybrid
- 5.2.3 Electric
- 5.2.4 LPG/CNG
- 5.3 By Vendor Type
- 5.3.1 Organized
- 5.3.2 Unorganized
- 5.4 By Distribution Channel
- 5.4.1 Online
- 5.4.2 Offline
- 5.5 By Vehicle Age
- 5.5.1 0-3 Years
- 5.5.2 4-6 Years
- 5.5.3 7-10 Years
- 5.5.4 More than 10 Years
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.4.1 Auto1 Group Italy
- 6.4.2 Penske Automotive Italy
- 6.4.3 Brumbrum
- 6.4.4 Cavauto Group
- 6.4.5 BCA Italia
- 6.4.6 Arval Italia
- 6.4.7 ALD Automotive Italia
- 6.4.8 LeasePlan Italia
- 6.4.9 Subito Motors
- 6.4.10 AutoScout24 Italia
- 6.4.11 Carvago
- 6.4.12 Denicar FCA
- 6.4.13 Das WeltAuto Italy
- 6.4.14 Renault Selection Italy
- 6.4.15 Toyota Plus Italia
- 6.4.16 Stellantis SPOTICAR Italy
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 中國二手車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印尼二手車金融:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)中東和非洲二手車市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)印尼二手車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031)新加坡二手車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031)法國二手車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)英國二手車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031)西班牙二手車市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031)馬來西亞二手車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)東南亞二手車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)