


 |
市場調查報告書
商品編碼
2163483
西班牙乙烯基壁紙:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Spain Vinyl Wallpaper - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
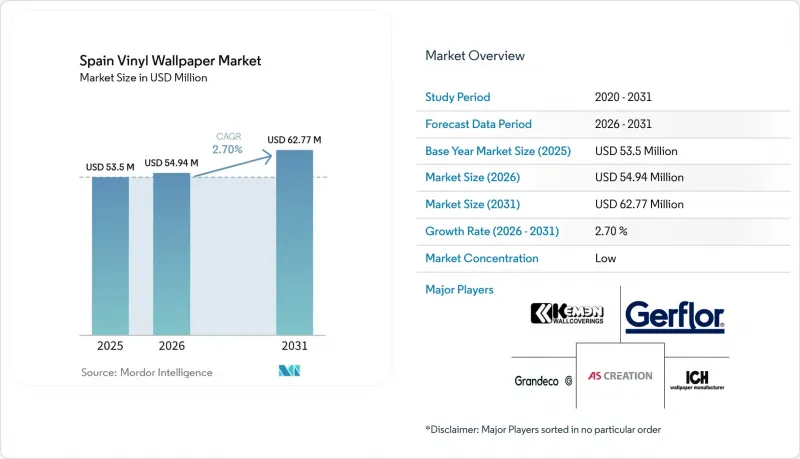
根據 Mordor Intelligence 預測,西班牙乙烯基壁紙市場規模將從 2025 年的 5,350 萬美元成長到 2026 年的 5,494 萬美元,到 2031 年將達到 6,277 萬美元,2026 年至 2031 年的複合年預計成長率為 2.70%。
西班牙乙烯基壁紙市場的趨勢和洞察
翻新和整修需求
西班牙預計到2025年將有190萬戶家庭進行住宅維修,這意味著十分之三的家庭將進行某種形式的住宅維修。由於牆面裝飾通常是在房間整體維修時選擇的,西班牙的乙烯基壁紙市場因此受益。在西班牙2,710萬套住宅中,超過95%建於2009年之前,這意味著大量住宅存量亟需進行外部和結構性維修。用於提高能源效率的資金將使隔熱工程、暖氣系統維修和室內裝修能夠在一次翻新工程中同時進行。西班牙的《2026-2030年國家住宅計畫》(皇家法令第326/2026號)將其70億歐元預算中的至少30%(約21億歐元)分配給房屋維修。
飯店設施維修及與旅遊業相關的室內裝修工程。
旅遊業在西班牙乙烯基壁紙市場中繼續扮演著至關重要的角色,因為酒店經營者需要定期翻新客房和公共區域。預計2025年,到訪西班牙的外國旅客數量將達到9,680萬人次,外國遊客的消費將達到1,347億歐元,比2024年增加6.8%。西班牙國營酒店集團Paradores制定了一項2.5億歐元的翻新計劃,計劃在2028年覆蓋其一半以上的酒店。梅利亞索爾托雷莫利諾斯酒店綜合大樓於2025年完成了一項耗資5,200萬歐元的維修。此類專案對能夠提供經認證、高度耐用且符合專案規模的壁材的供應商青睞有加。能夠最大限度減少飯店關閉時間的產品也具有優勢,因為可靠的施工進度至關重要。
遵守PVC和化學品安全法規的成本
REACH法規加強了對PVC產品製造商和進口商的合規要求。歐盟法規(EU) 2023/923規定,PVC材料中的鉛含量必須低於0.1%(重量百分比),超過此閾值的產品將於2024年11月28日後禁止在歐盟市場銷售。在西班牙乙烯基壁紙市場,供應商在逐步淘汰含鉛穩定劑的過程中,因文件編制和配方變更而承擔了額外的成本。根據VinylPlus的報告顯示,REACH法規及相關工具仍在持續審查某些PVC添加劑的處理方式。對於從歐盟以外地區購買的小規模經銷商,在貨物進入歐盟之前驗證其合規性是一項特別沉重的負擔。這些成本對於低價產品類型可能難以負擔。
細分市場分析
2025年,乙烯基塗佈紙佔據了西班牙乙烯基壁紙市場43%的佔有率。其低廉的價格和「直接貼牆」的便利性促使專業安裝人員廣泛使用。這種壁紙適用於西班牙現有住宅存量中常見的舊式石膏和混凝土牆面。另一方面,實心乙烯基壁紙在需要高耐磨性的應用中仍然發揮著重要作用,例如商業、醫療和住宅設施。不織布乙烯基壁紙在中高階住宅項目中越來越受歡迎,因為它可以直接貼牆,從而縮短安裝時間。這種效率在業主一次整修多個房間的大規模翻新項目中往往是首要考慮因素。 2025年,一次全面翻新的平均支出將達到32,000歐元。這些選項表明,價格、牆面狀況和安裝方式決定了產品組合。
不織布乙烯基和非PVC不織布基材在住宅DIY專案中市場佔有率不斷成長,抑制了乙烯基塗層紙的成長。預計2026年至2031年間,乙烯布將以4.75%的複合年成長率成長,是所有產品類型中成長率最高的。酒店項目對公共空間紋理豐富且經久耐用的飾面材料的需求推動了這一細分市場的發展。高階規格產品無需依賴大規模標準印刷,即可助力精品酒店的定位。數位印刷特種產品雖然產量仍較小,但對設計師和獨立飯店而言仍具有潛力。商用項目的產品選擇必須考慮消防安全聲明和清潔要求。經認證的布基產品既能滿足這些標準,又能提供更優質的表面效果。因此,在西班牙乙烯基壁紙市場,高階規格產品的競爭預計會比乙烯基塗佈紙市場相對較小。這種差異為符合標準的供應商提供了一條通往更高附加價值規格的清晰路徑。
截至2025年,傳統型和非自黏型乙烯基壁紙產品佔據了西班牙乙烯基壁紙市場72%的佔有率。專業安裝人員在裝修採購中仍扮演著核心角色,41%的裝修買家依賴值得信賴的業內相關人員的推薦。自黏型產品非常適合老舊建築中紋理粗糙或不平整的表面。對於在大空間施工的安裝人員來說,自黏型產品也是一種熟悉的安裝方式。不織布背襯乙烯基壁紙改進了傳統的安裝方法,可以直接將黏合劑塗抹在牆面上,從而減少錯誤和材料浪費。在安裝品質和表面接受度至關重要的場合,傳統產品仍將發揮重要作用。它們既有的地位將限制專業項目中其他替代品的採用。
自黏式和即撕即貼式乙烯基壁紙預計到2031年將以4.99%的複合年成長率成長。這類壁紙適合需要可逆式室內裝修的短期租賃房產的居住者和業主。西班牙全國短期租賃登記制度原計劃於2025年7月強制實施,但最高法院於2026年5月宣布該制度無效,不過區域旅遊許可證仍將繼續有效。視覺化工具的普及,使客戶能夠在購買前評估顏色和圖案,這將促進線上銷售。即撕即貼式產品簡化了安裝流程,並避免了搬離時牆面修補的費用。憑藉這些優勢,自黏式產品在西班牙乙烯基壁紙市場的B2C領域佔有重要地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 房屋翻新改造的需求
- 飯店設施維修及與旅遊業相關的室內裝修工程。
- 頻繁使用的室內空間對耐洗性和耐用性的要求
- 數位壁紙和客製化壁紙的發展
- 採用適合出租房屋的「剝離式」類型。
- 更快的飯店整修週期,對營運的干擾更小。
- 市場限制因素
- 與遵守PVC和化學品安全法規相關的成本
- 由於不織布和油漆等替代品的出現,競爭加劇。
- 有關承包工程耐火性能的文件
- 老舊住宅存量地基和牆壁狀況的限制因素
- 產業價值鏈分析
- 波特五力分析
- 深入了解產業最新趨勢與創新
- 近期產業趨勢分析(新產品發布、策略性舉措、投資、合作、合資、業務擴張、併購等)
第5章 市場規模與成長預測
- 依產品類型/結構類型
- 實心乙烯基壁紙
- 乙烯基塗佈紙
- 帶襯裡的乙烯基
- 不織布乙烯基壁紙
- 其他產品類型
- 按安裝類型
- 常規/非黏合型
- 自黏/剝離式乙烯基壁紙
- 透過使用
- 新建工程
- 維修和改造
- 最終用戶
- 住宅
- 客廳
- 廚房
- 臥室
- 浴室
- 兒童房
- 商業的
- 住宅
- 透過分銷管道
- B2C通路
- 大賣場和超級市場
- 壁紙專賣店
- 家居建材商店
- 線上
- 本地零售商(非正規通路)
- 其他分銷管道
- B2B通路(承包商、建築商、室內設計師、建築師、專案採購和機構銷售)
- B2C通路
- 按地區
- 安達盧西亞
- 加泰隆尼亞
- 馬德里
- 瓦倫西亞
- 加那利群島
- 西班牙其他地區
第6章 競爭情勢
- 市場集中度概述
- 策略趨勢
- 市佔率分析
- 公司簡介
- AS Creation Tapeten AG
- Sanderson Design Group plc
- Grandeco Wallfashion Group Belgium NV
- Tapetenfabrik Gebr. Rasch GmbH & Co. KG
- Erismann & Cie. GmbH
- Graham & Brown Ltd
- Arte International
- Komar Products GmbH
- Marburger Tapetenfabrik JB Schaefer GmbH & Co. KG
- Muraspec
- Koroseal Interior Products
- Wall & deco Srl
- Elitis
- Kemen Wallcoverings/Vinelus, SA
- ICH Papeles Pintados
- Gerflor
第7章 市場機會與未來展望
According to Mordor Intelligence, the Spain vinyl wallpaper Market size is expected to grow from USD 53.5 million in 2025 to USD 54.94 million in 2026 and is forecast to reach USD 62.77 million by 2031, growing at a 2.70% CAGR during 2026-2031.
Spain Vinyl Wallpaper Market Trends and Insights
Renovation and Remodeling Demand
Spain recorded 1.9 million home renovation interventions in 2025, and 3 in 10 households made some form of home improvement. The Spanish vinyl wallpaper market benefits because wall finishes are often selected during wider room upgrades. More than 95% of Spain's 27.1 million homes were built before 2009, which leaves a large stock requiring cosmetic and structural work. Funding directed at energy efficiency can bring insulation, heating, and decorative work into the same renovation visit. Spain's 2026-2030 State Housing Plan (Royal Decree 326/2026) allocates at least 30% of its EUR 7 billion budget, about EUR 2.1 billion, to building rehabilitation..
Hospitality Refurbishment and Tourism-Linked Fit-Out
Tourism remains important to the Spanish vinyl wallpaper market because hotel owners must refresh guest rooms and shared areas regularly. International tourist spending reached EUR 134.7 billion in 2025, up 6.8% from 2024, after Spain received 96.8 million international visitors. Paradores has a EUR 250 million refurbishment plan covering more than half of its network before 2028. The Melia Sol Torremolinos complex completed a EUR 52 million renovation in 2025. These projects favor suppliers that can provide certified, durable wallcoverings at the project scale. The need for reliable installation schedules also favors products that reduce closure time for hotels.
PVC and Chemical-Safety Compliance Costs
REACH requirements have raised compliance demands for manufacturers and importers of PVC-based products. Regulation (EU) 2023/923 sets a lead limit of 0.1% by weight in PVC material, and products above that threshold could not be placed on the EU market from November 28, 2024. The Spain vinyl wallpaper market faces added documentation and reformulation costs as suppliers move away from lead stabilizers. VinylPlus reported that the treatment of certain PVC additives remains under review through REACH and related tools. Smaller distributors that source from outside the European Union face a particular burden in confirming compliance before goods enter the region. These costs can be harder to absorb in lower-priced product categories.
Other drivers and restraints analyzed in the detailed report include:
- Washability and Durability Requirements in High-Traffic Interiors
- Growth of Digital and Made-to-Measure Wallcoverings
- Competition from Nonwoven and Paint Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vinyl-coated paper held 43% of the Spanish vinyl wallpaper market share in 2025. Its lower price point and compatibility with paste-to-wall methods support broad use by professional installers. The format can suit older plaster and concrete surfaces found across Spain's established housing stock. Solid vinyl remains relevant where commercial, healthcare, and institutional settings require strong scrub resistance. Nonwoven vinyl is gaining acceptance in mid- and premium residential projects because paste-to-wall installation can reduce labor time. Comprehensive renovation projects can favor this efficiency when homeowners upgrade several rooms at once. Average spending for a full renovation reached EUR 32,000 in 2025. These choices show that price, wall condition, and installation practice determine the product mix.
Nonwoven vinyl and non-PVC nonwoven substrates are gaining ground in residential DIY projects, which caps vinyl-coated paper's growth. Fabric-backed vinyl is forecast to expand at a 4.75% CAGR during 2026-2031, the highest rate among product types. This segment benefits from hotel projects that seek textured, durable finishes for public spaces. Premium formats can support boutique-style hotel positioning without relying on large standard print runs. Digitally printed specialty products remain smaller in volume but offer scope for designers and independent hotels. Product selection in contract projects must account for fire-performance declarations and cleaning requirements. Certified fabric backed products can meet these criteria while offering a more premium surface finish. The Spain vinyl wallpaper market industry is therefore likely to see lower crowding in premium formats than in vinyl coated paper. This difference gives compliant suppliers a clearer route to higher-value specifications.
Traditional and non self-adhesive products held 72% of the Spain vinyl wallpaper market size in 2025. Professional contractors remain central to renovation purchasing, and 41% of renovation buyers relied on recommendations from trusted trade contacts. Paste-applied formats work well on textured and uneven surfaces in older buildings. They also provide installers with a familiar method for large room projects. Nonwoven-backed vinyl has improved the traditional route by allowing paste-to-wall application. This can reduce error rates and material waste. Traditional products will remain important where installation quality and surface tolerance matter most. Their established position limits the speed of substitution in professional projects.
Self-adhesive and peel-and-stick vinyl is forecast to grow at a 4.99% CAGR through 2031. The format suits renters and short-term rental owners who need reversible room updates. Spain's national short-term rental registry, mandatory from July 2025, was annulled by the Supreme Court in May 2026, although regional tourist licences continue to apply. Online sales benefit when visualization tools help buyers assess colors and patterns before purchase. Peel-and-stick products can reduce labor needs and avoid wall-repair costs at move-out. These qualities make self-adhesive products important to the B2C side of the Spain vinyl wallpaper market.
Complete Report Scope:
- By Product Type/Construction Type
- Solid Vinyl Wallpaper
- Vinyl Coated Paper
- Fabric Backed Vinyl
- Non-Woven Vinyl Wallpapers
- Other Product Type
- By Installation Type
- Traditional/Non-Self-Adhesive
- Self-Adhesive / Peel-and-Stick Vinyl Wallpaper
- By Application
- New Construction
- Renovation and Remodeling
- By End User
- Residential
- Living Room
- Kitchen
- Bedroom
- Bathroom
- Kids Room
- Commercial
- Residential
- By Distribution Channel
- B2C Channels
- Hypermarkets and Supermarkets
- Specialty Wallpaper Stores
- Home Centers
- Online
- Local Shops (unorganized channels)
- Other Distribution Channels
- B2B Channels (Contractors and Installers, Interior Designers and Architects, Project Procurement and Institutional Sales)
- B2C Channels
- By Geography
- Andalusia
- Catalonia
- Madrid
- Valencia
- Canary Islands
- Rest of Spain
List of Companies Covered in this Report:
- A.S. Creation Tapeten AG
- Sanderson Design Group plc
- Grandeco Wallfashion Group Belgium NV
- Tapetenfabrik Gebr. Rasch GmbH & Co. KG
- Erismann & Cie. GmbH
- Graham & Brown Ltd
- Arte International
- Komar Products GmbH
- Marburger Tapetenfabrik J. B. Schaefer GmbH & Co. KG
- Muraspec
- Koroseal Interior Products
- Wall&deco Srl
- Elitis
- Kemen Wallcoverings / Vinelus, SA
- ICH Papeles Pintados
- Gerflor
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Renovation and Remodeling Demand
- 4.2.2 Hospitality Refurbishment and Tourism-Linked Fit-Out
- 4.2.3 Washability and Durability Requirements in High-Traffic Interiors
- 4.2.4 Growth of Digital and Made-to-Measure Wallcoverings
- 4.2.5 Rental-Friendly Peel-and-Stick Adoption
- 4.2.6 Faster, Lower-Disruption Hotel Renovation Cycles
- 4.3 Market Restraints
- 4.3.1 PVC and Chemical-Safety Compliance Costs
- 4.3.2 Competition from Nonwoven and Paint Alternatives
- 4.3.3 Fire-Performance Documentation for Contract Projects
- 4.3.4 Substrate and Wall-Condition Constraints in Older Housing Stock
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Insights into the Latest Trends and Innovations in the Industry
- 4.7 Insights into the Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Industry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type/Construction Type
- 5.1.1 Solid Vinyl Wallpaper
- 5.1.2 Vinyl Coated Paper
- 5.1.3 Fabric Backed Vinyl
- 5.1.4 Non-Woven Vinyl Wallpapers
- 5.1.5 Other Product Type
- 5.2 By Installation Type
- 5.2.1 Traditional/Non-Self-Adhesive
- 5.2.2 Self-Adhesive / Peel-and-Stick Vinyl Wallpaper
- 5.3 By Application
- 5.3.1 New Construction
- 5.3.2 Renovation and Remodeling
- 5.4 By End User
- 5.4.1 Residential
- 5.4.1.1 Living Room
- 5.4.1.2 Kitchen
- 5.4.1.3 Bedroom
- 5.4.1.4 Bathroom
- 5.4.1.5 Kids Room
- 5.4.2 Commercial
- 5.4.1 Residential
- 5.5 By Distribution Channel
- 5.5.1 B2C Channels
- 5.5.1.1 Hypermarkets and Supermarkets
- 5.5.1.2 Specialty Wallpaper Stores
- 5.5.1.3 Home Centers
- 5.5.1.4 Online
- 5.5.1.5 Local Shops (unorganized channels)
- 5.5.1.6 Other Distribution Channels
- 5.5.2 B2B Channels (Contractors and Installers, Interior Designers and Architects, Project Procurement and Institutional Sales)
- 5.5.1 B2C Channels
- 5.6 By Geography
- 5.6.1 Andalusia
- 5.6.2 Catalonia
- 5.6.3 Madrid
- 5.6.4 Valencia
- 5.6.5 Canary Islands
- 5.6.6 Rest of Spain
6 Competitive Landscape
- 6.1 Market Concentration Overview
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 A.S. Creation Tapeten AG
- 6.4.2 Sanderson Design Group plc
- 6.4.3 Grandeco Wallfashion Group Belgium NV
- 6.4.4 Tapetenfabrik Gebr. Rasch GmbH & Co. KG
- 6.4.5 Erismann & Cie. GmbH
- 6.4.6 Graham & Brown Ltd
- 6.4.7 Arte International
- 6.4.8 Komar Products GmbH
- 6.4.9 Marburger Tapetenfabrik J. B. Schaefer GmbH & Co. KG
- 6.4.10 Muraspec
- 6.4.11 Koroseal Interior Products
- 6.4.12 Wall&deco Srl
- 6.4.13 Elitis
- 6.4.14 Kemen Wallcoverings / Vinelus, SA
- 6.4.15 ICH Papeles Pintados
- 6.4.16 Gerflor
7 Market Opportunities & Future Outlook
- 7.1 Hospitality-Grade Removable Vinyl
- 7.2 Digitally Printed Small-Batch Collections for Independent Designers

 商用壁紙:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)布藝壁紙:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)不織布壁紙:市場佔有率分析、產業趨勢及統計、成長預測(2026-2031)印度壁紙:市場佔有率分析、產業趨勢與統計、成長預測(2025-2030)乙烯基壁紙:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 乙烯基壁紙市場規模、佔有率和成長分析:按產品類型、設計/圖案、價格範圍、應用、最終用戶細分市場、分銷管道和地區分類-2026-2033年產業預測
 壁紙市場:按產品類型、應用、銷售管道和地區分類壁紙:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026-2034年全球壁紙市場規模、佔有率、趨勢和成長分析報告
 日本壁紙市場規模、佔有率、趨勢及預測(按壁紙類型、通路、最終用戶和地區分類),2026-2034年