


 |
市場調查報告書
商品編碼
2154391
廢棄物預處理:替代燃料和原料(AFRs):市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Waste Pre-processing For Alternate Fuel and Raw Materials (AFR) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,用於生產替代燃料和原料的廢棄物預處理市場規模預計將從 2025 年的 20.2 億美元成長到 2026 年的 22.5 億美元,到 2031 年達到 33.3 億美元,2026 年至 2031 年的複合成長率為 8.14%。
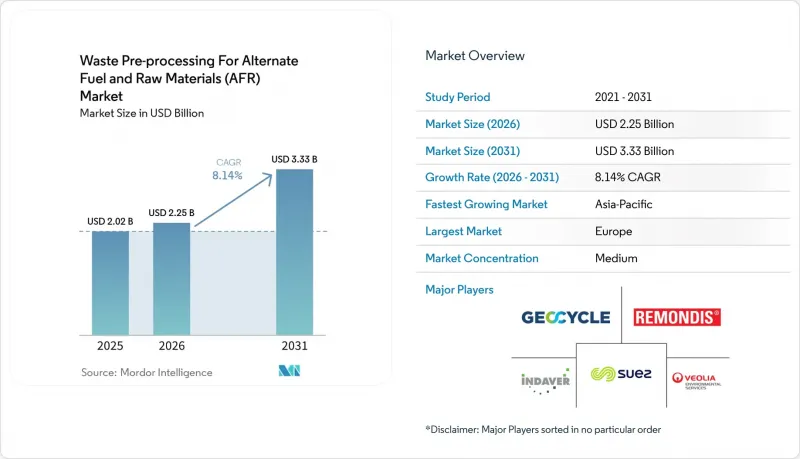
全球廢棄物預處理在替代燃料和原料(AFRs)領域的趨勢和見解
石化燃料的替代和水泥的脫碳
水泥生產中30%的排放源自於燃料燃燒,因此燃料替代已成為水泥廠的直接營運重點。當工廠需要的是客製化燃料而非隨意接收廢棄物時,替代燃料和廢棄物市場將會受益。據全球水泥聯盟(GCCA)稱,燃料品質要求目前包括對熱值、鹼含量、氯化物含量和水分控制的限制。海德堡材料公司已設定目標,在其超過50%的營運中使用替代燃料,並計劃在其超過30%的水泥熟料廠中將替代燃料的使用率提高到至少45%。這些目標催生了對能夠提供高熱值、規格一致的固態回收燃料的供應商的需求。此外,對供應和計量設施的投資正在推動多年期合約關係的建立,而不是一次性廢棄物交易。
強制減少廢棄物掩埋量並實施循環經濟
歐洲的掩埋法規正引導更多廢棄物走向回收和協同處理途徑。 《廢棄物框架指令》支援依照預防、再利用、回收、再生和處置的順序進行處理。隨著掩埋處置受到更多限制,用於替代燃料和原料市場的廢棄物預處理將在地方層面獲得更大的處理量。 2026/1703號法規限制了用於回收的混合城市廢棄物的出口,從而減少了廢物在國外處置的目的地。此外,法國更新了固態再生燃料(SRF)的生產要求,有效期至2025年。這些法規鼓勵能夠將難以處理的市政和工業廢棄物轉化為符合標準的燃料的設施。競爭性處置途徑成本的上升可能會提高低熱值污泥和建築殘渣處理的經濟效益。這將擴大可用於替代燃料和原料市場的廢棄物預處理的材料範圍,前提是必要的技術控制措施到位。
原料波動與窯爐穩定性風險
水分含量、熱值和灰分組成的波動會導致殘餘廢棄物無法滿足主燃燒器的燃料需求。窯爐燃燒器技術研究表明,主燃燒器穩定燃燒需要低於10%的水分含量。高水分燃料會損害煅燒爐的穩定性,並導致水泥熟料燃燒不均勻。因此,在許多城市固態廢棄物和農業殘餘物處理流程中,乾燥和水分調節是必不可少的。沒有生物乾燥或熱乾燥設施的營運商在為替代燃料和原料市場提供高品質燃料的廢棄物預處理合約方面競爭力較弱。隨著品管要求的提高,進料成分的變化可能會對利潤率造成壓力。
細分市場分析
截至2025年,都市固態廢棄物佔替代燃料和原料廢棄物預處理市場佔有率的33.4%。其龐大的數量和接近性城市收集系統的地理位置,使得處理設施可以建在城市廢棄物流附近。工業廢棄物由於其成分通常更均一且污染程度較低,廢棄物有用的原料。這種均一性減少了生產高熱值固態回收燃料所需的加工步驟。建築和拆除木材正逐漸成為水泥窯的顆粒原料。建築和拆除回收協會(CDRA)與美國水泥協會(ACA)和環境保護署(EPA)合作,於2025年至2026年研究將清潔纖維素生質能歸類為無害二次材料。廢舊輪胎即使經過破碎和除鐵處理,其熱值仍接近煤炭。污水污泥需要進行生物乾燥才能達到適合混燒的能量密度。雖然這些原料需求穩定,但與生質能殘渣相比,其成長前景較低。
針對生質能和農業廢棄物的替代燃料和原料廢棄物預處理市場預計到2031年將以9.3%的複合年成長率成長。農業殘餘物可望擴大亞太和拉丁美洲水泥生產商的原料基礎。 2025年的一項研究表明,生質能和農業燃料可提供高達煤炭70%的能量,並且在測試條件下,其氯化氫和戴奧辛排放量更低。 Holcim Mexico於2026年8月在科利馬州啟動了一座生質能設施的運作。該設施利用窯爐回收的熱量,每天乾燥220噸甘蔗渣,然後將其粉碎並用於混燒。中國的T/CIECCPA 129-2026標準規定了水泥窯所使用生質能燃料的熱值、水分含量、灰分組成和粒徑要求。這些要求有利於那些能夠應對農業原料季節性波動的設施。此外,這也有助於將供應來源從未經加工的殘渣轉變為供應符合加工燃料規格的生質能。
區域分析
2025年,歐洲在替代燃料和原料的廢棄物預處理市場中佔據37.4%的佔有率。該地區已製定了廢棄物聯合處理的規則和商業性安排。 2026/1703號法規限制了用於回收的混合城市廢棄物的出口,並將殘渣導向國內市場。奧地利、比利時和德國是水泥替代率最高的國家之一。波蘭、西班牙和義大利的替代燃料利用率低於歐洲平均水平(58%),這為新增加工能力的引入留下了空間。 2026年7月,Paprec和Vicat在法國開設了「ALTereNATIVE」工廠,投資額達1,540萬歐元。該工廠體現了一種區域供應鏈模式,將加工能力與當地水泥買家連接起來。
預計到2031年,亞太地區將以9.5%的複合年成長率成長。中國、印度、印尼和越南等國的廢棄物量不斷增加,水泥產能也在擴張,這些因素共同推動了替代燃料和原料的廢棄物預處理市場發展,但供應品質仍然依賴當地的收集和分類系統。 KHD於2025年12月在康迪集團寶山工廠運作了其第二套「熱解轉子」系統。該設施在高濕度條件下每小時可處理18噸生質能和都市固態廢棄物。印尼的垃圾焚化發電項目發展計畫可能會促進預處理燃料所需正規基礎設施的擴建。印度每天產生15萬噸城市固態廢棄物,但由於分類系統不完善和原料品質不穩定,其短期用於水泥生產受到限制。該地區的商業機會取決於在原料運往水泥廠之前,如何改善收集、分類和品管。
南美洲、中東和非洲雖然規模較小,但潛力巨大。 GeoCycle計畫在2030年在拉丁美洲投資1.25億美元,預計到2025年,14個處理設施將處理總合100萬噸廢棄物。該模式將水泥生產和廢棄物管理整合到單一供應鏈中。沙烏地阿拉伯和阿拉伯聯合大公國(舉措)正透過「水泥和混凝土突破計劃」推動一項支持將廢棄物作為替代燃料的政策框架。鑑於摩洛哥水泥產量和城市固態廢棄物產生量不斷成長,該國也具有發展潛力。研究表明,使用當地農業廢棄物灰燼可將非洲水泥的碳足跡減少高達40%。這將使未來的項目能夠將燃料製備與替代原料的使用聯繫起來。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 石化燃料的替代和水泥的脫碳
- 減少掩埋廢棄物和促進循環經濟的強制性要求。
- 對穩定、高熱值燃料的需求
- 擴大垃圾焚化發電汽電共生(CHP)產能
- 人工智慧驅動的分類和數位燃料追溯
- 替代原料與燃料預處理的整合
- 市場限制因素
- 與原料波動和窯爐穩定性相關的風險
- 預處理涉及高昂的資金和物流成本。
- 高熱值殘餘廢棄物的競爭
- 跨境廢棄物許可製度和法規的碎片化
- 供應鏈分析
- 波特五力分析
- 科技趨勢
- 監理情勢
- 投資分析
第5章 市場規模與成長預測
- 廢棄物類型
- 一般廢棄物(MSW)
- 工業廢棄物
- 商業廢棄物
- 建築和拆除廢棄物
- 污水污泥
- 舊輪胎
- 生質能和農業廢棄物
- 其他類型的廢棄物
- 預處理技術
- 機械分類和分離
- 破碎和研磨
- 排序和分類
- 磁選和渦流分離
- 空氣分離和彈道分離
- 光學和感測器分選
- 機械加工、生物加工和生物乾燥
- 乾燥和濕度控制
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 義大利
- 西班牙
- 英國
- 波蘭
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 印尼
- 越南
- 泰國
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 埃及
- 南非
- 摩洛哥
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Andusia Holdings Limited
- Beauparc Utilities Holdings Limited
- Biffa plc
- CEMEX, SAB de CV
- EEW Energy from Waste GmbH
- Enva Group Limited
- FCC Environment(UK)Limited
- Geminor AS
- Geocycle(Deutschland)GmbH
- Heidelberg Materials AG
- Holcim Ltd.
- Indaver NV
- Paprec Group SAS(Paprec)
- PreZero International GmbH
- Ragn-Sells AB
- REMONDIS SE & Co. KG
- Renewi plc(Renewi)
- SUEZ SA
- Veolia Environnement SA
- Vicat SA
第7章 市場機會與未來展望
According to Mordor Intelligence, the waste pre-processing for alternate fuel and raw materials market size is expected to increase from USD 2.02 billion in 2025 to USD 2.25 billion in 2026 and reach USD 3.33 billion by 2031, at a CAGR of 8.14% over 2026-2031.
Global Waste Pre-processing For Alternate Fuel and Raw Materials (AFR) Market Trends and Insights
Fossil-Fuel Substitution and Cement Decarbonization
Fuel combustion accounted for 30% of cement production emissions, making fuel replacement a direct operating priority for cement plants. The waste pre-processing for alternative fuels and raw materials market benefits when plants require engineered fuels instead of irregular waste deliveries. The GCCA states that fuel quality requirements now address calorific value, alkali content, chloride limits, and moisture control. Heidelberg Materials set a target above 50% for alternative fuel use and plans for more than 30% of its clinker plants to achieve at least 45% AFR use. These targets create demand for suppliers that can provide high-calorific solid recovered fuel at consistent specifications. Investment in feeding and dosing equipment also supports multi-year arrangements rather than one-time waste transactions.
Landfill Diversion and Circular-Economy Mandates
Europe's landfill rules are directing more residual material toward recovery and co-processing routes. The Waste Framework Directive supports prevention, reuse, recycling, recovery, and disposal in that order. The waste pre-processing for alternative fuels and raw materials market gains access to larger local volumes when landfilling becomes more restricted. Regulation 2026/1703 restricts exports of mixed municipal waste for recovery, which reduces overseas outlets for residual waste. France also updated requirements related to solid recovered fuel production during 2025. These rules encourage facilities that can turn difficult municipal and industrial streams into compliant fuels. Higher costs for competing disposal routes can improve the economics of processing lower-calorific sludge and construction residues. This increases the range of materials that can enter the waste pre-processing for alternative fuels and raw materials market when technical controls are in place.
Feedstock Variability and Kiln-Stability Risk
Variable moisture, calorific value, and ash composition can prevent residual waste from meeting main-burner fuel requirements. Research on kiln burner technology identifies moisture below 10% as necessary for stable main-burner combustion. High-moisture fuel can destabilize the calciner and cause uneven clinker burning. This makes drying and moisture conditioning necessary for many municipal solid waste and agricultural residue streams. Operators without biodrying or thermal drying equipment are less able to compete for premium fuel contracts in the waste pre-processing for alternative fuels and raw materials market. The need for tighter quality control can narrow margins when incoming materials change in composition.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Consistent High-Calorific Fuels and Energy Recovery Capacity
- AI-Enabled Sorting, Traceability, and Alternative Raw Materials Integration
- High Pre-Processing Capital, Logistics, and Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Municipal solid waste held 33.4% of the waste pre-processing for alternative fuels and raw materials market share in 2025. Its large volume and proximity to urban collection systems support the location of processing facilities near municipal waste flows. Industrial and commercial waste remains a useful input because its composition is often more uniform and less contaminated. That uniformity can reduce the processing steps needed to produce higher-calorific solid recovered fuel. Construction and demolition wood is emerging as a pellet feedstock for cement kilns. The Construction and Demolition Recycling Association worked with the American Cement Association and the EPA during 2025 and 2026 on non-hazardous secondary material classification for clean cellulosic biomass. Waste tires retain a heat value near that of coal after shredding and steel separation. Sewage sludge requires biodrying to reach an energy density suitable for co-firing. These inputs provide stable demand but have lower projected growth than biomass residues.
The waste pre-processing for alternative fuels and raw materials market size for biomass and agricultural waste is projected to grow at a 9.3% CAGR through 2031. Agricultural residues can broaden the feedstock base for cement producers in Asia-Pacific and Latin America. A 2025 study found that biomass and agricultural fuels could provide up to 70% of coal's energy content and showed low HCl and dioxin emissions under the tested conditions. Holcim Mexico commissioned a biomass facility in Colima during August 2026. The facility dries 220 tonnes per day of sugar bagasse with recovered kiln heat before grinding it for co-firing. China's T/CIECCPA 129-2026 standard sets requirements for calorific value, moisture, ash composition, and particle size for biomass fuels used in cement kilns. Such requirements favor facilities that can manage seasonal variation in agricultural inputs. They also shift biomass supply toward engineered fuel specifications rather than untreated residue delivery.
Complete Report Scope:
- By Waste Type
- Municipal Solid Waste (MSW)
- Industrial Waste
- Commercial Waste
- Construction and Demolition Waste
- Sewage Sludge
- Waste Tires
- Biomass and Agricultural Waste
- Other Waste Types
- By Pre-processing Technology
- Mechanical Sorting and Segregation
- Shredding and Size Reduction
- Screening and Classification
- Magnetic and Eddy-Current Separation
- Air and Ballistic Separation
- Optical and Sensor-Based Sorting
- Mechanical-Biological Treatment and Biodrying
- Drying and Moisture Conditioning
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe accounted for 37.4% of the waste pre-processing for alternative fuels and raw materials market share in 2025. The region has established rules and commercial arrangements for waste co-processing. Regulation 2026/1703 restricts mixed municipal waste exports for recovery and redirects residual material to domestic outlets. Austria, Belgium, and Germany have some of the highest cement substitution rates. Poland, Spain, and Italy remain below Europe's 58% average alternative fuel rate, leaving room for new processing capacity. Paprec and Vicat opened the EUR 15.4 million ALTereNATIVE plant in France during July 2026. The facility illustrates the regional supply-chain model that links processing capacity with a local cement offtaker.
Asia-Pacific is projected to grow at a 9.5% CAGR through 2031. The waste pre-processing for alternative fuels and raw materials market is supported by increasing waste volumes and cement capacity across China, India, Indonesia, and Vietnam, although supply quality still depends on local collection and segregation systems. KHD commissioned a second Pyrorotor system at Conch Group's Baoshan plant during December 2025. The installation processes shredded biomass and municipal solid waste at 18 tonnes per hour under high-moisture conditions. Indonesia's program for waste-to-energy projects can expand the formal infrastructure needed for prepared fuels. India generates 150,000 tonnes of municipal solid waste each day, but segregation gaps and variable feedstock quality limit near-term cement use. The region's opportunity depends on improving collection, sorting, and quality control before material reaches cement plants.
South America and the Middle East and Africa are smaller regions with meaningful potential. Geocycle planned USD 125 million of Latin American investment through 2030, supported by 14 facilities that processed nearly 1 million tonnes of waste during 2025. This model combines cement operations and waste processing within one supply chain. Saudi Arabia and the UAE support policy frameworks for waste as an alternative fuel through the Cement and Concrete Breakthrough initiative. Morocco also offers potential as cement production and municipal solid waste volumes grow. Research found that locally sourced agricultural waste ashes could reduce the carbon footprint of African cement by up to 40%. This can link fuel preparation with alternative raw material use in future projects.
- Andusia Holdings Limited
- Beauparc Utilities Holdings Limited
- Biffa plc
- CEMEX, S.A.B. de C.V.
- EEW Energy from Waste GmbH
- Enva Group Limited
- FCC Environment (UK) Limited
- Geminor AS
- Geocycle (Deutschland) GmbH
- Heidelberg Materials AG
- Holcim Ltd.
- Indaver NV
- Paprec Group S.A.S. (Paprec)
- PreZero International GmbH
- Ragn-Sells AB
- REMONDIS SE & Co. KG
- Renewi plc (Renewi)
- SUEZ S.A.
- Veolia Environnement SA
- Vicat SA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Fossil-Fuel Substitution and Cement Decarbonization
- 4.2.2 Landfill Diversion and Circular-Economy Mandates
- 4.2.3 Demand for Consistent High-Calorific Fuels
- 4.2.4 Expansion of Waste-to-Energy and CHP Capacity
- 4.2.5 AI-Enabled Sorting and Digital Fuel Traceability
- 4.2.6 Integration of Alternative Raw Materials With Fuel Pre-Processing
- 4.3 Market Restraints
- 4.3.1 Feedstock Variability and Kiln-Stability Risk
- 4.3.2 High Pre-Processing Capital and Logistics Costs
- 4.3.3 Competition for High-Calorific Residual Waste
- 4.3.4 Fragmented Permitting and Cross-Border Waste Rules
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Waste Type
- 5.1.1 Municipal Solid Waste (MSW)
- 5.1.2 Industrial Waste
- 5.1.3 Commercial Waste
- 5.1.4 Construction and Demolition Waste
- 5.1.5 Sewage Sludge
- 5.1.6 Waste Tires
- 5.1.7 Biomass and Agricultural Waste
- 5.1.8 Other Waste Types
- 5.2 By Pre-processing Technology
- 5.2.1 Mechanical Sorting and Segregation
- 5.2.2 Shredding and Size Reduction
- 5.2.3 Screening and Classification
- 5.2.4 Magnetic and Eddy-Current Separation
- 5.2.5 Air and Ballistic Separation
- 5.2.6 Optical and Sensor-Based Sorting
- 5.2.7 Mechanical-Biological Treatment and Biodrying
- 5.2.8 Drying and Moisture Conditioning
- 5.2.9 Others
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 France
- 5.3.2.3 Italy
- 5.3.2.4 Spain
- 5.3.2.5 United Kingdom
- 5.3.2.6 Poland
- 5.3.2.7 Russia
- 5.3.2.8 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 South Korea
- 5.3.3.5 Australia
- 5.3.3.6 Indonesia
- 5.3.3.7 Vietnam
- 5.3.3.8 Thailand
- 5.3.3.9 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Chile
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Egypt
- 5.3.5.4 South Africa
- 5.3.5.5 Morocco
- 5.3.5.6 Rest of Middle East and Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Andusia Holdings Limited
- 6.4.2 Beauparc Utilities Holdings Limited
- 6.4.3 Biffa plc
- 6.4.4 CEMEX, S.A.B. de C.V.
- 6.4.5 EEW Energy from Waste GmbH
- 6.4.6 Enva Group Limited
- 6.4.7 FCC Environment (UK) Limited
- 6.4.8 Geminor AS
- 6.4.9 Geocycle (Deutschland) GmbH
- 6.4.10 Heidelberg Materials AG
- 6.4.11 Holcim Ltd.
- 6.4.12 Indaver NV
- 6.4.13 Paprec Group S.A.S. (Paprec)
- 6.4.14 PreZero International GmbH
- 6.4.15 Ragn-Sells AB
- 6.4.16 REMONDIS SE & Co. KG
- 6.4.17 Renewi plc (Renewi)
- 6.4.18 SUEZ S.A.
- 6.4.19 Veolia Environnement SA
- 6.4.20 Vicat SA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 廢棄物焚化發電廠原料:市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)
 廢棄物製紡織品轉化技術市場規模、佔有率和趨勢分析報告:按廢棄物類型、技術、最終用途、地區和細分市場預測(2026-2033 年)固態回收燃料(SRF):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)廢棄物衍生燃料(RDF):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)替代燃料和原料(AFR)燃燒系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)新能源發電產業取代燃料與原料(AFRs):市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)石油和天然氣行業的替代燃料和原料(AFR):市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)美國垃圾焚化發電(WTE):市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)歐洲垃圾焚化發電:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2034年垃圾焚化發電市場預測-全球分析(依技術、廢棄物類型、能源產量、工廠產能、原料來源、應用、最終用戶、所有權結構、設施類型和地區分類)