


 |
市場調查報告書
商品編碼
2125432
中東和非洲程序化廣告:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Middle East And Africa Programmatic Advertising - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,中東和非洲的程式化廣告市場規模將從 2025 年的 200.5 億美元成長到 2026 年的 216.3 億美元,然後在 2031 年達到 316.2 億美元,2026 年至 2031 年的複合成長率 7.89%。
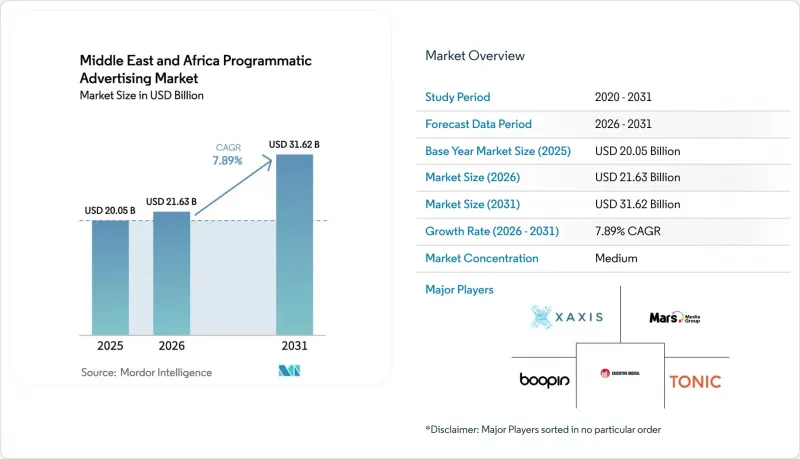
本報告按交易平台(即時競價(RTB)、私人市場擔保交易等)、廣告媒介(數位展示廣告、行動顯示器)、廣告形式(橫幅廣告、線上影片等)、公司規模(中小企業、大型企業)和行業(零售/電子商務、銀行、金融服務和保險等)進行分類。市場預測以美元計價。
中東和非洲程序化廣告市場的趨勢和洞察
海灣合作理事會國家「行動優先」消費者的激增
目前,行動優先的趨勢正在推動消費者參與度的提升,阿拉伯聯合大公國70%的消費者使用人工智慧助手,預計到2024年這一比例將增加44%。用戶平均每天在社交平臺上花費3.5小時,67%的TikTok用戶願意進行應用程式內購買。廣告主正在獲取詳細的受眾訊號,以最佳化競標策略。零售商正優先投資人工智慧,以縮短購買流程並降低購物車放棄率。預計到2028年,阿拉伯聯合大公國電子商務市場規模將超過488億迪拉姆(133億美元),這將進一步擴大對先進程式化技術堆疊的需求。像InMobi這樣的行動端需求方平台(DSP)正計劃透過IPO募集10億美元,以抓住這波成長浪潮。
中東和北非地區廣播公司對連網電視/OTT廣告資源的採用率不斷提高
阿拉伯聯合大公國有65%的居住者每天都在使用串流內容,品牌預算朝向可尋址電視廣告形式的轉移正在加速。 Noon的IPL直播展示了購物功能如何將娛樂與衝動消費結合。 ArabyAds與LG廣告解決方案的合作在擴大廣告庫存的同時,也保證了廣告可見度標準。與開放式交易平台相比,電通精心打造的CTV廣告市場在用戶注意力得分方面提升了18%,詐欺率降低了60%。 Netflix和雅虎正在拓展其程式化銷售業務,而亞馬遜廣告與Roku的合作已覆蓋全球80%的CTV家庭用戶,從而推動了中東和非洲程式化廣告市場的新需求。
本地出版商除了第三方 Cookie 之外,可選擇的替代方案有限。
30% 的行銷人員仍未做好應對第三方 Cookie 逐步淘汰的準備,導致過度依賴情境定向。本地出版商往往缺乏資金來建立第一方數據工具,從而形成了一種“兩極分化的生態系統”,全球平台獲得了不成比例的巨額預算。 ArabyAds 和 Lotame 等合作計畫旨在彌合這一差距,但其應用情況參差不齊。分散的資料隱私框架增加了合規負擔,小規模出版商難以管理。這種不平衡限制了中東和非洲程序化廣告市場的供應多樣性,並有可能減緩該地區 CPM 的成長。
細分市場分析
到2025年,即時競價(RTB)市場規模將達到88.8億美元,佔中東和非洲程式化廣告市場規模的44.30%。廣告主青睞RTB,是因為其競標效率高,且涵蓋範圍廣,能夠覆蓋分散的發布商群。然而,隨著人們對詐騙廣告的擔憂日益加劇,能夠以可預測的CPM提供優質廣告位的自動擔保交易(Automated Guaranteed Deals)正變得越來越有吸引力。自動擔保交易預計將以10.34%的複合年成長率成長,反映出市場對品牌安全性的期望不斷提高,以及供應鏈路徑最佳化協議的整合。 The Trade Desk 25%的營收成長以及對Sincera的收購表明,市場正在轉向能夠揭示可信路徑並減少隱性費用的分析技術。 PubMatic的報告顯示,目前55%的廣告展示都經過了最佳化路徑,凸顯了市場對透明度的重視。
「私人市場保障」為汽車、銀行、金融和保險 (BFSI) 以及奢侈品牌提供精心策劃、高曝光度的廣告內容。對於尋求成本控制的效果行銷人員而言,無預留、固定費率的合約仍然可行。產業重組正在重塑平台選擇,例如 Outbrain 以 10 億美元收購 T-ados,此舉擴展了原生廣告和影片廣告組合。因此,在確定中東和非洲程序化廣告市場的最佳交易結構時,廣告商正在仔細權衡規模和獨家性之間的平衡。
數位展示廣告保持了 54.30% 的市場佔有率,這主要得益於跨螢幕重複使用創新的全通路宣傳活動。行動顯示器廣告預計將實現 8.88% 的複合年成長率,這主要得益於智慧型手機的普及以及「綠色媒體」的創新,後者在減少 39% 碳排放的同時,還能將點擊率提高 10%。營運商的資料整合正在提升情境預測的準確性,尤其是在對 Cookie 依賴性較低的環境中。隨著中東和非洲程序化廣告市場的日趨成熟,品牌正在調整其行動預算,以契合人工智慧主導的商務流程,在用戶購買意願最強烈的應用程式內觸達他們。桌面展示廣告對於 B2B 和長篇內容仍然至關重要,但隨著混合辦公模式的興起,用戶的時間逐漸轉移到行動平台,其市場佔有率持續下降。
媒體購買者對跨裝置頻率控制和整合式衡量的需求日益成長。 Magnite 的連網電視 (CTV) 營收成長 23%,顯示市場對融合 CTV 和行動影片的單一平台執行方案的需求不斷成長。此外,不斷上漲的媒體成本促使行銷人員重新評估其供應管道,從而提升了能夠以永續的CPM 提供可見廣告位的供應方平台 (SSP) 的重要性。因此,在中東和非洲的程序化廣告市場,展示廣告預算的分配變得更加規範。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 海灣合作理事會國家「行動優先」消費者的激增
- 中東和北非地區廣播公司擴大CTV/OTT廣告投放範圍。
- 跨境電子商務的激增正在推動阿拉伯聯合大公國和沙烏地阿拉伯對第一方資料的使用。
- 非洲電信業者主導的身份舉措(例如,MTN、Vodacom)
- 在中東和非洲 (MEA) 地區,針對國際足總和世博會等活動,部署程式化數位戶外廣告。
- 人工智慧在廣告營運中的整合和自動化
- 市場限制因素
- 本地出版商除了第三方 Cookie 之外,可選擇的替代方案有限。
- 非洲主要城市以外地區4G/5G覆蓋不均
- 品牌安全工具的低普及率增加了詐欺風險。
- 中東和非洲各國資料隱私法規存在差異
- 監理展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過交易平台
- 即時競價(RTB)
- 私人交易平台(有保障)
- 自動擔保類型
- 無限制固定利率
- 透過廣告媒介
- 數字顯示
- 行動顯示器
- 廣告格式
- 全橫幅
- 線上影片
- 社群媒體
- CTV/OTT
- 音訊(串流媒體和播客)
- 數位戶外廣告 (DOOH)
- 其他
- 按公司規模
- 中小企業
- 大公司
- 按行業
- 零售與電子商務
- BFSI
- 車
- 媒體與娛樂
- 醫療保健和製藥
- 旅遊與飯店
- 通訊/IT
- 其他
第6章 競爭情勢
- Strategic Developments
- Vendor Positioning Analysis
- 公司簡介
- Google LLC
- Amazon Ads(Amazon Inc.)
- Xaxis(GroupM)
- InMobi Pte Ltd
- The Trade Desk, Inc.
- Magnite, Inc.
- PubMatic, Inc.
- Adform A/S
- Criteo SA
- Mars Media Group
- Tonic International
- Hsoub
- AdFalcon
- Gamned!
- Adsterra
- MMP World Wide
- Dentsu Aegis Network MEA
- Omnicom Media Group MEA
- AdFalcon(Noor Telecom)
- Digital Turbine Inc.
- Executive Digital
- Boopin
第7章 市場機會與未來展望
According to Mordor Intelligence, the Middle East and Africa programmatic advertising market size is expected to grow from USD 20.05 billion in 2025 to USD 21.63 billion in 2026 and is forecast to reach USD 31.62 billion by 2031 at 7.89% CAGR over 2026-2031.
This report is Segmented by Trading Platform (Real-Time Bidding (RTB), Private Marketplace Guaranteed, and More), Advertising Media (Digital Display, Mobile Display), Ad Format (Display Banner, Online Video, and More), Enterprise Size (SMBs, Large Enterprises), Industry Vertical (Retail and E-Commerce, BFSI, and More). The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Programmatic Advertising Market Trends and Insights
Explosion of Mobile-First Consumers in GCC States
Mobile-first usage now defines consumer engagement, with 70% of UAE shoppers leveraging AI assistants, a 44% jump since 2024. Users spend 3.5 hours daily on social platforms, and 67% of TikTok viewers feel motivated to make in-app purchases. Advertisers gain granular audience signals that refine bid strategies across the Middle East and Africa programmatic advertising market. Retailers are prioritizing AI budgets to shorten the path to purchase and reduce cart abandonment. The UAE e-commerce market is projected to surpass AED 48.8 billion (USD 13.3 billion) by 2028, reinforcing the scale needed for advanced programmatic stacks. Mobile-centric DSPs such as InMobi are positioning for a USD 1 billion IPO to capitalize on this uptick.
Growing Adoption of CTV/OTT Advertising Inventory by MENA Broadcasters
Sixty-five percent of UAE residents stream content daily, accelerating migration of brand budgets toward addressable TV formats. Noon's IPL streams show how shoppable overlays fuse entertainment with impulse purchases. ArabyAds' alliance with LG Ad Solutions broadens supply while maintaining viewability standards. Dentsu's curated CTV marketplace posted an 18% lift in attention scores and reduced fraud by 60% compared with open exchanges. Netflix and Yahoo expanded programmatic sales, and Amazon Ads struck a Roku pact reaching 80% of global CTV homes, pulling incremental demand into the Middle East and Africa programmatic advertising market.
Limited Third-Party Cookie Alternatives on Local Publishers
Thirty percent of marketers remain ill-prepared for cookie deprecation, leading to over-reliance on contextual targeting. Local publishers often lack the capital to build first-party data tools, creating a two-speed ecosystem where global platforms win disproportionate budgets. Partnerships such as ArabyAds-Lotame aim to close the gap, yet uptake is uneven. Fragmented data-privacy frameworks add compliance overhead that smaller publishers struggle to manage. The imbalance restricts supply diversity within the Middle East and Africa programmatic advertising market and could dampen CPM growth for regional inventory.
Other drivers and restraints analyzed in the detailed report include:
- Cross-Border E-commerce Surge Boosting First-Party Data Use in UAE and KSA
- Telco-Led Identity Graph Initiatives in Africa
- Patchy 4G/5G Coverage Outside Tier-1 African Cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Real-Time Bidding contributed USD 8.88 billion, equating to 44.30% of the Middle East and Africa programmatic advertising market size in 2025. Advertisers favor RTB for auction efficiency and reach across fragmented publisher pools. Yet fraud concerns have heightened the appeal of Automated Guaranteed deals that lock premium slots at predictable CPMs. Automated Guaranteed is set for 10.34% CAGR, reflecting rising brand-safety expectations and the integration of supply-path optimization protocols. The Trade Desk's 25% revenue rise and Sincera acquisition demonstrate the pivot toward analytics that surface trustworthy paths and reduce hidden fees. PubMatic reports 55% of impressions now travel through optimized routes, underscoring a marketwide push for transparency.
Private Marketplace Guaranteed offers curated high-viewability contexts for auto, BFSI, and luxury brands. Unreserved Fixed-Rate deals remain relevant for performance marketers chasing cost control. Consolidation reshapes platform choices, as Outbrain's USD 1 billion Teads takeover broadens native and video bundles. Advertisers therefore weigh scale versus exclusivity in determining optimal trading mixes across the Middle East and Africa programmatic advertising market.
Digital Display retained 54.30% share led by omnichannel campaigns that repurpose creative across screens. Mobile Display is forecast to post 8.88% CAGR, propelled by smartphone adoption and green media innovations that cut emissions by 39% while boosting click-throughs by 10%. Telco data integrations deepen contextual accuracy, particularly in cookie-light environments. As the Middle East and Africa programmatic advertising market matures, brands align mobile budgets with AI-driven commerce journeys, meeting consumers in-app where purchase intent peaks. Desktop display remains vital for B2B and long-form content, yet its share continues to edge down as hybrid work pushes more user time into mobile ecosystems.
Media buyers increasingly demand cross-device frequency capping and unified measurement. Magnite's 23% CTV revenue rise signals demand for single-platform execution that blends CTV and mobile video. Media cost inflation has also nudged marketers toward supply-path pruning, elevating SSPs that guarantee viewable inventory at sustainable CPMs. The result is a more disciplined allocation of display budgets across the Middle East and Africa programmatic advertising market.
Complete Report Scope:
- By Trading Platform
- Real-Time Bidding (RTB)
- Private Marketplace Guaranteed
- Automated Guaranteed
- Unreserved Fixed-rate
- By Advertising Media
- Digital Display
- Mobile Display
- By Ad Format
- Display Banner
- Online Video
- Social Media
- CTV / OTT
- Audio (Streaming and Podcast)
- Digital-Out-of-Home (DOOH)
- Others
- By Enterprise Size
- Small and Medium Businesses (SMBs)
- Large Enterprises
- By Industry Vertical
- Retail and E-commerce
- BFSI
- Automotive
- Media and Entertainment
- Healthcare and Pharma
- Travel and Hospitality
- Telecom and IT
- Others
List of Companies Covered in this Report:
- Google LLC
- Amazon Ads (Amazon Inc.)
- Xaxis (GroupM)
- InMobi Pte Ltd
- The Trade Desk, Inc.
- Magnite, Inc.
- PubMatic, Inc.
- Adform A/S
- Criteo SA
- Mars Media Group
- Tonic International
- Hsoub
- AdFalcon
- Gamned!
- Adsterra
- MMP World Wide
- Dentsu Aegis Network MEA
- Omnicom Media Group MEA
- AdFalcon (Noor Telecom)
- Digital Turbine Inc.
- Executive Digital
- Boopin
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosion of Mobile-First Consumers in GCC States
- 4.2.2 Growing Adoption of CTV/OTT Advertising Inventory by MENA Broadcasters
- 4.2.3 Cross-border E-commerce Surge Boosting First-Party Data Use in UAE and KSA
- 4.2.4 Telco-led Identity Graph Initiatives in Africa (e.g., MTN, Vodacom)
- 4.2.5 Programmatic DOOH Roll-outs Around FIFA and Expo Events in MEA
- 4.2.6 AI Integration and Automation in Advertising Operations
- 4.3 Market Restraints
- 4.3.1 Limited Third-Party Cookie Alternatives on Local Publishers
- 4.3.2 Patchy 4G/5G Coverage Outside Tier-1 African Cities
- 4.3.3 Low Brand-safety Tool Penetration Elevating Fraud Risk
- 4.3.4 Fragmented Data-privacy Regulations Across MEA States
- 4.4 Regulatory Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Trading Platform
- 5.1.1 Real-Time Bidding (RTB)
- 5.1.2 Private Marketplace Guaranteed
- 5.1.3 Automated Guaranteed
- 5.1.4 Unreserved Fixed-rate
- 5.2 By Advertising Media
- 5.2.1 Digital Display
- 5.2.2 Mobile Display
- 5.3 By Ad Format
- 5.3.1 Display Banner
- 5.3.2 Online Video
- 5.3.3 Social Media
- 5.3.4 CTV / OTT
- 5.3.5 Audio (Streaming and Podcast)
- 5.3.6 Digital-Out-of-Home (DOOH)
- 5.3.7 Others
- 5.4 By Enterprise Size
- 5.4.1 Small and Medium Businesses (SMBs)
- 5.4.2 Large Enterprises
- 5.5 By Industry Vertical
- 5.5.1 Retail and E-commerce
- 5.5.2 BFSI
- 5.5.3 Automotive
- 5.5.4 Media and Entertainment
- 5.5.5 Healthcare and Pharma
- 5.5.6 Travel and Hospitality
- 5.5.7 Telecom and IT
- 5.5.8 Others
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Google LLC
- 6.3.2 Amazon Ads (Amazon Inc.)
- 6.3.3 Xaxis (GroupM)
- 6.3.4 InMobi Pte Ltd
- 6.3.5 The Trade Desk, Inc.
- 6.3.6 Magnite, Inc.
- 6.3.7 PubMatic, Inc.
- 6.3.8 Adform A/S
- 6.3.9 Criteo SA
- 6.3.10 Mars Media Group
- 6.3.11 Tonic International
- 6.3.12 Hsoub
- 6.3.13 AdFalcon
- 6.3.14 Gamned!
- 6.3.15 Adsterra
- 6.3.16 MMP World Wide
- 6.3.17 Dentsu Aegis Network MEA
- 6.3.18 Omnicom Media Group MEA
- 6.3.19 AdFalcon (Noor Telecom)
- 6.3.20 Digital Turbine Inc.
- 6.3.21 Executive Digital
- 6.3.22 Boopin
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 亞太地區程序化廣告:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美程序化廣告:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲程序化廣告:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)程序化廣告:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)OTT程序化廣告:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)動態創新最佳化軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 程序化廣告市場:2026-2032年全球市場預測(依廣告格式、設備類型、平台類型、技術類型及產業分類)
 程序化展示廣告市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、設備、流程、部署模式及最終用戶分類
 2026年全球付費會員計畫平台市場報告2026年全球動態創新最佳化(DCO)市場報告