


 |
市場調查報告書
商品編碼
2125329
歐洲程序化廣告:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Programmatic Advertising - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
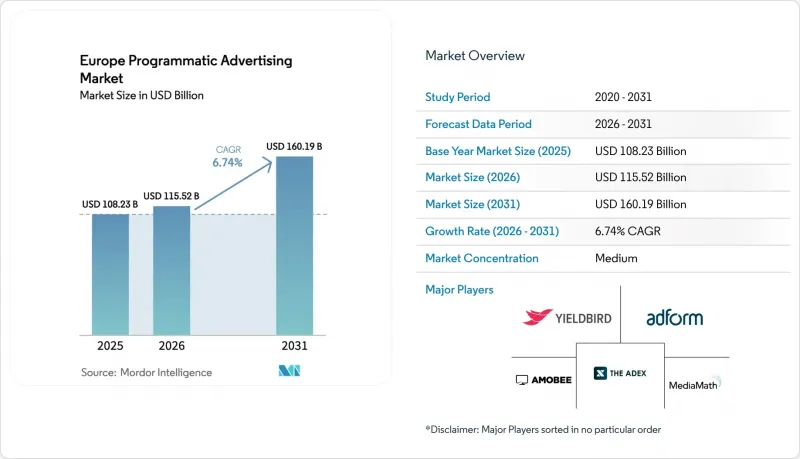
根據 Mordor Intelligence 估計,歐洲程式化廣告市場規模從 2025 年的 1,082.3 億美元成長到 2026 年的 1,155.2 億美元,預計到 2031 年將達到 1,601.9 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 6.74%。
本報告按交易平台(即時競價、私人市場等)、廣告媒體(展示橫幅廣告、線上影片、連網電視等)、公司規模(中小企業和大型企業)、產業(零售和電子商務、消費品、汽車、金融服務等)以及地區進行細分。市場預測以美元計價。
歐洲程序化廣告市場的趨勢與洞察
數位媒體消費和線上影片的激增
2024年,歐洲觀眾超過一半的數位媒體興趣都集中在視訊格式。音訊和短影片的觀看時長與廣告支出之間的不平衡表明,其廣告庫存仍有進一步成長的潛力。隨著廣播公司開始透過供應端平台提供優質串流服務,連網電視(CTV)的廣告支出達到36億歐元,較去年同期成長23.5%。先進的衡量框架將CTV的曝光量與檢驗的結果聯繫起來,鼓勵品牌廣告商和效果廣告商將預算轉移到能夠兼顧覆蓋範圍和精準度的歐洲程序化廣告宣傳中。跨螢幕定序工具進一步提升了影片的有效性,提高了訊息記憶度並減少了無效曝光。隨著光纖和5G在歐洲的普及,高解析度廣告傳輸的頻寬限制已被消除,從而能夠呈現更豐富的創新和更流暢的用戶體驗。
推廣符合 GDPR 規範的數據以進行受眾定向
自 2018 年 GDPR 生效這一里程碑年份以來,出版商和零售商已對第一方資料基礎設施進行了大量投資。目前,他們正利用電子郵件、會員忠誠度和交易資料集,以及經用戶許可的地址、IP 位址和 SDK 訊號,建立不依賴第三方 Cookie 的強大受眾圖譜。 IAB Europe 的透明度和使用者授權框架 (TCF) 已註冊超過 1000 家認證供應商,73% 的領先出版商已實施 ads.txt 和 sellers.json,以確保銷售管道的合法性。這些措施提高了信任度,減少了無效廣告供應,並使歐洲程序化廣告市場的參與企業企業能夠基於合法數據觸發即時創新最佳化。最終,他們獲得了更深層、更注重隱私保護的種子資料池,用於相似受眾建模和上下文疊加,從而拓展了網路、應用程式和新興元宇宙的變現潛力。
嚴格的隱私權法限制第三方 Cookie
《一般資料保護規範》(GDPR)、《電子隱私指令》以及一系列國家法規正在限制識別碼的使用並強制要求用戶明確同意,這推高了廣告技術供應商的合規成本。法國監管機構CNIL已將典型的程序化交易鏈中的620多個獨立系統列入名單,每個系統現在都必須證明其資料使用範圍有限且資料最小化。雖然大型出版商正在部署同意管理平台,但小規模網站卻難以應對法律負擔,這減緩了歐洲程式化廣告市場的庫存成長。同時,瀏覽器層面的介入措施正在縮短cookie的有效期,迫使廣告商轉向基於情境、基於使用者群組和「無塵室」的解決方案,而這些解決方案的實施成本通常很高。
細分市場分析
到2025年,即時競價(RTB)將佔據歐洲程式化廣告市場42.98%的佔有率。廣告主看重其競標效率、覆蓋率廣度和預算分配柔軟性。然而,隨著媒體品質日益受到重視,出版商擴大利用私有市場,將受眾群體和情境訊號以協商最低價格(底價)打包,並與RTB結合。程序化擔保交易以8.28%的複合年成長率成長,它允許在自動化流程中簽訂類似於訂單(廣告投放契約)的直接契約,為雙方提供可預測的投放和效果。隨著廣播和零售網路將廣告資源包系統化,以適應關鍵事件和季節性高峰,歐洲程序化廣告市場擔保交易的規模預計將穩定成長。
私有市場扮演策略橋樑的角色,提供「優先瀏覽」機會,而無需保證投放量。這種模式對品牌安全要求嚴格的行業(例如金融、醫療保健和政府機構)極具吸引力,因為在這些行業中,情境和創新契合度比規模更為重要。 DSP 和 SSP 符合 TCF v2.2 標準,可減少法律摩擦,簡化交易流程,並擴大廣告主的參與度。在預測期內,結合即時競價 (RTB) 的覆蓋範圍和有保障交易的確定性的混合購買框架將在歐洲程序化廣告市場中普及,從而在成本效益和庫存品質之間取得平衡。
到2025年,線上影片和連網電視(CTV)將佔歐洲程式化廣告市場的37.12%。精準的家庭導向、高級受眾細分和高影響力創新正在推動高價位廣告的出現,而發布商則利用動態廣告插入來最大化收入。展示橫幅廣告仍然是重要的效果廣告管道,尤其是在重新導向和全通路廣告投放方面。然而,成長最快的領域是數位戶外廣告(DOOH),其複合年成長率高達8.16%,這得益於DOOH網路整合了天氣和交通流量等即時數據觸發機制,以實現螢幕個人化。
行動應用程式內廣告位由上下文資料層提供支持,該資料層可補償因 Cookie 功能下降導致的訊號損失。應用 SDK 遙測技術能夠理解用戶意圖,從而支持可玩廣告和激勵影片等以轉換為導向的廣告形式。音訊廣告佔媒體消費時長的 21%,但僅佔廣告支出的 4.5%。然而,音頻廣告覆蓋範圍更廣,廣告環境更不易引起用戶反感。隨著跨螢幕衡量標準的日益標準化,不同廣告形式的分配將更加嚴格,但由於影片具有更優異的互動指標,預計影片廣告仍將在歐洲程式化廣告市場保持強勁的佔有率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 數位媒體的使用和線上影片的激增
- 推廣符合 GDPR 規範的數據以進行受眾定向
- 聯網電視(CTV)程序化廣告空間的擴展
- 行動應用程式內廣告的普及速度正在加快。
- 拓展零售媒體網路中的程式化廣告服務
- 歐盟數位市場立法正在推動開放網路之外的其他選擇。
- 市場限制因素
- 嚴格的隱私權法限制第三方 Cookie(GDPR、ePrivacy)
- 持續存在的廣告詐騙以及對品牌安全的擔憂。
- 供應鏈的複雜性和透明度問題
- 廣告科技公司越來越關注其供應鏈中的碳足跡。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資分析
第5章 市場規模與成長預測
- 透過交易平台
- 即時競價(公開競標)
- 私有市場(PMP)
- 程序化擔保
- 優惠套餐(無限固定利率)
- 透過廣告媒介
- 全橫幅
- 線上影片和連網電視
- 行動應用程式廣告
- 聲音的
- 數位戶外廣告 (DOOH)
- 按公司規模
- 中小企業
- 大公司
- 按行業分類
- 零售與電子商務
- 消費品(CPG)
- 車
- 金融服務
- 媒體與娛樂
- 旅遊與飯店
- 醫療和藥品
- 科技與通訊
- 政府/公共部門
- 按地區
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 波蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Google Ireland Limited
- Meta Platforms Ireland Limited
- The Trade Desk, Inc.
- Xandr(Microsoft Advertising)
- Criteo SA
- Adform A/S
- MediaMath, Inc.
- IPONWEB Limited
- Yieldbird Sp. z oo
- The ADEX GmbH
- PubMatic, Inc.
- Amobee, Inc.
- Eskimi DSP
- Magnite, Inc.
- Index Exchange, Inc.
- OpenX Technologies, Inc.
- Smart Adserver SAS
- Smaato, Inc.
- Tremor International Ltd.
- LiveRamp Holdings, Inc.
- Sizmek Technologies, Inc.
- InMobi Pte Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, Europe programmatic advertising market size in 2026 is estimated at USD 115.52 billion, growing from 2025 value of USD 108.23 billion with 2031 projections showing USD 160.19 billion, growing at 6.74% CAGR over 2026-2031.
This report is Segmented by Trading Platform (Real-Time Bidding, Private Marketplace, and More), Advertising Media (Display Banner, Online Video and CTV, and More), Enterprise Size (SMEs and Large Enterprises), Industry Vertical (Retail and E-Commerce, CPG, Automotive, Financial Services, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Europe Programmatic Advertising Market Trends and Insights
Surge in Digital Media Consumption and Online Video
European viewers allocated more than half of their digital attention to video formats in 2024, and the imbalance between time spent and ad spend in audio and short-form video signals incremental inventory growth potential. CTV spend climbed to EUR 3.6 billion, a 23.5% year-over-year jump as broadcasters unlocked premium streams through supply-side platforms. Advanced measurement frameworks now link CTV impressions to verified outcomes, encouraging brand and performance advertisers alike to shift budgets toward Europe Programmatic Advertising market campaigns that blend reach with precision. Cross-screen sequencing tools further amplify video's effectiveness, increasing message recall and reducing frequency waste. With near-ubiquitous fiber and 5G rollouts across the continent, bandwidth no longer limits high-definition ad delivery, enabling richer creative and seamless user experiences.
Proliferation of GDPR-Compliant Data for Audience Targeting
Publishers and retailers invested heavily in first-party data infrastructure after the GDPR milestone year of 2018. Email, loyalty, and transaction datasets are now complemented by consented address, IP, and SDK signals, giving rise to robust audience graphs that operate without third-party cookies. IAB Europe's Transparency and Consent Framework (TCF) lists more than 1,000 certified vendors, and 73% of major publishers have implemented ads.txt and sellers.json to ensure authorized selling paths. These measures elevate trust, cut invalid supply, and allow Europe Programmatic Advertising market participants to deploy real-time creative optimization based on lawful data triggers. The net result is a deeper, privacy-safe seed pool for look-alike modeling and contextual overlays, which expands monetization possibilities across web, app, and emerging metaverse surfaces.
Stringent Privacy Laws Limiting Third-Party Cookies
The GDPR, ePrivacy Directive, and a patchwork of national rules restrict identifiers and mandate explicit consent, elevating compliance costs for ad-tech vendors. French watchdog CNIL catalogued more than 620 discrete systems in a typical programmatic transaction chain, each of which must now substantiate purpose limitation and data minimization claims. Large publishers deploy consent-management platforms, but smaller sites struggle with legal overhead, tempering inventory growth in the Europe Programmatic Advertising market. Parallelly, browser-level interventions curtail cookie lifespans, pushing advertisers toward contextual, cohort-based, and clean-room solutions that often carry higher implementation expenses.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Connected TV Programmatic Inventory
- Expansion of Retail-Media Networks' Programmatic Offerings
- Persistent Ad-Fraud and Brand-Safety Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
RTB contributed 42.98% of Europe Programmatic Advertising market share in 2025. Advertisers favor its auction efficiency, broad reach, and budget pacing flexibility. However, heightened emphasis on media quality drives publishers to augment RTB with private marketplaces that bundle audience segments and contextual signals at negotiated floors. Programmatic guaranteed, growing at an 8.28% CAGR, enables direct, IO-like commitments within automated pipes, giving both parties predictable delivery and performance. The Europe Programmatic Advertising market size for guaranteed deals is projected to climb steadily as broadcast and retail networks codify inventory packages around tent-pole events and seasonal peaks.
Private marketplaces serve as a strategic bridge, offering "first-look" access without volume guarantees. This format appeals to verticals with strict brand-safety requirements, finance, health, and government, where context and creative adjacency matter more than scale. DSP and SSP compliance with TCF v2.2 reduces legal friction, streamlines deal activation, and widens advertiser participation. Over the forecast horizon, hybrid buying frameworks that combine RTB's reach with guaranteed deals' certainty will become commonplace across the Europe Programmatic Advertising market, balancing cost efficiency with inventory quality.
Online video and CTV accounted for 37.12% of Europe Programmatic Advertising market size in 2025. Household addressability, advanced audience segments, and high-impact creative drive premium pricing, and publishers leverage dynamic ad-insertion to maximize yield. Display banners remain an essential performance channel, particularly for retargeting and full-funnel sequencing. Yet the fastest-growing slice is digital out-of-home, expanding at an 8.16% CAGR as DOOH networks integrate real-time data triggers such as weather and transit flows to personalize screens.
Mobile in-app inventory is buoyed by contextual data layers that offset signal loss from cookie depreciation. App-SDK telemetry maps intent, enabling conversion-oriented formats such as playable ads and rewarded video. Audio, despite representing only 4.5% of ad spend relative to 21% of media time, offers incremental reach and low-clutter environments. As measurement unifies across screens, cross-format allocations will tighten, but video's share should remain resilient given its superior engagement metrics within the Europe Programmatic Advertising market.
Complete Report Scope:
- By Trading Platform
- Real-Time Bidding (Open Auction)
- Private Marketplace (PMP)
- Programmatic Guaranteed
- Preferred Deal (Unreserved Fixed-Rate)
- By Advertising Media
- Display Banner
- Online Video and CTV
- Mobile In-App
- Audio
- Digital Out-of-Home (DOOH)
- By Enterprise Size
- Small and Medium-Sized Enterprises (SMEs)
- Large Enterprises
- By Industry Vertical
- Retail and E-Commerce
- Consumer Packaged Goods (CPG)
- Automotive
- Financial Services
- Media and Entertainment
- Travel and Hospitality
- Healthcare and Pharmaceuticals
- Technology and Telecommunications
- Government and Public Sector
- By Geography
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Google Ireland Limited
- Meta Platforms Ireland Limited
- The Trade Desk, Inc.
- Xandr (Microsoft Advertising)
- Criteo S.A.
- Adform A/S
- MediaMath, Inc.
- IPONWEB Limited
- Yieldbird Sp. z o.o.
- The ADEX GmbH
- PubMatic, Inc.
- Amobee, Inc.
- Eskimi DSP
- Magnite, Inc.
- Index Exchange, Inc.
- OpenX Technologies, Inc.
- Smart Adserver SAS
- Smaato, Inc.
- Tremor International Ltd.
- LiveRamp Holdings, Inc.
- Sizmek Technologies, Inc.
- InMobi Pte Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in digital media consumption and online video
- 4.2.2 Proliferation of GDPR-compliant data for audience targeting
- 4.2.3 Growth of Connected TV (CTV) programmatic inventory
- 4.2.4 Accelerating adoption of mobile in-app advertising
- 4.2.5 Expansion of retail-media networks' programmatic offerings
- 4.2.6 EU Digital Markets Act spurring open-web alternatives
- 4.3 Market Restraints
- 4.3.1 Stringent privacy laws (GDPR, ePrivacy) limiting third-party cookies
- 4.3.2 Persistent ad-fraud and brand-safety concerns
- 4.3.3 Supply-path complexity and transparency issues
- 4.3.4 Emerging carbon-footprint scrutiny of ad-tech supply chains
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Advertisers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Trading Platform
- 5.1.1 Real-Time Bidding (Open Auction)
- 5.1.2 Private Marketplace (PMP)
- 5.1.3 Programmatic Guaranteed
- 5.1.4 Preferred Deal (Unreserved Fixed-Rate)
- 5.2 By Advertising Media
- 5.2.1 Display Banner
- 5.2.2 Online Video and CTV
- 5.2.3 Mobile In-App
- 5.2.4 Audio
- 5.2.5 Digital Out-of-Home (DOOH)
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium-Sized Enterprises (SMEs)
- 5.3.2 Large Enterprises
- 5.4 By Industry Vertical
- 5.4.1 Retail and E-Commerce
- 5.4.2 Consumer Packaged Goods (CPG)
- 5.4.3 Automotive
- 5.4.4 Financial Services
- 5.4.5 Media and Entertainment
- 5.4.6 Travel and Hospitality
- 5.4.7 Healthcare and Pharmaceuticals
- 5.4.8 Technology and Telecommunications
- 5.4.9 Government and Public Sector
- 5.5 By Geography
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Poland
- 5.5.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Google Ireland Limited
- 6.4.2 Meta Platforms Ireland Limited
- 6.4.3 The Trade Desk, Inc.
- 6.4.4 Xandr (Microsoft Advertising)
- 6.4.5 Criteo S.A.
- 6.4.6 Adform A/S
- 6.4.7 MediaMath, Inc.
- 6.4.8 IPONWEB Limited
- 6.4.9 Yieldbird Sp. z o.o.
- 6.4.10 The ADEX GmbH
- 6.4.11 PubMatic, Inc.
- 6.4.12 Amobee, Inc.
- 6.4.13 Eskimi DSP
- 6.4.14 Magnite, Inc.
- 6.4.15 Index Exchange, Inc.
- 6.4.16 OpenX Technologies, Inc.
- 6.4.17 Smart Adserver SAS
- 6.4.18 Smaato, Inc.
- 6.4.19 Tremor International Ltd.
- 6.4.20 LiveRamp Holdings, Inc.
- 6.4.21 Sizmek Technologies, Inc.
- 6.4.22 InMobi Pte Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 中東和非洲程序化廣告:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)亞太地區程序化廣告:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美程序化廣告:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)程序化廣告:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)OTT程序化廣告:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)動態創新最佳化軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 程序化廣告市場:2026-2032年全球市場預測(依廣告格式、設備類型、平台類型、技術類型及產業分類)
 程序化展示廣告市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、設備、流程、部署模式及最終用戶分類
 2026年全球付費會員計畫平台市場報告2026年全球動態創新最佳化(DCO)市場報告