


 |
市場調查報告書
商品編碼
2120816
馬來西亞油氣:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Malaysia Oil And Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,馬來西亞石油和天然氣市場在 2026 年的價值為 96.6 億美元,高於 2025 年的 91.6 億美元,預計到 2031 年將達到 125.6 億美元。
預計 2026 年至 2031 年的複合年成長率為 5.42%。
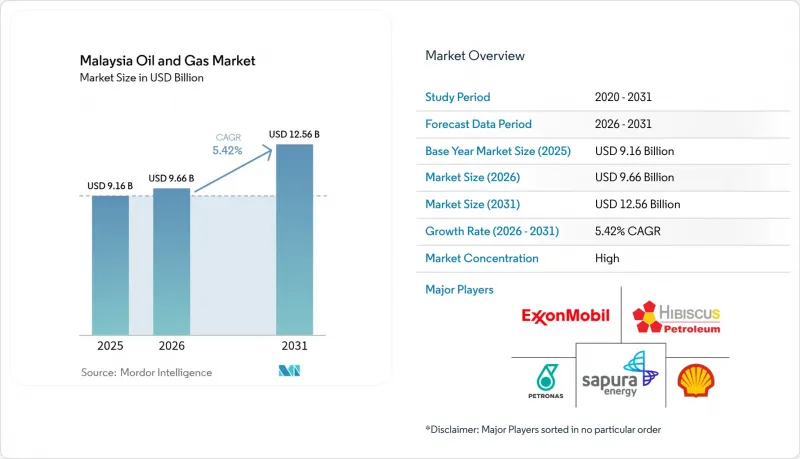
本報告按行業(上游、中游、下游)、地區(陸上和海上)和服務(建設、維護/檢修、退役)進行細分。市場規模和預測均以美元計價。
馬來西亞油氣市場趨勢與洞察
精煉石油產品需求激增
東南亞地區燃料消費的復甦和新的出行趨勢正在推動煉油廠的運轉率上升。彭格朗綜合煉油廠日加工能力達30萬桶,已於2024年11月投入商業運營,協助馬來西亞半島向印尼、越南和菲律賓等供應供不應求的市場提供原油。馬來西亞國家石油公司(Petronas)旗下的化學公司正在建造一座年處理能力3.3萬噸的化學品回收工廠,計劃於2026年運作,將循環經濟理念融入下游產業鏈。這些項目鞏固了上游生產商的原油採購管道,並使馬來西亞不僅成為石油出口國,更成為加工中心。
沙撈越和沙巴未開發的深海蘊藏量
蘭卡斯卡(Lankaska)和拉央拉叢集(Layang-Layang)區塊預計蘊藏大規模的天然氣和冷凝油蘊藏量,需要高性能鑽井鑽機、海底回接系統和浮體式天然氣(LNG)解決方案。馬來西亞2025年競標區塊招標指定了五個探勘區域和三個開發風險分擔叢集,以促進投資。康菲石油公司和殼牌公司正將投資組合資金轉向以天然氣為中心的開發項目,以確保LNG原料的穩定供應。穩定的產品分成合約(PSC)框架以及馬來西亞國家石油公司(Petronas)作為資源管理機構的作用,正在縮短從發現到首次天然氣生產的前置作業時間,從而增強馬來西亞油氣市場的長期競爭力。
原油價格劇烈波動
2024年至2025年間,布蘭特原油價格在每桶70美元至90美元之間波動,擾亂了現金流計劃,推遲了一些最終投資決策,並增加了借貸成本。獲利能力較弱的油田的經濟效益尤其容易受到價格下跌的影響,特別是當採用需要高成本氣舉或化學注入等增產技術時。馬來西亞石油、天然氣和能源服務理事會提出的財政援助請求凸顯了其面臨的市場波動風險。雖然避險和成本最佳化能夠帶來一些好處,但持續的波動可能會減緩深海油田開發和退役工作的進展。
細分市場分析
2025年,上游產業佔馬來西亞油氣市場規模的74.85%,這主要得益於活躍的產量分成合約(PSC)活動和馬來西亞國家石油公司(Petronas)的專案儲備。傑隆(Jerung)、卡薩瓦里(Kasawari)和古穆蘇特-卡卡普(Gumusut-Kakap)油田的重建項目在抵消自然減產的同時,維持了峰值產量水平。上游產業在馬來西亞油氣市場佔據主導地位,得益於其豐富的冷凝油氣蘊藏量地質條件以及有利於油田商業化的稅收政策。
隨著國際業者獲得深水井和利潤微薄的油氣田改造計畫的特許權,上游領域的投資動能預計將持續到2031年。同時,隨著沙巴-砂拉越天然氣管道於2027年退役,中游業者將面臨重新規劃運輸路線的挑戰,並需要尋找從東馬運輸天然氣的替代方式。下游業者將受益於新的原料,因為上游瓶頸消除後,冷凝油產量增加,這些凝析油將供應給邊佳蘭重整裝置。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 石油煉製產品需求激增
- 未開發的深海蘊藏量(沙撈越和沙巴)
- 基於獎勵和財務條件對生產分成合約進行審查
- 亞洲對液化天然氣需求的成長正在推動馬來西亞的出口。
- CCUS和藍氫計畫管網
- 下游石化產業的整合勢頭
- 市場限制因素
- 原油價格劇烈波動
- 投資趨勢向全球能源轉型轉變
- ESG相關資金籌措限制
- 海上基礎設施老化和營運成本(OPEX)上升
- 供應鏈分析
- 監理情勢
- 技術展望
- 原油產量和消費量預測
- 天然氣生產與消費預測
- 管道容量分析
- 非傳統資源(緻密油、油砂、深海油田)資本投資預測
- 波特五力模型
- PESTLE分析
第5章 市場規模與成長預測
- 按行業
- 上游部門
- 中游
- 下游產業
- 按位置
- 陸上
- 離岸
- 按服務
- 建造
- 維護和檢修
- 退休
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Petroliam Nasional Berhad(Petronas)
- Shell plc
- Exxon Mobil Corp.
- Chevron Corp.
- BP plc
- Hibiscus Petroleum Bhd
- Sapura Energy Bhd
- Dialog Group Bhd
- MISC Berhad
- Yinson Holdings Bhd
- PTTEP(Malaysia assets)
- Repsol Exploration(Malaysia)SA
- Lundin Energy Malaysia
- Murphy Oil Corporation(Malaysia)
- Serba Dinamik Holdings
- Velesto Energy Bhd
- Malaysia Marine & Heavy Engineering
- Altus Oil & Gas Malaysia Sdn Bhd
- Petro-Excel Sdn Bhd
- Petro Teguh(M)Sdn Bhd
第7章 市場機會與未來展望
According to Mordor Intelligence, Malaysia oil and gas market size in 2026 is estimated at USD 9.66 billion, growing from 2025 value of USD 9.16 billion with 2031 projections showing USD 12.56 billion, growing at 5.42% CAGR over 2026-2031.
This report is Segmented by Sector (Upstream, Midstream, and Downstream), Location (Onshore and Offshore), and Service (Construction, Maintenance and Turn-Around, and Decommissioning). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Malaysia Oil And Gas Market Trends and Insights
Surging Demand for Refined Petroleum Products
Regional fuel consumption recovery and new mobility trends stimulate refinery utilization rates across Southeast Asia. The Pengerang Integrated Complex entered commercial service in November 2024 with 300,000 barrels-per-day capacity, underpinning Peninsular Malaysia's aspiration to supply deficit markets in Indonesia, Vietnam, and the Philippines. Petronas Chemicals is constructing a 33,000-tonnes-per-annum chemical recycling plant due in 2026, embedding circular-economy practices into the downstream landscape. These projects lock in crude intake for upstream producers and frame Malaysia as a processing hub rather than a pure exporter of crude.
Untapped Deep-Water Reserves in Sarawak & Sabah
Frontier acreage in the Langkasuka and Layang-Layang clusters offers sizable gas and condensate potential that requires high-spec rigs, subsea tie-backs, and floating LNG solutions. The Malaysia Bid Round 2025 listed five exploration blocks and three Development and Risk-sharing Option clusters to catalyze investment. ConocoPhillips and Shell have shifted portfolio capital toward gas-weighted developments to maximize LNG feedstock security. The stable PSC framework and Petronas' role as resource custodian shorten lead times from discovery to first gas, enhancing the long-term competitiveness of the Malaysia oil and gas market.
High Crude-Price Volatility
Brent fluctuations between USD 70-90 per barrel in 2024-2025 disrupted cash-flow planning, deferred some final investment decisions, and raised borrowing costs. Marginal field economics remain sensitive to price dips, particularly where enhanced recovery requires costly gas lift or chemical injection. The Malaysian Oil, Gas and Energy Services Council's appeal for fiscal relief underscores exposure to market swings. While hedging and cost optimization help, sustained volatility may temper the pace of deep-water and decommissioning commitments.
Other drivers and restraints analyzed in the detailed report include:
- Rising Asian LNG Demand Lifting Malaysian Exports
- Downstream Petrochemical Integration Momentum
- Global Energy-Transition Investment Shift
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The upstream segment captured 74.85% of the Malaysia oil and gas market size in 2025, buoyed by robust PSC activity and Petronas' project pipeline. Jerun, Kasawari, and Gumusut-Kakap Redevelopment sustain plateau output while offsetting natural decline rates. The Malaysian oil and gas market share leadership in upstream activities reflects a geology rich in gas-condensate plays and a supportive fiscal regime that accelerates field monetization.
Upstream investment momentum will likely continue through 2031 as international operators secure acreage in deep-water wells and marginal redevelopments. Concurrently, midstream operators face rerouting challenges once the Sabah-Sarawak Gas Pipeline retires in 2027, requiring alternative evacuation for East Malaysian gas. Downstream players benefit from new feedstock when upstream debottlenecking releases incremental condensate volumes that feed into Pengerang's reformers.
Complete Report Scope:
- By Sector
- Upstream
- Midstream
- Downstream
- By Location
- Onshore
- Offshore
- By Service
- Construction
- Maintenance and Turn-around
- Decommissioning
List of Companies Covered in this Report:
- Petroliam Nasional Berhad (Petronas)
- Shell plc
- Exxon Mobil Corp.
- Chevron Corp.
- BP plc
- Hibiscus Petroleum Bhd
- Sapura Energy Bhd
- Dialog Group Bhd
- MISC Berhad
- Yinson Holdings Bhd
- PTTEP (Malaysia assets)
- Repsol Exploration (Malaysia) S.A.
- Lundin Energy Malaysia
- Murphy Oil Corporation (Malaysia)
- Serba Dinamik Holdings
- Velesto Energy Bhd
- Malaysia Marine & Heavy Engineering
- Altus Oil & Gas Malaysia Sdn Bhd
- Petro-Excel Sdn Bhd
- Petro Teguh (M) Sdn Bhd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for refined petroleum products
- 4.2.2 Untapped deep-water reserves (Sarawak & Sabah)
- 4.2.3 Incentive-driven PSC revisions & fiscal terms
- 4.2.4 Rising Asian LNG demand lifting Malaysian exports
- 4.2.5 CCUS & blue-hydrogen project pipeline
- 4.2.6 Downstream petrochemical integration momentum
- 4.3 Market Restraints
- 4.3.1 High crude-price volatility
- 4.3.2 Global energy-transition investment shift
- 4.3.3 ESG-driven capital access constraints
- 4.3.4 Aging offshore infrastructure & OPEX escalation
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Crude-Oil Production & Consumption Outlook
- 4.8 Natural-Gas Production & Consumption Outlook
- 4.9 Installed Pipeline Capacity Analysis
- 4.10 Unconventional Resources CAPEX Outlook (tight oil, oil sands, deep-water)
- 4.11 Porter's Five Forces
- 4.11.1 Bargaining Power - Suppliers
- 4.11.2 Bargaining Power - Buyers
- 4.11.3 Threat of New Entrants
- 4.11.4 Threat of Substitutes
- 4.11.5 Competitive Rivalry
- 4.12 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Sector
- 5.1.1 Upstream
- 5.1.2 Midstream
- 5.1.3 Downstream
- 5.2 By Location
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Service
- 5.3.1 Construction
- 5.3.2 Maintenance and Turn-around
- 5.3.3 Decommissioning
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Petroliam Nasional Berhad (Petronas)
- 6.4.2 Shell plc
- 6.4.3 Exxon Mobil Corp.
- 6.4.4 Chevron Corp.
- 6.4.5 BP plc
- 6.4.6 Hibiscus Petroleum Bhd
- 6.4.7 Sapura Energy Bhd
- 6.4.8 Dialog Group Bhd
- 6.4.9 MISC Berhad
- 6.4.10 Yinson Holdings Bhd
- 6.4.11 PTTEP (Malaysia assets)
- 6.4.12 Repsol Exploration (Malaysia) S.A.
- 6.4.13 Lundin Energy Malaysia
- 6.4.14 Murphy Oil Corporation (Malaysia)
- 6.4.15 Serba Dinamik Holdings
- 6.4.16 Velesto Energy Bhd
- 6.4.17 Malaysia Marine & Heavy Engineering
- 6.4.18 Altus Oil & Gas Malaysia Sdn Bhd
- 6.4.19 Petro-Excel Sdn Bhd
- 6.4.20 Petro Teguh (M) Sdn Bhd
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 義大利石油和天然氣:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)英國石油與天然氣:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)中國油氣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)印尼油氣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)東南亞油氣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)美國石油和天然氣:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)印度石油和天然氣:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026年全球油氣管道及相關結構建設市場報告
 石油和天然氣市場規模、佔有率和成長分析(按產品類型、產業類型、部署類型、應用和地區分類)-2026-2033年產業預測越南石油天然氣:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)