


 |
市場調查報告書
商品編碼
2120409
印尼油氣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)Indonesia Oil And Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,印尼石油和天然氣市場規模將從 2025 年的 138.8 億美元成長到 2026 年的 146 億美元,然後在 2031 年達到 188.1 億美元,2026 年至 2031 年的複合年成長率為 5.18%。
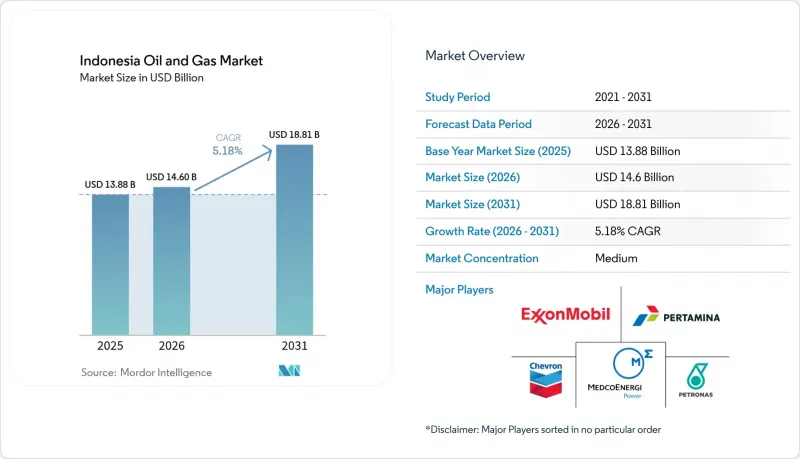
本報告按行業(上游、中游、下游)、地區(陸上和海上)和服務(建設、維護/檢修、退役)進行細分。市場規模和預測均以美元計價。
印尼油氣市場趨勢與洞察
中產階級的崛起推動了強勁的國內需求。
印尼不斷壯大的中產階級正在推動汽油、柴油和石化產品的消費成長,預計到2030年,原油日需求量將達到180萬桶,高於2025年的約160萬桶。隨著爪哇島的都市化超過60%,燃油效率提升工作正在推進,而交通運輸燃料的使用量也增加。個人收入的成長也帶動了對塑膠和包裝材料需求的增加。預計到2030年,天然氣需求將達到120億立方英尺/日,因為聯合循環發電廠可以彌補可再生能源的間歇性,並滿足工業鍋爐的需求。燃油補貼改革釋放了資金,這些資金正被重新用於公路、港口和公共交通項目,進一步刺激了能源需求,並提振了國內碳氫化合物的長期需求。
政府的這項計畫旨在 2030 年實現原油日產量 100 萬桶,天然氣日產量 120 億立方英尺。
SKK Migas的目標是日產100萬桶原油和120億立方英尺天然氣,以減少其對進口的依賴。目前,進口已佔其成品油需求的60%。優先措施包括加速核准127個區塊、為提高石油採收率(EOR)提供稅收優惠,以及建立數位化油田監測系統以提高邊際儲存的產量。阿巴迪液化天然氣計畫和唐湖擴建計畫等計畫有助於提高天然氣供給能力,而米納斯和杜利地區的蒸氣注入和化學驅油措施則有助於緩解自然損耗。在監管方面,引入「總分」產品分成合約(PSC)簡化了審計程序並保證了早期現金流,這促使雪佛龍、哈伯能源和Medco等公司決定進入這一前沿地區。
可再生能源的擴張和電動車的普及
印尼的目標是到2025年將可再生能源滲透率提高到23%,並在2060年達到淨零排放。這些雄心勃勃的目標促使資金從石化燃料計畫轉向再生能源,目前正在建造的太陽能、風能和地熱發電裝置總合達10吉瓦。針對電動車組裝廠的稅收優惠政策正吸引著來自世界各地的汽車製造商落腳西爪哇,這與印尼到2030年實現200萬輛電池式電動車上路行駛的國家目標相契合。儘管天然氣目前仍能彌補發電的不穩定性,但隨著收費公路沿線充電網路的建設,預計汽油需求將在長期內下降。然而,由於基礎設施短缺和價格敏感性,短期替代效應有限,預計印尼的油氣市場仍將保持其在交通運輸和工業領域的核心地位。
細分市場分析
預計到2025年,印尼油氣市場(上游領域)規模將達到100.1億美元,佔總營收的72.10%,並將在2031年之前以5.55%的複合年成長率成長。主要資本投資包括BP投資70億美元的唐古(Tangguh)地下氣田項目和Inpex投資200億美元的阿巴迪(Abadi)液化天然氣項目,這顯示各公司對長週期天然氣項目充滿信心。隨著盆地進入成熟階段,產品分成合約(PSC)改革、地下構造數位化成像以及油藏機器人技術正在提高現有儲存的採收率,並增強上游領域的現金流。
毛利分成生產分成合約(PSC)提高了透明度和成本確定性,為雪佛龍重返拉帕克區塊以及海港能源在圖納的加密鑽井計劃提供了支持。由印尼國家石油公司(Pertamina)和FPT軟體公司實施的數位化資產健康管理系統將意外停機時間減少了15%,展現了人工智慧整合帶來的營運優勢。中游領域的擴張——一條連接中蘇拉威西和爪哇的新管道——確保了運輸的經濟性,而下游領域圖班煉油廠的石化一體化則透過將重質原油轉化為高利潤烯烴,提高了獲利能力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 中產階級的壯大推動了強勁的國內需求。
- 政府努力實現 2030 年原油日產量 100 萬桶和天然氣日產量 120 億立方英尺的目標。
- 對東北亞液化天然氣出口的套利交易
- PSC 的總收益分成獎勵正在吸引國際石油公司 (IOC)。
- 二氧化碳捕集設施正在提高成熟油田的經濟可行性。
- 人工智慧驅動的數位化油田可降低石油開採成本
- 市場限制因素
- 可再生能源的擴張和電動車的普及
- 老舊生產區域的產量下降
- 土地權利和原住民社區之間的衝突
- ESG相關資金籌措限制
- 供應鏈分析
- 監理情勢
- 技術展望
- 原油產量和消費量預測
- 天然氣生產與消費預測
- 管道設置容量分析
- 非傳統資源(緻密油、油砂、深海油田)資本投資預測
- LNG接收站處理能力展望
- 波特五力模型
- PESTLE分析
第5章 市場規模與成長預測
- 按行業
- 上游部門
- 中游
- 下游產業
- 按位置
- 陸上
- 離岸
- 按服務
- 建造
- 維護和檢修
- 退休
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和市場佔有率)
- 公司簡介
- Pertamina
- Chevron
- ExxonMobil
- Shell
- BP
- Petronas
- ConocoPhillips
- Medco Energi
- Eni
- TotalEnergies
- Repsol
- Sinopec
- PGN
- Chandra Asri
- Inpex
- Mubadala Energy
- Harbour Energy
- Conrad Asia Energy
- PT Connusa Energindo
- CNOOC
第7章 市場機會與未來展望
According to Mordor Intelligence, the Indonesia oil and gas market size is expected to grow from USD 13.88 billion in 2025 to USD 14.6 billion in 2026 and is forecast to reach USD 18.81 billion by 2031 at 5.18% CAGR over 2026-2031.
This report is Segmented by Sector (Upstream, Midstream, and Downstream), Location (Onshore and Offshore), and Service (Construction, Maintenance and Turn-Around, and Decommissioning). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Indonesia Oil And Gas Market Trends and Insights
Robust Domestic Demand from Rising Middle Class
Indonesia's growing middle class is driving up gasoline, diesel, and petrochemical consumption, with daily crude demand projected to reach 1.8 million barrels by 2030, up from roughly 1.6 million barrels in 2025. Java's urbanization rate above 60% intensifies transport fuel use, despite efficiency drives, while rising personal incomes underpin higher demand for plastics and packaging. Natural gas demand is expected to reach 12 Bcf/d by 2030, as combined-cycle power plants supplement renewable energy intermittency and meet the needs of industrial boilers. Fuel-subsidy reforms redirect savings into roads, ports, and mass transit projects, which further spur energy needs, reinforcing the long-term pull for domestic hydrocarbons.
Government Push for 1 Million bbl/d Crude and 12 Bcf/d Gas by 2030
SKK Migas targets 1 million barrels per day (bbl/d) of oil and 12 billion cubic feet per day (Bcf/d) of gas to curb import dependence, which already covers 60% of refined-product demand. Priority accelerators include 127 blocks slated for fast-track approval, fiscal sweeteners for enhanced recovery, and digital field surveillance that lifts output from marginal reservoirs. Projects such as Abadi LNG and the Tangguh expansion underpin gas deliverability, whereas steamflood and chemical EOR initiatives at Minas and Duri slow base decline. The regulatory path features gross-split PSCs that streamline audits and guarantee earlier cash flow, attracting Chevron, Harbour Energy, and Medco into frontier acreage.
Renewable-Energy Build-Out and EV Adoption
Indonesia aims for 23% renewable energy penetration by 2025 and net-zero emissions by 2060, ambitions that redirect capital from fossil fuel projects into solar, wind, and geothermal units totaling 10 GW under construction. Fiscal incentives for EV assembly plants draw global OEMs to West Java, in line with a national goal of 2 million battery electric vehicles on the roads by 2030. While gas still balances intermittency, long-run gasoline demand faces attrition as charging networks densify across toll-road corridors. Yet infrastructure gaps and price sensitivity moderate short-term displacement, allowing the Indonesian oil and gas market to retain core transport and industrial segments.
Other drivers and restraints analyzed in the detailed report include:
- LNG Export Arbitrage to North-East Asia
- PSC Gross-Split Incentives Attracting IOCs
- Declining Output from Ageing Basins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Indonesia's oil and gas market size for the upstream segment was USD 10.01 billion in 2025, accounting for 72.10% of the overall revenue and projected to grow at a 5.55% CAGR through 2031. Major capital commitments include BP's USD 7 billion Tangguh UCC and Inpex's USD 20 billion Abadi LNG project, signaling durable corporate confidence in long-cycle gas projects. Production-sharing reforms, digital subsurface imaging, and reservoir robotics enhance recovery rates from legacy wells, reinforcing upstream cash flow even as basins mature.
Gross-split PSCs heighten transparency, with cost certainty spurring Chevron's return to the Rapak Block and Harbour Energy's infill campaign at Tuna. Digital asset integrity systems deployed by Pertamina and FPT Software reduced unplanned shutdowns by 15%, demonstrating the operational advantage that AI integration provides. Midstream expansions-new pipelines linking Central Sulawesi to Java-protect evacuation economics, while downstream petrochemical integration at Tuban refinery monetizes heavier crudes into high-margin olefins.
Complete Report Scope:
- By Sector
- Upstream
- Midstream
- Downstream
- By Location
- Onshore
- Offshore
- By Service
- Construction
- Maintenance and Turn-around
- Decommissioning
List of Companies Covered in this Report:
- Pertamina
- Chevron
- ExxonMobil
- Shell
- BP
- Petronas
- ConocoPhillips
- Medco Energi
- Eni
- TotalEnergies
- Repsol
- Sinopec
- PGN
- Chandra Asri
- Inpex
- Mubadala Energy
- Harbour Energy
- Conrad Asia Energy
- PT Connusa Energindo
- CNOOC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Robust domestic demand from rising middle class
- 4.2.2 Government push for 1 mb/d crude & 12 Bcf/d gas by 2030
- 4.2.3 LNG export arbitrage to North-East Asia
- 4.2.4 PSC gross-split incentives attracting IOCs
- 4.2.5 Carbon-capture hubs boosting mature-field economics
- 4.2.6 AI-enabled digital oilfields cutting lifting cost
- 4.3 Market Restraints
- 4.3.1 Renewable-energy build-out & EV adoption
- 4.3.2 Declining output from ageing basins
- 4.3.3 Land-right & indigenous community disputes
- 4.3.4 ESG-linked financing constraints
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Crude-Oil Production & Consumption Outlook
- 4.8 Natural-Gas Production & Consumption Outlook
- 4.9 Installed Pipeline Capacity Analysis
- 4.10 Unconventional Resources CAPEX Outlook (tight oil, oil sands, deep-water)
- 4.11 LNG Terminal Capacity Outlook
- 4.12 Porter's Five Forces
- 4.12.1 Threat of New Entrants
- 4.12.2 Bargaining Power of Suppliers
- 4.12.3 Bargaining Power of Buyers
- 4.12.4 Threat of Substitutes
- 4.12.5 Competitive Rivalry
- 4.13 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Sector
- 5.1.1 Upstream
- 5.1.2 Midstream
- 5.1.3 Downstream
- 5.2 By Location
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Service
- 5.3.1 Construction
- 5.3.2 Maintenance and Turn-around
- 5.3.3 Decommissioning
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Pertamina
- 6.4.2 Chevron
- 6.4.3 ExxonMobil
- 6.4.4 Shell
- 6.4.5 BP
- 6.4.6 Petronas
- 6.4.7 ConocoPhillips
- 6.4.8 Medco Energi
- 6.4.9 Eni
- 6.4.10 TotalEnergies
- 6.4.11 Repsol
- 6.4.12 Sinopec
- 6.4.13 PGN
- 6.4.14 Chandra Asri
- 6.4.15 Inpex
- 6.4.16 Mubadala Energy
- 6.4.17 Harbour Energy
- 6.4.18 Conrad Asia Energy
- 6.4.19 PT Connusa Energindo
- 6.4.20 CNOOC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

 義大利石油和天然氣:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)英國石油與天然氣:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)馬來西亞油氣:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)中國油氣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)東南亞油氣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)美國石油和天然氣:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)印度石油和天然氣:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026年全球油氣管道及相關結構建設市場報告
 石油和天然氣市場規模、佔有率和成長分析(按產品類型、產業類型、部署類型、應用和地區分類)-2026-2033年產業預測越南石油天然氣:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)