


 |
市場調查報告書
商品編碼
2120516
歐洲藥品包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Europe Pharmaceutical Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年歐洲藥品包裝市場價值 439.9 億美元,預計到 2031 年將達到 610.2 億美元,而 2026 年為 464.6 億美元,預測期(2026-2031 年)複合年成長率為 5.61%。
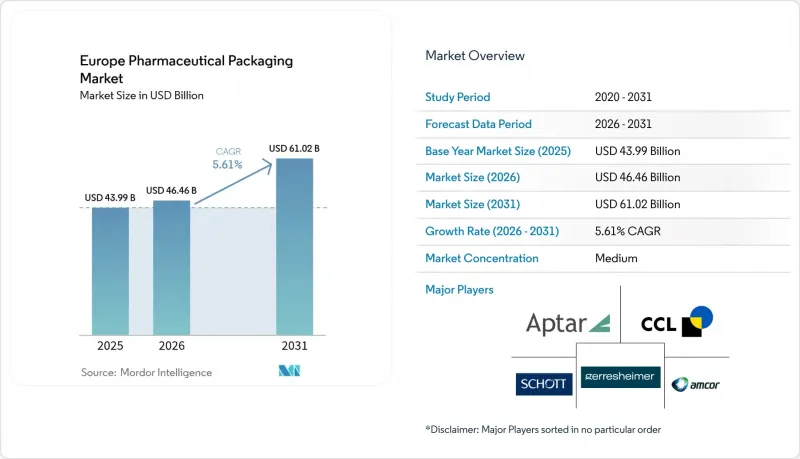
本報告按材料類型(塑膠、玻璃、金屬/箔等)、包裝類型(一級包裝、二級包裝、三級包裝)、技術(常規、無菌/滅菌等)、最終用戶(製藥企業、專業/生物技術公司、醫院/診所等)和國家/地區進行細分。市場預測以美元(USD)計價。
歐洲藥品包裝市場的趨勢與洞察
生物製藥和注射療法領域的成長
在歐洲藥品管理局 (EMA) 2024 年批准的新分子實體 (NME) 中,生物製藥產品佔比超過 30%,推動了對低萃取率和嚴格尺寸公差的注射容器的需求成長。肖特製藥 (SCHOTT Pharma) 公佈 2024 會計年度銷售額為 20.95 億歐元(23 億美元),其中 78% 來自藥物容器解決方案,例如 I 型硼矽酸管瓶和環烯烴聚合物藥筒。 West Pharmaceutical Services累計截至 2024 年 9 月的九個月銷售額為 19.8 億美元,主要來自其專有組件,例如 NovaPure 瓶塞和 Daikyo Crystal Zenith 注射器。 Stevanart 集團 2024 年上半年銷售額年增 11.6%,主要得益於 EZ-fill管瓶和 Nexa 自動注射器平台。 2024 年 9 月,Geresheimer、Stevanat 和 SCHOTT Pharma 達成合作協議,預計將規範成品藥的規格,從而縮短生物相似藥的合格週期,尤其是在契約製造成長最為顯著的波蘭和義大利。
歐盟嚴格的序列化法規
《反仿冒藥品指令》規定,所有在歐盟境內流通的處方藥包裝都必須配備唯一識別碼和防篡改裝置。預計到2026年,這將催生一個價值12億歐元的序列化標籤、2D條碼和NFC包裝盒的售後市場。 Schreiner Medipharm公司已擴展其NFC標籤產品線,以滿足真偽驗證和病人參與等應用情境的需求。 CCL Industries公司報告稱,2024年前九個月的銷售額為51億加元(37.5億美元)。醫療和特種標籤產業正受惠於此次整合升級。英國在脫歐後繼續沿用歐盟的序列化法規,要求標籤製造商提供與泛歐供應鏈相容的互通解決方案。
醫藥級原料價格波動
2024年,隨著歐洲能源成本飆升,硼矽酸玻璃管和環烯烴共聚物樹脂的價格上漲了18%至22%。由於連續式玻璃熔爐需要1500 度C的工作溫度,生產商不得不依賴天然氣,而天然氣價格極易受到地緣政治衝擊的影響。為了保護大京晶彩Zenith組件免受現貨價格波動的影響,West Pharmaceutical Services已簽訂了多年期樹脂供應合約。不斷上漲的原料成本正在加速對使用環烯烴聚合物和聚對苯二甲酸乙二醇酯等替代材料的研究,但這些替代材料在獲得歐洲藥品管理局(EMA)批准之前,需要大量的穩定性數據支持。
細分市場分析
到2025年,塑膠將以52.03%的市場佔有率在歐洲醫藥包裝市場佔據主導地位,這主要得益於聚對苯二甲酸乙二醇酯(PET)瓶和聚丙烯泡殼薄膜的強勁成長。玻璃仍將保持其以金額為準第二的位置,這主要得益於I型硼矽酸管瓶和玻璃筒。此外,Geresheimer、Schott Pharma和SGD Pharma在2023年至2027年間對熔爐設備的15億歐元(16.5億美元)投資將進一步鞏固這一市場。生物聚合物和複合材料預計將以6.86%的複合年成長率成長,這主要得益於品牌商希望在不影響阻隔性性能的前提下滿足PPWR的再生材料含量要求。 Amcor和Norato正在推進聚乳酸和聚羥基烷酯的認證,使其能夠用於非接觸層,並符合ISO 15378製程驗證標準。
監管壁壘減緩了生物聚合物在初級包裝容器中的應用,但大型加工商可以攤銷驗證成本,導致供應商市場兩極化。隨著《塑膠包裝說明書》(PPWR)在2028年後執行力度加大,口服固體製劑用塑膠的成長速度將會放緩,而玻璃和環烯烴聚合物將繼續在高價值生物製藥領域保持其高階地位。
預計到2025年,初級包裝將佔歐洲藥品包裝市場規模的62.10%,並預計到2031年將以6.58%的複合年成長率成長。片劑瓶仍然是最大的細分市場,但隨著注射和吸入劑佔有率的擴大,其成長速度正在放緩。預灌封注射器和藥筒是West Pharmaceutical Services公司19.8億美元專有組件銷售額的基礎,凸顯了藥物輸送系統固有的利潤率優勢。儘管匈牙利和塞爾維亞新增了產能,管瓶和小瓶仍面臨間歇性的供應限制。
二級包裝佔支出的30-35%,隨著序列化和近場通訊(NFC)技術的應用而成長,CCL Industries醫療保健標籤銷售額的成長便印證了這一點。三級包裝(瓦楞紙板)佔剩餘部分,主要得益於慢性病藥物的電商分銷。這些根本性的變化導致價值創造集中在一級包裝領域,而一級包裝目前仍面臨最高的監管准入門檻和技術複雜性。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 生技藥品和注射療法的成長
- 歐盟施加的嚴格序列化義務
- 對病人友善給藥方法的需求日益成長
- 引入支援NFC功能的智慧標籤,以防止偽造。
- 溫控郵購藥局的擴張
- 歐盟強制要求使用基於PPWR的再生醫用塑膠。
- 市場限制因素
- 醫藥級原料價格波動
- 與永續性相關的合規成本增加
- 醫藥級模製管瓶產能瓶頸
- 延長複合材料產品CE標誌審查期限
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
- 依劑型分析包裝需求(定性評估)
第5章 市場規模與成長預測
- 材料類型
- 塑膠
- 玻璃
- 紙張和紙板
- 金屬/箔
- 生物聚合物和複合材料
- 按包裝類型
- 初級包裝
- 瓶子
- 吸塑包裝
- 預灌封注射器
- 病毒安瓿
- 靜脈輸液容器
- 吸入器
- 其他主要包裝
- 二級包裝
- 折疊紙箱
- 標籤和插頁
- 袋子和小袋
- 托盤
- 其他二級包裝
- 三級包裝
- 紙板運輸箱
- 調色盤
- 其他三級包裝
- 初級包裝
- 透過技術
- 傳統的
- 無菌和滅菌
- 智慧互聯(NFC/RFID)
- 防偽/序列化
- 永續/可回收解決方案
- 兒童安全鎖和防篡改解決方案
- 最終用戶
- 製藥公司
- 專業公司/生技公司
- 契約製造/包裝業務
- 醫院和診所
- 國家
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 波蘭
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor Plc
- Gerresheimer AG
- Schott AG
- AptarGroup Inc.
- CCL Industries Inc.
- Stevanato Group SpA
- West Pharmaceutical Services Inc.
- SGD Pharma SAS
- Nolato AB
- Ardagh Group SA
- Bormioli Pharma SpA
- Nipro Corporation
- Origin Pharma Packaging Ltd.
- Gaplast GmbH
- DWK Life Sciences GmbH
- IntraPac International LLC
- Vetter Pharma-Fertigung GmbH and Co. KG
- Romaco Group GmbH
- APG Europe BV
- Piramal Pharma Solutions
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe pharmaceutical packaging market size was valued at USD 43.99 billion in 2025 and estimated to grow from USD 46.46 billion in 2026 to reach USD 61.02 billion by 2031, at a CAGR of 5.61% during the forecast period (2026-2031).
This report is Segmented by Material Type (Plastic, Glass, Metal/Foil, and More), Packaging Type (Primary Packaging, Secondary Packaging, Tertiary Packaging), Technology (Conventional, Aseptic and Sterile, and More), End User (Pharmaceutical Manufacturers, Specialty/Biotech Firms, Hospitals and Clinics, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Pharmaceutical Packaging Market Trends and Insights
Growth of Biologics and Injectable Therapies
Biologics accounted for more than 30% of new molecular entities approved by the European Medicines Agency in 2024, elevating demand for parenteral containers with low extractables and tight dimensional tolerances. SCHOTT Pharma reported EUR 2.095 billion (USD 2.30 billion) in fiscal 2024 revenue, 78% of which came from drug containment solutions, including Type I borosilicate vials and cyclic olefin polymer cartridges. West Pharmaceutical Services derived USD 1.98 billion from proprietary components, including NovaPure stoppers and Daikyo Crystal Zenith syringes in the nine months to September 2024. Stevanato Group grew its first-half 2024 revenue 11.6% year over year, driven by EZ-fill vials and the Nexa autoinjector platform. A September 2024 alliance among Gerresheimer, Stevanato, and SCHOTT Pharma is expected to harmonize ready-to-fill specifications, potentially reducing qualification timelines for biosimilars, particularly in Poland and Italy, where contract manufacturing growth is strongest.
Stringent EU Serialization Mandates
The Falsified Medicines Directive requires every prescription pack distributed in the European Union to carry a unique identifier and a tamper-evident device, generating a EUR 1.2 billion aftermarket for serialized labels, 2D barcodes, and NFC-equipped cartons through 2026. Schreiner MediPharm has expanded its NFC label portfolio to support authentication and patient engagement use cases. CCL Industries reported CAD 5.1 billion (USD 3.75 billion) revenue for the first nine months of 2024, with healthcare and specialty labels benefiting from aggregation upgrades. The United Kingdom has mirrored EU serialization rules post-Brexit, compelling label converters to deliver interoperable solutions for pan-European supply chains.
Volatility in Pharmaceutical-Grade Raw Material Prices
Borosilicate glass tubing and cyclic olefin copolymer resins climbed 18-22% in 2024 as European energy costs surged. Continuous glass furnaces require an operating temperature of 1,500 °C, anchoring producers to natural-gas inputs that remain vulnerable to geopolitical shocks. West Pharmaceutical Services now secures its supply with multi-year resin contracts to protect Daikyo Crystal Zenith components from spot-price fluctuations. Elevated input costs have accelerated material-substitution studies involving cyclic olefin polymer and polyethylene terephthalate glycol; however, these alternatives require extensive stability data before EMA approval.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of NFC-Enabled Smart Labels for Anti-Counterfeiting
- Expansion of Temperature-Controlled Mail-Order Pharmacies
- Capacity Bottlenecks for Pharma-Grade Molded Glass Vials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics dominated the Europe pharmaceutical packaging market with a 52.03% share in 2025, led by polyethylene terephthalate bottles and polypropylene blister films. Glass remained second in value, owing to Type I borosilicate vials and cartridges, a segment fortified by EUR 1.5 billion (USD 1.65 billion) in furnace investments from Gerresheimer, Schott Pharma, and SGD Pharma between 2023 and 2027. Biopolymers and composite materials are projected to grow at a 6.86% CAGR, driven by brand owners seeking to meet PPWR recycled-content requirements without compromising barrier properties. Amcor and Nolato are qualifying polylactic and polyhydroxyalkanoate resins for non-contact layers that still meet the ISO 15378 process validation thresholds.
Regulatory hurdles slow the uptake of biopolymers in primary containers, yet converters with scale can amortize validation costs, creating a two-tier supplier landscape. As PPWR enforcement tightens after 2028, growth in plastics for oral-solid dosage formats will moderate, while Glass and cyclic olefin polymers will retain their premium status in high-value biologics.
Primary formats are expected to account for 62.10% of the Europe pharmaceutical packaging market size in 2025 and are projected to rise at a 6.58% CAGR through 2031. Bottles for tablets remain the largest sub-segment, but their growth lags as injectables and inhalables gain share. Pre-fillable syringes and cartridges underpin West Pharmaceutical Services' USD 1.98 billion proprietary-components revenue, highlighting the margin leverage embedded in drug-delivery systems. Vials and ampules face intermittent supply constraints despite the introduction of new capacity in Hungary and Serbia.
Secondary packaging, which accounts for 30-35% of spending, grows in tandem with serialization and NFC adoption, as evidenced by CCL Industries' healthcare-label revenue uptick. Tertiary corrugated packs hold the balance, aided by e-commerce distribution for chronic-disease therapies. The underlying shift concentrates value creation in primary packs where regulatory moats and technical complexity remain highest.
Complete Report Scope:
- By Material Type
- Plastic
- Glass
- Paper and Paperboard
- Metal/Foil
- Biopolymers and Composite Materials
- By Packaging Type
- Primary Packaging
- Bottles
- Blister Packs
- Pre-fillable Syringes
- Vials and Ampoules
- IV Containers
- Inhalers
- Other Primary Packagings
- Secondary Packaging
- Folding Cartons
- Labels and Inserts
- Bags and Pouches
- Trays
- Other Secondary Packagings
- Tertiary Packaging
- Corrugated Shippers
- Pallets
- Other Tertiary Packagings
- Primary Packaging
- By Technology
- Conventional
- Aseptic and Sterile
- Smart and Connected (NFC/RFID)
- Anti-counterfeit / Serialisation
- Sustainable / Recyclable Solutions
- Child-Resistant and Tamper-Evident Solutions
- By End User
- Pharmaceutical Manufacturers
- Specialty/Biotech Firms
- Contract Manufacturing and Packaging Organizations
- Hospitals and Clinics
- By Country
- United Kingdom
- Germany
- France
- Spain
- Italy
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Amcor Plc
- Gerresheimer AG
- Schott AG
- AptarGroup Inc.
- CCL Industries Inc.
- Stevanato Group S.p.A.
- West Pharmaceutical Services Inc.
- SGD Pharma SAS
- Nolato AB
- Ardagh Group S.A.
- Bormioli Pharma S.p.A.
- Nipro Corporation
- Origin Pharma Packaging Ltd.
- Gaplast GmbH
- DWK Life Sciences GmbH
- IntraPac International LLC
- Vetter Pharma-Fertigung GmbH and Co. KG
- Romaco Group GmbH
- APG Europe B.V.
- Piramal Pharma Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of Biologics and Injectable Therapies
- 4.2.2 Stringent EU Serialization Mandates
- 4.2.3 Rising Demand for Patient-Friendly Drug Delivery Formats
- 4.2.4 Adoption of NFC-Enabled Smart Labels for Anti-Counterfeiting
- 4.2.5 Expansion of Temperature-Controlled Mail-Order Pharmacies
- 4.2.6 Recycled Medical-Grade Plastics Mandate Under EU PPWR
- 4.3 Market Restraints
- 4.3.1 Volatility in Pharmaceutical-Grade Raw Material Prices
- 4.3.2 Increasing Sustainability Compliance Costs
- 4.3.3 Capacity Bottlenecks for Pharma-Grade Molded Glass Vials
- 4.3.4 Extended CE-Mark Review Timelines for Combination Products
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Packaging Demand Analysis by Dosage Form (Qualitative Assessment)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.2 Glass
- 5.1.3 Paper and Paperboard
- 5.1.4 Metal/Foil
- 5.1.5 Biopolymers and Composite Materials
- 5.2 By Packaging Type
- 5.2.1 Primary Packaging
- 5.2.1.1 Bottles
- 5.2.1.2 Blister Packs
- 5.2.1.3 Pre-fillable Syringes
- 5.2.1.4 Vials and Ampoules
- 5.2.1.5 IV Containers
- 5.2.1.6 Inhalers
- 5.2.1.7 Other Primary Packagings
- 5.2.2 Secondary Packaging
- 5.2.2.1 Folding Cartons
- 5.2.2.2 Labels and Inserts
- 5.2.2.3 Bags and Pouches
- 5.2.2.4 Trays
- 5.2.2.5 Other Secondary Packagings
- 5.2.3 Tertiary Packaging
- 5.2.3.1 Corrugated Shippers
- 5.2.3.2 Pallets
- 5.2.3.3 Other Tertiary Packagings
- 5.2.1 Primary Packaging
- 5.3 By Technology
- 5.3.1 Conventional
- 5.3.2 Aseptic and Sterile
- 5.3.3 Smart and Connected (NFC/RFID)
- 5.3.4 Anti-counterfeit / Serialisation
- 5.3.5 Sustainable / Recyclable Solutions
- 5.3.6 Child-Resistant and Tamper-Evident Solutions
- 5.4 By End User
- 5.4.1 Pharmaceutical Manufacturers
- 5.4.2 Specialty/Biotech Firms
- 5.4.3 Contract Manufacturing and Packaging Organizations
- 5.4.4 Hospitals and Clinics
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Spain
- 5.5.5 Italy
- 5.5.6 Poland
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor Plc
- 6.4.2 Gerresheimer AG
- 6.4.3 Schott AG
- 6.4.4 AptarGroup Inc.
- 6.4.5 CCL Industries Inc.
- 6.4.6 Stevanato Group S.p.A.
- 6.4.7 West Pharmaceutical Services Inc.
- 6.4.8 SGD Pharma SAS
- 6.4.9 Nolato AB
- 6.4.10 Ardagh Group S.A.
- 6.4.11 Bormioli Pharma S.p.A.
- 6.4.12 Nipro Corporation
- 6.4.13 Origin Pharma Packaging Ltd.
- 6.4.14 Gaplast GmbH
- 6.4.15 DWK Life Sciences GmbH
- 6.4.16 IntraPac International LLC
- 6.4.17 Vetter Pharma-Fertigung GmbH and Co. KG
- 6.4.18 Romaco Group GmbH
- 6.4.19 APG Europe B.V.
- 6.4.20 Piramal Pharma Solutions
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2026-2030年全球實驗室耗材初級包裝市場
 中國藥品包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)
 全球藥品包裝市場規模、佔有率、趨勢和成長分析報告(2026-2034年)菲律賓藥品包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)印度藥品包裝市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 實驗室耗材初級包裝市場-2026-2032年全球市場預測北美藥品包裝市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)醫藥包裝器材:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)醫藥瓶市場:2026-2032年全球市場預測(依產品類型、材質、容量、瓶蓋、瓶型、應用及通路分類)全球生物製藥包裝市場規模、佔有率、趨勢和成長分析報告(2026-2034)