


 |
市場調查報告書
商品編碼
2118238
新加坡企業內容管理 (ECM):市佔率分析、產業趨勢與統計及成長預測 (2026-2031)Singapore Enterprise Content Management (ECM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
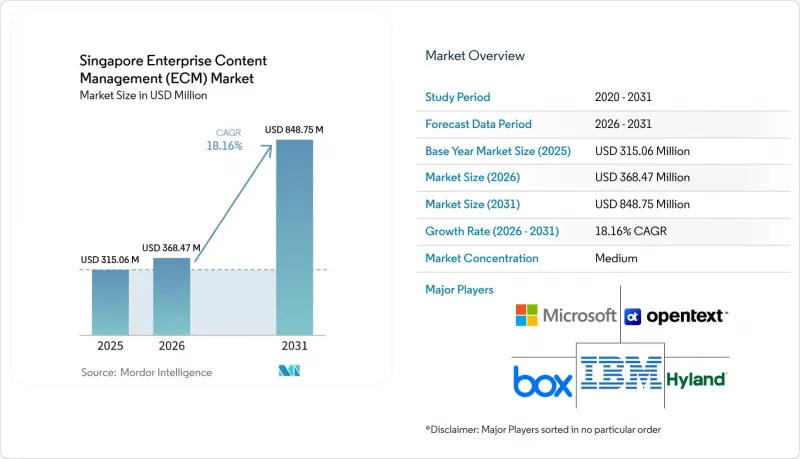
據 Mordor Intelligence 稱,新加坡企業內容管理 (ECM) 市場在 2025 年的價值為 3.1506 億美元,預計到 2031 年將達到 8.4875 億美元,而 2026 年為 3.6847 億美元,2026 年成長率 2031 年成長率為 18.18.18 年。
本報告按解決方案類型(文件管理、記錄管理等)、部署模式(本地部署、雲端部署、混合部署)、企業規模(中小企業、大型企業)和最終用戶行業(銀行、金融服務和保險 (BFSI)、政府和公共部門、醫療保健、IT 和電信等)進行細分。市場預測以美元 (USD) 計價。
新加坡企業內容管理 (ECM) 市場趨勢與洞察
AI 副駕駛整合到內容工作流程中
在新加坡的企業內容管理 (ECM) 市場,人工智慧輔助工具正在改變資訊處理方式。這是因為用戶現在期望平台能夠指導他們的操作,而不僅僅是搜尋文件。這些工具可以在文件處理過程中提案、指定核准流程並提取異常訊息,從而減少營運和合規團隊的手動工作量。 Hyland 於 2026 年 6 月發布了其企業上下文引擎 (Enterprise Context Engine)。該產品包含針對醫療保健、金融服務、保險和政府機構等特定產業本體,展示了供應商如何將特定領域的人工智慧整合到內容系統中。新加坡政府科技局 (GovTech) 也向新加坡政府機構部署了 AISAY v2。該平台可以在幾秒鐘內處理大量文檔,並產生可用於工作流程的結構化 JSON 輸出。這種轉變正在推動新加坡企業內容管理 (ECM) 市場的需求,因為買家現在將人工智慧驅動的內容處理視為日常流程管理的一部分,而不是未來的附加功能。
資料居住要求和主權要求
在新加坡企業內容管理 (ECM) 市場,資料居住法規正成為一項關鍵的採購標準,尤其對於那些管理高度敏感的財務、個人或醫療記錄的機構而言更是如此。新加坡的《個人資料保護法》(PDPA) 對個人資料的處理和傳輸規定了相關義務,使得跨境管理成為內容平台選擇的關鍵因素。在銀行、金融和保險 (BFSI) 以及醫療保健行業,這一問題尤其突出,因為這些行業的內容存儲庫存儲著需要在明確的管轄權和更嚴格的管治控制下進行保護的記錄。微軟計劃在 2025 年至 2029 年間向新加坡的雲端和人工智慧基礎設施投資 55 億美元,這將增強本地能力,以滿足新加坡企業內容管理 (ECM) 市場的需求。因此,能夠兼顧雲端效能和管轄權保障的供應商將在新加坡企業內容管理 (ECM) 市場的競爭格局中佔據顯著優勢。
與舊有系統整合的複雜性
整合複雜性仍然是新加坡企業內容管理 (ECM) 市場最大的結構性限制因素,尤其是在那些資訊系統已運作多年的大型企業中。銀行、金融和保險 (BFSI) 行業以及政府機構的舊存儲庫通常包含自定義元元資料結構、點對點鏈接,以及與 ERP、HRMS 和核心操作系統之間文檔不完善的連接。這使得遷移過程比許多買家最初預期的更長、更昂貴,並且更依賴分階段遷移計劃。新加坡住宅發展局 (HDB) 透過 GeBIZ 於 2026 年 5 月發布的一項人工智慧驅動的知識管理系統競標,明確要求與現有資訊系統、文件儲存系統和基於角色的存取控制整合,凸顯了整合的巨大負擔。因此,即使採購已獲批准,新加坡企業內容管理 (ECM) 市場的部署計劃也很容易遠遠超出最初的計劃。
細分市場分析
到2025年,文件管理將佔據32.14%的最大市場佔有率,使其成為新加坡企業內容管理(ECM)市場買家最明確的切入點。由於銀行、金融服務和保險(BFSI)機構需要確保貸款檔案、KYC(了解你的客戶)記錄和監管文件按照保留和審計要求進行管理,因此該領域仍然至關重要。合規主導的文件處理是一項持續性工作,不易受短期預算波動的影響,因此該領域在新加坡企業內容管理(ECM)行業中繼續佔據重要地位。雖然記錄管理和案例管理的規模相對較小,但在需要加強生命週期管理和系統化處理受監管文件的機構中,它們仍然發揮著重要作用。
預計從2026年到2031年,工作流程和業務流程管理將以20.83%的複合年成長率成長,成為新加坡企業內容管理(ECM)市場成長最快的解決方案領域。這一成長主要得益於人工智慧在以往需要人工操作的流程(例如核准流程、異常處理和團隊交接)中的廣泛應用。數位資產管理持續滿足媒體、零售和行銷產業日益專業化的需求,而網路內容管理則為金融服務和公共部門的發布和揭露工作流程提供了支援。 「其他解決方案」(包括文件擷取和電子郵件歸檔)繼續在中型企業買家透過早期數位轉型專案進入新加坡企業內容管理(ECM)市場的過程中發揮重要作用。
預計到2025年,雲端採用率將佔新加坡企業內容管理(ECM)市場79.41%的市場佔有率,成為成長最快的採用模式,複合年成長率(CAGR)高達21.24%,凸顯了新加坡企業內容管理市場向「雲端優先」採購策略的堅定轉變。該市場並非傳統架構與新型架構的對立,因為大多數新增投資並非用於初始雲端試用,而是為了擴展現有雲端應用。雲端是規模最大且成長最快的細分市場,顯示企業對此模式的信心已超越試點階段。對許多買家而言,雲端現已成為新加坡企業內容管理(ECM)市場中新內容項目的預設架構。
這一發展勢頭得益於本地基礎設施的不斷完善以及人們對管理管治的託管環境日益成長的信心。微軟在新加坡多年來的基礎設施建設工作正在增強其處理能力,以滿足自主運作和人工智慧工作負載的需求。混合部署模式在大規模銀行、金融和保險(BFSI)機構以及需要對特定內容類別進行更嚴格控制的政府機構中仍然發揮著實際作用,而對於涉及敏感資訊和機密文件的有限用例,本地部署系統仍然是必要的。儘管如此,長期發展趨勢仍表明,企業將進一步擺脫傳統的部署模式,預計雲端仍將是新加坡企業內容管理(ECM)市場的核心。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- AI 副駕駛已整合到內容創作工作流程中
- 關於資料位置和主權的要求
- 零信任內容存取控制
- 傳統程式碼庫的雲端遷移
- 特定產業合規自動化
- 對無程式碼工作流程編配。
- 市場限制因素
- 與舊有系統整合的複雜性
- 使用者對內容管治法規的抵制
- 對平台套件中供應商鎖定問題的擔憂
- 智慧內容管理方面的技能差距
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按解決方案類型
- 文件管理
- 記錄管理
- 工作流程和業務流程管理
- 個案管理
- 數位資產管理
- 網站內容管理
- 其他解決方案
- 部署模式
- 現場
- 雲
- 混合
- 按公司規模
- 小型企業
- 大公司
- 按最終用戶行業分類
- BFSI
- 政府/公共部門
- 衛生保健
- 資訊科技/通訊
- 製造業
- 零售
- 媒體與娛樂
- 教育
- 能源公用事業
- 其他終端用戶產業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software, Inc.
- Oracle Corporation
- Box, Inc.
- Adobe Inc.
- Xerox Holdings Corporation
- M-Files Corporation
- Alfresco Software, Inc.
- DocuWare GmbH
- Datamatics Global Services Limited
- Newgen Software Technologies Limited
- Laserfiche, Inc.
- Yonyou Singapore
- Fujifilm Business Innovation Corp
- KYOCERA Document Solutions Singapore Pte. Ltd
- KnowledgeLake, Inc.
- iManage, LLC
- Egnyte, Inc.
- Objective Corporation Limited
- Zoho Corporation Pvt. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Singapore enterprise content management (ECM) market size was valued at USD 315.06 million in 2025 and estimated to grow from USD 368.47 million in 2026 to reach USD 848.75 million by 2031, at a CAGR of 18.16% during the forecast period 2026-2031.
This report is Segmented by Solution Type (Document Management, Records Management, and More), Deployment Mode (On-Premises, Cloud, and Hybrid), Enterprise Size (Small and Medium Enterprises, and Large Enterprises), and End-User Industry (BFSI, Government and Public Sector, Healthcare, IT and Telecommunications, and More). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Enterprise Content Management (ECM) Market Trends and Insights
AI Copilots Embedded in Content Workflows
AI copilots are changing how the Singapore enterprise content management (ECM) market handles stored information, because users now expect platforms to guide work rather than only retrieve files. These tools can suggest classifications, route approvals, and surface exceptions during document handling, reducing manual effort for operations and compliance teams. Hyland launched its Enterprise Context Engine in June 2026, featuring sector-specific ontologies for healthcare, financial services, insurance, and government, demonstrating how vendors are integrating domain-aware AI into content systems. GovTech also deployed AISAY v2 in Singapore government agencies, and the platform can process large document sets in seconds and return structured JSON outputs for workflow use. This shift is boosting demand in the Singapore enterprise content management (ECM) market, as buyers now see AI-driven content handling as part of day-to-day process control rather than a future add-on.
Data Residency and Sovereignty Requirements
Data residency rules are becoming a core buying factor in the Singapore enterprise content management (ECM) market, especially for organizations that manage sensitive financial, personal, or clinical records. Singapore's PDPA imposes obligations on how personal data is handled and transferred, keeping cross-border controls central to content platform selection. This issue is more visible in BFSI and healthcare, where content repositories hold records that need clear jurisdictional protection and stronger governance controls. Microsoft's USD 5.5 billion investment in cloud and AI infrastructure in Singapore from 2025 through 2029 reinforces the local capacity needed to support this demand in the Singapore enterprise content management (ECM) market. As a result, vendors that can align cloud performance with jurisdictional assurance are better placed in competitive evaluations across the Singapore enterprise content management (ECM) market.
High Integration Complexity With Legacy Systems
Integration complexity remains the biggest structural restraint in the Singapore enterprise content management (ECM) market, especially among large enterprises with long-established information systems. Older repositories in BFSI and government often include custom metadata structures, point-to-point links, and poorly documented connections to ERP, HRMS, and core operating systems. This makes migration slower, costlier, and more dependent on staged transition plans than many buyers first expect. A May 2026 GeBIZ tender from the Housing and Development Board for an AI-driven knowledge management system explicitly required integration with existing information systems, document storage, and role-based access controls, underscoring the centrality of the integration burden. Because of this, deployment timelines in the Singapore enterprise content management (ECM) market can stretch well beyond initial plans even when procurement approval is already in place.
Other drivers and restraints analyzed in the detailed report include:
- Zero Trust Content Access Controls
- Cloud Migration of Legacy Repositories
- User Resistance to Content Governance Discipline
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Document management held the largest share at 32.14% in 2025, which made it the clearest entry point for buyers in the Singapore enterprise content management (ECM) market. It remained central because BFSI institutions needed reliable control over loan files, KYC records, and regulatory correspondence that aligned with retention and audit expectations. This part of the Singapore enterprise content management (ECM) industry also kept its weight because compliance-driven document handling is recurring and less exposed to short-term budget swings. Records management and case management stayed smaller, but they remained important where organizations needed stronger lifecycle control and structured handling of regulated files.
Workflow and business process management is projected to grow at a 20.83% CAGR from 2026 to 2031, making it the fastest-growing solution area in the Singapore enterprise content management (ECM) market. Growth is being driven by the broader adoption of AI for approval routing, exception handling, and cross-team handoffs that were once handled manually. Digital asset management continued to serve more focused needs in media, retail, and marketing functions, while web content management supported publishing and disclosure workflows across financial services and the public sector. The other solutions group, which includes document capture and email archiving, remained relevant for mid-market buyers entering the Singapore enterprise content management (ECM) market through early-stage digitization programs.
Cloud deployment held a 79.41% share in 2025 and ranked as the fastest-growing mode at a 21.24% CAGR, underscoring how firmly the Singapore enterprise content management (ECM) market has aligned around cloud-first buying. This is not a split market between old and new architectures, because most new investments are now expanding cloud use rather than testing it for the first time. The fact that cloud is both the largest and fastest-growing segment suggests that enterprise confidence in this model has already moved beyond the pilot stage. For many buyers, cloud is now the default architecture for new content programs in the Singapore enterprise content management (ECM) market.
That momentum is supported by local infrastructure expansion and stronger confidence in governed hosting environments. Microsoft's multiyear infrastructure commitment in Singapore is reinforcing the capacity needed for sovereign and AI-ready workloads. Hybrid deployment still held a practical role among large BFSI institutions and government agencies that needed tighter control over selected content classes, while on-premises systems remained necessary in limited use cases involving sensitive or classified material. Even so, the longer-term direction still points toward additional migration away from traditional deployments, which should keep the cloud at the center of the Singapore enterprise content management (ECM) market.
Complete Report Scope:
- By Solution Type
- Document Management
- Records Management
- Workflow and Business Process Management
- Case Management
- Digital Asset Management
- Web Content Management
- Other Solutions
- By Deployment Mode
- On-Premises
- Cloud
- Hybrid
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Industry
- BFSI
- Government and Public Sector
- Healthcare
- IT and Telecommunications
- Manufacturing
- Retail
- Media and Entertainment
- Education
- Energy and Utilities
- Other End-User Industries
List of Companies Covered in this Report:
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software, Inc.
- Oracle Corporation
- Box, Inc.
- Adobe Inc.
- Xerox Holdings Corporation
- M-Files Corporation
- Alfresco Software, Inc.
- DocuWare GmbH
- Datamatics Global Services Limited
- Newgen Software Technologies Limited
- Laserfiche, Inc.
- Yonyou Singapore
- Fujifilm Business Innovation Corp
- KYOCERA Document Solutions Singapore Pte. Ltd
- KnowledgeLake, Inc.
- iManage, LLC
- Egnyte, Inc.
- Objective Corporation Limited
- Zoho Corporation Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI Copilots Embedded in Content Workflows
- 4.2.2 Data Residency and Sovereignty Requirements
- 4.2.3 Zero Trust Content Access Controls
- 4.2.4 Cloud Migration of Legacy Repositories
- 4.2.5 Industry-Specific Compliance Automation
- 4.2.6 No-Code Workflow Orchestration Demand
- 4.3 Market Restraints
- 4.3.1 High Integration Complexity With Legacy Systems
- 4.3.2 User Resistance to Content Governance Discipline
- 4.3.3 Vendor Lock-In Concerns in Platform Suites
- 4.3.4 Skills Gap in Intelligent Content Operations
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution Type
- 5.1.1 Document Management
- 5.1.2 Records Management
- 5.1.3 Workflow and Business Process Management
- 5.1.4 Case Management
- 5.1.5 Digital Asset Management
- 5.1.6 Web Content Management
- 5.1.7 Other Solutions
- 5.2 By Deployment Mode
- 5.2.1 On-Premises
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 Government and Public Sector
- 5.4.3 Healthcare
- 5.4.4 IT and Telecommunications
- 5.4.5 Manufacturing
- 5.4.6 Retail
- 5.4.7 Media and Entertainment
- 5.4.8 Education
- 5.4.9 Energy and Utilities
- 5.4.10 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 OpenText Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Hyland Software, Inc.
- 6.4.5 Oracle Corporation
- 6.4.6 Box, Inc.
- 6.4.7 Adobe Inc.
- 6.4.8 Xerox Holdings Corporation
- 6.4.9 M-Files Corporation
- 6.4.10 Alfresco Software, Inc.
- 6.4.11 DocuWare GmbH
- 6.4.12 Datamatics Global Services Limited
- 6.4.13 Newgen Software Technologies Limited
- 6.4.14 Laserfiche, Inc.
- 6.4.15 Yonyou Singapore
- 6.4.16 Fujifilm Business Innovation Corp
- 6.4.17 KYOCERA Document Solutions Singapore Pte. Ltd
- 6.4.18 KnowledgeLake, Inc.
- 6.4.19 iManage, LLC
- 6.4.20 Egnyte, Inc.
- 6.4.21 Objective Corporation Limited
- 6.4.22 Zoho Corporation Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 企業架構服務市場:全球市場預測,2026-2032年
 中國企業內容管理(ECM):市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國企業內容管理 (ECM):市場佔有率分析、行業趨勢和統計數據以及成長預測 (2026-2031)義大利企業內容管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)西班牙企業內容管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)企業內容管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)基於雲端的企業內容管理市場-2026年至2032年全球市場預測雲端的企業內容管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 Frost Radar™:數位媒體內容安全與反派餅服務,2026 年企業內容管理市場-2026-2032年全球市場預測