


 |
市場調查報告書
商品編碼
2118232
中國企業內容管理(ECM):市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)China Enterprise Content Management (ECM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
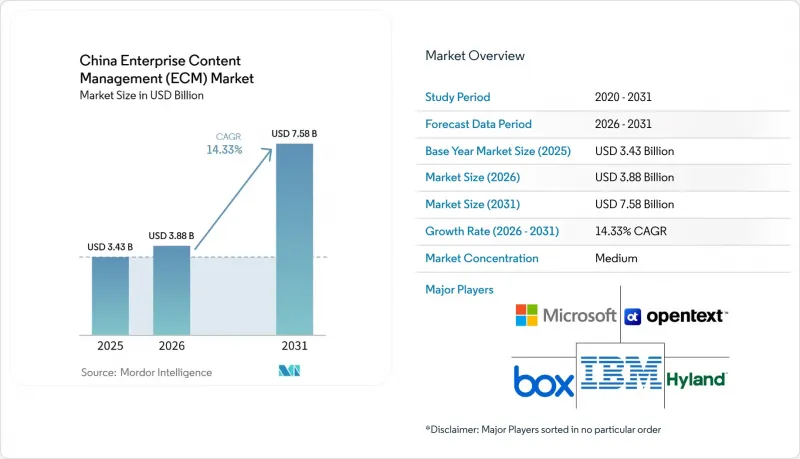
根據 Mordor Intelligence 預測,中國企業內容管理 (ECM) 市場規模預計到 2025 年將達到 34.3 億美元,到 2026 年將達到 38.8 億美元,到 2031 年將達到 75.8 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 14.33%。
本報告按解決方案類型(文件管理、記錄管理等)、部署模式(本地部署、雲端部署、混合部署)、企業規模(中小企業、大型企業)和最終用戶行業(銀行、金融服務和保險業、政府和公共部門、醫療保健等)進行細分。市場預測以美元計價。
中國企業內容管理(ECM)市場的趨勢與洞察
中國企業向數位化記錄的轉變正在加速。
中國企業仍然擁有大量紙本記錄,這導致存取受限、回應延遲以及儲存風險增加。在銀行、能源和製藥等監管嚴格的行業,這種壓力尤其突出,因為這些行業的檔案往往多年累積。因此,數位化遷移已不僅僅是一個現代化項目,更成為推動大規模採購的催化劑。採集、掃描、索引和元資料準備的重要性也日益凸顯,因為這些流程決定了數位化內容遷移後的效用。隨著中國企業內容管理 (ECM) 市場的擴張,能夠將儲存庫管理與更快的資料擷取速度和特定產業文件結構相結合的供應商有望從中受益。
人工智慧驅動的內容分類與搜尋效率
人工智慧正在改變企業內容系統的角色,使其從單純的儲存轉變為主動決策支援。如今,買家期望平台能夠對文件進行分類、檢測重複項、標記衝突並提取相關內容,而無需耗時的人工審核流程。 2026年1月實施的WPS 365智慧文件庫升級報告顯示,重複項檢測準確率高達95%,衝突辨識準確率達80%,顯示內容管理在日常營運中的重要性日益凸顯。這項轉變對中國企業內容管理(ECM)市場意義重大,因為中文業務記錄、採購文件和監管文件都需要強大的在地化功能。此外,IBM於2025年11月發布的Core Content Services MCP Server預覽版顯示,全球供應商正在將人工智慧模型直接整合到內容儲存庫中,從而提高了人工智慧資訊管理的標準。
複雜的本地化和資料居住需求
在中國企業內容管理 (ECM) 市場,在地化仍然是一大障礙,因為資料管治法規會影響架構、託管和發布管理。為了有效參與競爭,外國供應商通常需要獨立的本地環境、更嚴格的資料隔離以及符合中國特定營運規範的作業流程。與全球產品週期相比,這會增加成本並延緩新功能的部署。而國內供應商在這方面則更具優勢,因為他們的平台已經針對本地部署需求進行了客製化。例如,2026 年 5 月向政府機構發布的「WPS 新華智慧安全版」就凸顯了完全在地化技術堆疊在高度敏感環境中的實際優勢。
細分市場分析
在2025年中國企業內容管理(ECM)市場中,文件管理佔26.42%,成為最大的解決方案類別。版本控制、集中儲存和檔案存取規則仍然是許多買家的起點,因為它們通常是正式內容管治的第一步。這種主導地位反映了一種常見的採購路徑:企業首先穩定文件管理,然後擴展到更廣泛的儲存、審核和流程管理。記錄管理和Web內容管理通常在初始層級建立之後才會擴展,尤其是在合規性和發布需求難以手動管理的情況下。
預計到2031年,工作流程和業務流程管理將以16.94%的複合年成長率成長,成為中國企業內容管理(ECM)市場中成長最快的解決方案細分領域。隨著企業希望加快跨部門的核准、審核和基於內容的決策,市場需求不斷成長。數位資產管理和案例管理仍然是重要的細分領域,儘管規模較小。數位資產管理在企業處理媒體庫和品牌相關文件時變得越來越重要,而個案管理在政府、法律和醫療保健行業則變得越來越關鍵。整體趨勢是,買家現在期望內容系統不僅作為獨立的儲存庫,而且還能支援審核路徑、保留邏輯、AI驅動的搜尋以及提高團隊間的可見度。 IBM的「2025 MCP Server」預覽版體現了這個發展方向,它將AI模型與文件和元資料操作結合,幫助將儲存的內容轉換為可操作的工作流程輸入。
預計到2025年,雲端運算在中國企業內容管理(ECM)市場將佔據71.28%的佔有率,並在2031年之前以17.31%的複合年成長率成長。這表明雲端運算的採用尚未進入成熟的替代週期,而仍處於積極的擴張階段。買家選擇雲端運算的原因在於,它可以縮短部署時間、簡化更新流程,並提高分散式團隊的存取權限。雲端運算在中國企業內容管理(ECM)市場的主導地位也反映出,許多新的雲端運算採用並非出於對基礎設施所有權的偏好,而是源自於數位化工作流程的目標。
需求趨勢遠比簡單地從本地基礎設施遷移複雜得多。許多敏感行業的公司選擇本地託管或託管雲端模式,以支援對存取和資料流進行更嚴格的管治。同時,對於需要將敏感記錄與大量協作內容分開的組織而言,混合部署仍然是至關重要的選擇。對於國營企業、政府機構和安全敏感型組織而言,本地環境仍佔據重要地位,因為實體隔離和內部控制是其採購的核心。全球供應商正在以主權和合規性為重點的部署策略來應對這一需求,而本地供應商則利用國內技術堆疊來降低可靠性障礙。 2025年7月,廣西壯族自治區與華為共同開發的智慧歸檔平台獲得了昇騰人工智慧和鯕鵬920架構的兼容性認證。這顯示基礎設施在地化與內容平台檢驗之間的關聯日益緊密。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 中國企業向數位化檔案的轉型正在加速。
- 人工智慧驅動的內容分類與搜尋效率
- 雲端優先企業軟體採購
- 關於可審計資訊保存的監管要求
- 用於處理大量文件的工作流程自動化
- 與ERP、CRM和案例管理系統進行跨平台整合。
- 市場限制因素
- 複雜的本地化和資料居住需求
- 傳統文件庫的高轉換成本
- 網路安全和機密資料外洩風險
- 中型企業購買意願的差異
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按解決方案類型
- 文件管理
- 記錄管理
- 工作流程和業務流程管理
- 個案管理
- 數位資產管理
- 網站內容管理
- 其他解決方案
- 部署模式
- 現場
- 雲
- 混合
- 按公司規模
- 小型企業
- 大公司
- 按最終用戶行業分類
- BFSI
- 政府/公共部門
- 衛生保健
- 資訊科技/通訊
- 製造業
- 零售
- 媒體與娛樂
- 教育
- 能源公用事業
- 其他終端用戶產業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software, Inc.
- Box, Inc.
- Oracle Corporation
- SAP SE
- Adobe Inc.
- Newgen Software Technologies Limited
- Laserfiche Inc.
- M-Files, Inc.
- DocuWare GmbH
- Alfresco Software, Inc.
- Tencent Cloud
- Yonyou Network Technology
- Alibaba Cloud
- Kingsoft Office Software
- Tungsten Automation Corporation
- Xerox Holdings Corporation
- Zoho Corporation Private Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the China enterprise content management (ECM) market size is projected to be USD 3.43 billion in 2025, USD 3.88 billion in 2026, and reach USD 7.58 billion by 2031, growing at a CAGR of 14.33% from 2026 to 2031.
This report is Segmented by Solution Type (Document Management, Records Management, and More), Deployment Mode (On-Premises, Cloud, and Hybrid), Enterprise Size (Small and Medium Enterprises, and Large Enterprises), and End-User Industry (BFSI, Government and Public Sector, Healthcare, and More). The Market Forecasts are Provided in Terms of Value (USD).
China Enterprise Content Management (ECM) Market Trends and Insights
Accelerating Digital Records Migration in Chinese Enterprises
Chinese enterprises still carry a large volume of paper-heavy records that limit access, slow response times, and increase retention risk. This pressure is strongest in regulated fields such as banking, energy, and pharmaceuticals, where archive volumes often stretch across many years. Migration work is therefore becoming a practical buying trigger, not just a modernization project. It also underscores the importance of capture, scanning, indexing, and metadata preparation, as these steps determine how useful digitized content will be after migration. Vendors that can pair repository control with faster ingest and better industry-specific document structures are likely to benefit as the China Enterprise Content Management (ECM) Market expands.
AI-Driven Content Classification and Retrieval Efficiency
AI is shifting the role of enterprise content systems from storage toward active decision support. Buyers now expect platforms to classify files, detect duplication, flag conflicts, and surface relevant content without long manual review cycles. WPS 365's Smart Document Library upgrade in January 2026 reported 95% duplicate-detection accuracy and 80% conflict-identification accuracy, demonstrating how content control is becoming more operational in daily work. This change matters in the China Enterprise Content Management (ECM) Market because Chinese-language business records, procurement files, and regulatory documents require robust local-language support. IBM's November 2025 preview of its Core Content Services MCP Server also showed that global vendors are linking AI models directly to content repositories, raising the bar for AI-ready information management.
Complex Localization and Data Residency Requirements
Localization remains a meaningful barrier in the China Enterprise Content Management (ECM) Market because data governance rules affect architecture, hosting, and release management. Foreign suppliers often need separate local environments, tighter data segregation, and China-specific operating practices to compete effectively. That adds cost and can slow the rollout of new features when compared with their global product cycles. Domestic vendors have a clearer path in these situations because their platforms are already aligned with local deployment expectations. The launch of the WPS Xinhua Intelligent Security Version for government office use in May 2026 highlights how fully localized stacks are being positioned as a practical advantage in sensitive environments.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-First Enterprise Software Procurement
- Regulatory Demand for Audit-Ready Information Retention
- High Switching Costs from Legacy Document Repositories
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Document Management accounted for 26.42% of the China Enterprise Content Management (ECM) Market in 2025, making it the largest solution category. It remains the starting point for many buyers because version control, central storage, and file access rules are usually the first steps in formal content governance. This leadership also reflects a common purchase path in which enterprises stabilize documents first, then move to broader retention, review, and process control. Records Management and Web Content Management usually expand after that first layer is in place, especially when compliance or publishing needs become harder to manage manually.
Workflow and Business Process Management is projected to grow at a 16.94% CAGR through 2031, making it the fastest-moving solution segment in the China Enterprise Content Management (ECM) Market. Demand is rising because enterprises want approvals, reviews, and content-based decisions to move faster across departments. Digital Asset Management and Case Management remain smaller but important layers, with Digital Asset Management gaining relevance where enterprises handle media libraries and branded files, while Case Management matters more in government, legal, and healthcare settings. The wider pattern is that buyers now expect content systems to support review paths, retention logic, AI-supported search, and better visibility across teams rather than function as stand-alone repositories. IBM's 2025 MCP Server preview reflects this direction because it links AI models with document and metadata operations, helping turn stored content into actionable workflow input.
Cloud accounted for 71.28% of the China Enterprise Content Management (ECM) Market in 2025 and is forecast to grow at a 17.31% CAGR through 2031. That combination shows that cloud adoption is still in an active expansion stage rather than a mature replacement cycle. Buyers are choosing cloud deployments because they reduce setup time, simplify updates, and enable broader access across distributed teams. The leading position of cloud in the China Enterprise Content Management (ECM) Market also reflects the fact that many new deployments are starting from digital workflow goals rather than from infrastructure ownership preferences.
The shape of demand is still more nuanced than a simple shift away from local infrastructure. Many enterprises in sensitive sectors are choosing controlled cloud models that support local hosting and tighter governance over access and data flow, while hybrid deployment remains relevant for organizations that need to separate sensitive records from broader collaboration content. On-premises environments still hold an important place in state-owned enterprises, government bodies, and security-sensitive organizations where physical isolation and internal control remain central to procurement. Global suppliers are adapting with sovereign and compliance-focused deployment strategies, while local suppliers are using domestic stacks to reduce trust barriers. In July 2025, a Guangxi smart archive platform developed with Huawei passed compatibility certifications for the Ascend AI and Kunpeng 920 architectures, demonstrating how infrastructure localization and content platform validation are increasingly linked.
Complete Report Scope:
- By Solution Type
- Document Management
- Records Management
- Workflow and Business Process Management
- Case Management
- Digital Asset Management
- Web Content Management
- Other Solutions
- By Deployment Mode
- On-Premises
- Cloud
- Hybrid
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Industry
- BFSI
- Government and Public Sector
- Healthcare
- IT and Telecommunications
- Manufacturing
- Retail
- Media and Entertainment
- Education
- Energy and Utilities
- Other End-User Industries
List of Companies Covered in this Report:
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software, Inc.
- Box, Inc.
- Oracle Corporation
- SAP SE
- Adobe Inc.
- Newgen Software Technologies Limited
- Laserfiche Inc.
- M-Files, Inc.
- DocuWare GmbH
- Alfresco Software, Inc.
- Tencent Cloud
- Yonyou Network Technology
- Alibaba Cloud
- Kingsoft Office Software
- Tungsten Automation Corporation
- Xerox Holdings Corporation
- Zoho Corporation Private Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Digital Records Migration in Chinese Enterprises
- 4.2.2 AI-Driven Content Classification and Retrieval Efficiency
- 4.2.3 Cloud-First Enterprise Software Procurement
- 4.2.4 Regulatory Demand for Audit-Ready Information Retention
- 4.2.5 Workflow Automation for High-Volume Document Operations
- 4.2.6 Cross-Platform Integration With ERP, CRM, and Case Systems
- 4.3 Market Restraints
- 4.3.1 Complex Localization and Data Residency Requirements
- 4.3.2 High Switching Costs From Legacy Document Repositories
- 4.3.3 Cybersecurity and Sensitive Data Exposure Risks
- 4.3.4 Fragmented Buyer Readiness Across Mid-Market Enterprises
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution Type
- 5.1.1 Document Management
- 5.1.2 Records Management
- 5.1.3 Workflow and Business Process Management
- 5.1.4 Case Management
- 5.1.5 Digital Asset Management
- 5.1.6 Web Content Management
- 5.1.7 Other Solutions
- 5.2 By Deployment Mode
- 5.2.1 On-Premises
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 Government and Public Sector
- 5.4.3 Healthcare
- 5.4.4 IT and Telecommunications
- 5.4.5 Manufacturing
- 5.4.6 Retail
- 5.4.7 Media and Entertainment
- 5.4.8 Education
- 5.4.9 Energy and Utilities
- 5.4.10 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 OpenText Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Hyland Software, Inc.
- 6.4.5 Box, Inc.
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Adobe Inc.
- 6.4.9 Newgen Software Technologies Limited
- 6.4.10 Laserfiche Inc.
- 6.4.11 M-Files, Inc.
- 6.4.12 DocuWare GmbH
- 6.4.13 Alfresco Software, Inc.
- 6.4.14 Tencent Cloud
- 6.4.15 Yonyou Network Technology
- 6.4.16 Alibaba Cloud
- 6.4.17 Kingsoft Office Software
- 6.4.18 Tungsten Automation Corporation
- 6.4.19 Xerox Holdings Corporation
- 6.4.20 Zoho Corporation Private Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 企業架構服務市場:全球市場預測,2026-2032年
 新加坡企業內容管理 (ECM):市佔率分析、產業趨勢與統計及成長預測 (2026-2031)美國企業內容管理 (ECM):市場佔有率分析、行業趨勢和統計數據以及成長預測 (2026-2031)義大利企業內容管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)西班牙企業內容管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)企業內容管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)基於雲端的企業內容管理市場-2026年至2032年全球市場預測雲端的企業內容管理:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 Frost Radar™:數位媒體內容安全與反派餅服務,2026 年企業內容管理市場-2026-2032年全球市場預測