


 |
市場調查報告書
商品編碼
2117421
西班牙礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Spain Mining Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
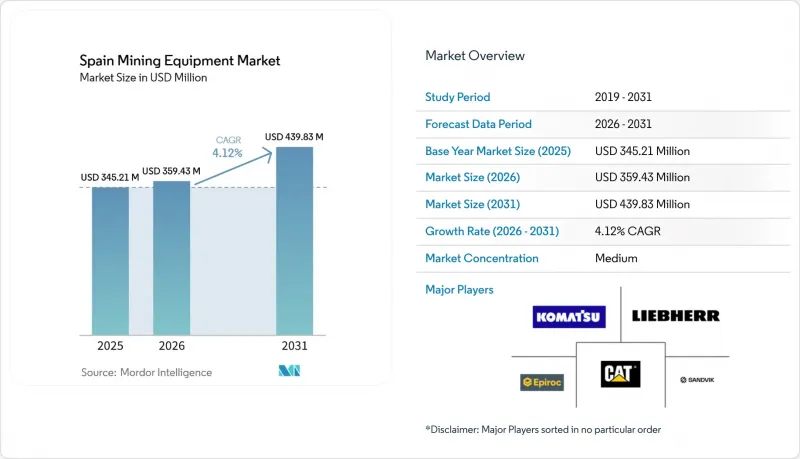
據 Mordor Intelligence 稱,西班牙採礦機械市場在 2025 年的價值為 3.4521 億美元,預計到 2031 年將達到 4.3983 億美元,而 2026 年為 3.5943 億美元,預測期內(2026-2031 年)的複合年成長率預計為 4.12%預計為 4.12%。
本報告按機器類型(露天採礦機械、地下採礦機械等)、自動化程度(手動、半自動等)、動力傳動系統類型(內燃機、電池電動等)、功率輸出(500馬力以下、500-1000馬力、1000馬力以上)和應用領域(金屬礦開採、煤礦開採、煤礦開採)進行分類。市場預測以美元計價。
西班牙礦業機械市場趨勢與洞察
歐盟的關鍵原物料政策刺激了國內礦業投資。
西班牙作為歐盟「戰略供應商」的地位刺激了對露天鑽探設備、運輸車輛和現場加工廠的投資。根據《基本原物料法》,目前有七個西班牙項目被指定為“戰略項目”,這縮短了獲得許可的前置作業時間,並將歐盟資金用於設備密集型開發項目。坎波德蒙蒂爾(Campo de Montiel)和埃爾莫托(El Moto)是這些計劃的核心,分別需要大容量鑽探設備、100噸卡車和可快速在相鄰礦床之間重新部署的模組化選礦廠。政府各部門正在將地質調查經費納入國家預算,以鼓勵對以前未開發的富鋰偉晶岩和鎢矽卡岩進行投資。因此,歐盟的自給自足目標與國內經濟政策一致,恢復了人們對該產業的信心。這提高了金融機構的貸款意願,並縮小了購買高規格設備的資金籌措差距。
可再生能源主導的金屬繁榮(鋰、銅、錫)正在擴大對設備的需求。
屋頂太陽能發電廠、大型儲能電池和離岸風力發電電場保障了未來幾十年對銅和鋰的需求,投資正集中在西班牙的伊比利亞黃鐵礦帶和弗洛雷斯山谷。承包商使用高空電動挖土機和符合Tier 4排放標準的裝載機,在不超出區域顆粒物排放標準的前提下,剝離鋰偉晶岩上方的風化層。新的礦石加工廠整合了乾式尾礦處理和礦石分選模組,顯著減少了用水量,這對於易受乾旱影響的安達盧西亞地區的採購至關重要。國際能源總署(IEA)預測,到2050年,鋰需求將成長十倍,這推動了西班牙採礦設備市場的發展,帶動了先進中壓電纜捲筒和汽車逆變器櫃期貨合約的交易。
漫長的授權程序和當地居民的強烈環保反對。
複雜的多階段核准程序和活躍的維權團體正在延遲專案進度,延長供應商前置作業時間,並增加庫存持有成本。博利登礦難的餘波持續影響公眾輿論,要求進行嚴格的基準調查和多部門聯合審查。地方政府擁有推翻國家批准的自由裁量權,迫使礦業公司在設備訂單獲得董事會批准前,必須與當地社區進行漫長的宣傳活動。作為應對措施,供應商正在歐洲的物流中心囤積前置作業時間長的零件,例如選礦廠殼體和挖土機機身,以便在獲得批准後縮短交貨時間。儘管近期訂定的《基本原料法》已引入了加速核准的措施,但程序性異議仍然頻繁出現,限制了西班牙礦業機械市場的短期成長潛力。
細分市場分析
儘管露天採礦在2025年佔銷售額的45.27%,但隨著卡塞雷斯鋰礦和韋爾瓦多金屬礦開採業務的擴張,預計到2031年,裝載機和運輸卡車的複合年成長率將達到7.46%。隨著礦床從露天礦層向更深層轉移,對通風設備、窄脈裝載機和膏體充填鑽機的需求激增,擴大了地下採礦設備的市場佔有率。在全國範圍內,由於基於感測器的分類機,已部署多台TOMRA分選機的Valeccopardo公司成功地大幅提高了其對重力選礦迴路的供應量。在格蘭加納利島銷售的Epiroc HB 4100利用了採石場的跨訂單趨勢,凸顯了鑽孔機和破碎機的穩定性。
機械設計越來越注重整合化車隊。例如,Cat 6015挖土機現已針對與Cat 773-777卡車的協同作業進行了最佳化,從而確保高效的作業循環時間。同時,配備牽引力控制系統和液氣懸吊系統的日本小松公司 HM460-6挖土機,能夠有效抑制西班牙鬆軟表層土壤中的車輪打滑。在西班牙礦山機械市場,MineStar、Smart Quarry和Micromine Pitram等開放式遠端資訊處理系統在性能上超越了獨立的動力解決方案,凸顯了互通性作為關鍵採購標準的重要性日益凸顯。
儘管到2025年,手動操作設備仍佔銷售額的68.28%,但受勞動力短缺和MATSA試點計畫成功的推動,自動駕駛設備正以8.43%的複合年成長率快速成長。半自動駕駛和遠端採礦等過渡性技術在有效利用現有重型機械的同時,降低了操作人員面臨的危險。 「X MINERGY」爆炸裝載原型機正朝著現場檢驗的方向發展,預示著遠端地面設備的廣泛應用。基礎設施投資發揮著至關重要的作用。 MATSA的綜合光纖Wi-Fi網路正在強化其互通性策略,目前該模式已被西班牙礦業機械市場伊比利亞黃鐵礦帶的其他營運商所採用。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟促進關鍵原料的政策正在刺激國內採礦投資。
- 為了提高安全性和生產效率,對自動化和遠端操作的需求正在激增。
- 可再生能源(鋰、銅、錫)主導的金屬繁榮正在擴大對設備的需求。
- 政府對大型移動機械低排放動力傳動系統的獎勵措施
- 模組化微型採礦機器人示範計畫(ROBOMINERS、OMEE 計畫)正在加速資本投資。
- 基於績效的維護合約正在加速設備更換週期。
- 市場限制因素
- 獲得許可的過程被延長了,當地居民出於環境方面的考慮,對此表示強烈反對。
- 新冠疫情後資本支出(Cap-Ex)膨脹和零件供應鏈中斷
- 安達盧西亞和埃斯特雷馬杜拉地區因水資源緊張而限制礦場擴張
- 缺乏具備自動駕駛技術技能的工程師,導致礦場營運成本(OPEX)上升。
- 價值鍊和供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章:預測市場規模與成長率
- 按機器類型
- 露天採礦機械
- 地下採礦機械
- 礦物加工設備
- 鑽頭破碎機
- 破碎、研磨與分類機
- 裝載機/運輸卡車
- 按自動化級別
- 手動機器
- 半自動機器
- 全自動機器
- 依動力傳動系統類型
- 內燃機
- 電池供電
- 混合
- 依輸出類型
- 低於500馬力
- 500~1,000 HP
- 1000馬力或以上
- 透過使用
- 金屬礦開採
- 礦產開採
- 採煤
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- Komatsu Ltd.
- Liebherr-International AG
- Sandvik AB
- Epiroc AB
- Volvo Construction Equipment
- Hitachi Construction Machinery
- Atlas Copco AB
- Metso Corporation
- Terex Corporation
- Doosan Infracore
- Sany Heavy Industry
- XCMG Group
- JCB Ltd.
- CNH Industrial(Case CE)
- Aramine(Groupe Melkonian SAS)
第7章 市場機會與未來展望
According to Mordor Intelligence, the Spain mining equipment market size was valued at USD 345.21 million in 2025 and is estimated to grow from USD 359.43 million in 2026 to reach USD 439.83 million by 2031, at a CAGR of 4.12% during the forecast period (2026-2031).
This report is Segmented by Equipment Type (Surface Mining Equipment, Underground Mining Equipment and More), Automation Level (Manual, Semi-Autonomous and More), Powertrain Type (ICE, Battery-Electric and More), Power Output (Less Than 500 HP, 500-1, 000 HP and Above 1, 000 HP), Application (Metal Mining, Mineral Mining and Coal Mining). The Market Forecasts are Provided in Terms of Value (USD).
Spain Mining Equipment Market Trends and Insights
EU Critical Raw Materials Push Revives Domestic Mining Investments
Spain's elevation to strategic supplier status inside the EU has ignited spending on surface drills, haulage fleets, and on-site processing plants. Seven Spanish projects are now named "Strategic" under the Critical Raw Materials Act, a designation that cuts permitting lead times and channels EU capital toward equipment-intensive developments. Campo de Montiel and El Moto headline the pipeline, each demanding high-capacity excavators, 100-t trucks, and modular concentrators capable of rapid redeployment across adjacent deposits. Ministries have embedded geological mapping funds into the national budget, guiding investors to lithium-rich pegmatites and tungsten skarns that previously lay idle. The resulting alignment between EU autonomy targets and domestic economic policy has restored industry credibility, boosting lender appetite and compressing financing spreads for high-specification equipment acquisitions.
Renewables-Led Metals Boom (Lithium, Copper, Tin) Expanding Equipment Demand
Rooftop-solar installs, grid-scale batteries, and offshore wind arrays lock in multi-decade demand for copper and lithium, funneling investment toward Spain's Iberian Pyrite Belt and Valdeflores Valley. Contractors mobilize high-reach electric shovels and Tier 4-compliant loaders to strip saprolite horizons above lithium pegmatites without breaching local particulate matter limits. New concentrators integrate dry-stack tailings and ore-sorting modules, significantly curbing water use-a decisive procurement attribute in drought-prone Andalusia. International Energy Agency scenarios projecting a tenfold spike in lithium by 2050 underpin forward contracts for advanced reels of medium-voltage cable and on-board inverter cabinets, stimulating the Spain mining equipment market.
Lengthy Permitting and Strong Local Environmental Opposition
Complex multi-tier authorizations and vocal activist groups delay project timelines, extending supplier lead-times and elevating inventory-carry costs. The Boliden spill legacy still shapes public sentiment, driving rigorous baseline studies and multi-agency reviews. Municipal councils wield discretionary powers that can override national approvals, prompting miners to run protracted community-engagement campaigns before equipment orders gain board sign-off. Suppliers respond by staging long-lead components-such as mill shells and shovel car-bodies-in European hubs to compress delivery once permits clear. Even with recent Critical Raw Materials Act fast-track provisions, procedural appeals remain frequent, tempering immediate upside for the Spain mining equipment market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Automation and Remote-Operation Demand to Improve Safety / Productivity
- Government Incentives for Low-Emission Powertrains in Heavy Mobile Machinery
- Water-Stress Restrictions on Andalusian and Extremaduran Mine Expansions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Surface units retained 45.27% of 2025 revenue, yet loaders and haul trucks are on track for a 7.46% CAGR to 2031 as lithium pits in Caceres and polymetallic cut-backs in Huelva scale up. As deposits shift from open-pit to deeper levels, the demand for ventilation, narrow-vein loaders, and paste-fill rigs has surged, leading to a growing share for underground fleets. Nationwide, several TOMRA machines have already enabled Barruecopardo to boost its feed to gravity circuits by a significant percentage, thanks to sensor-based sorters. Epiroc's HB 4100, sold in Gran Canaria, underscores the stability of drills and breakers, benefiting from cross-ordering trends in quarrying.
Equipment design is increasingly favoring integrated fleets. For instance, the Cat 6015 shovel is now optimized to work in tandem with Cat 773-777 trucks, ensuring efficient cycle times. Meanwhile, Komatsu's HM460-6, equipped with traction control and hydro-pneumatic suspension, effectively mitigates tire spin on Spain's softer overburden. In the Spanish mining equipment market, open telematics systems such as MineStar, Smart Quarry, and Micromine Pitram have outpaced standalone horsepower solutions, underscoring the growing emphasis on interoperability as a key purchasing criterion.
Manual units still accounted for 68.28% of 2025 turnover, but autonomy is expanding at an 8.43% CAGR, driven by labor scarcity and successful pilots at MATSA. Transitional technologies like semi-autonomous tramming and teleremote mucking are reducing operator exposure while still valuing legacy iron. The X MINERGY explosives-loading prototype is progressing toward field validation, heralding a wider embrace of teleoperated surface equipment. Infrastructure investment plays a pivotal role: MATSA's comprehensive fiber WiFi network bolsters its interoperability strategy, a model now being adopted by other operators in the Iberian Pyrite Belt within Spain's mining equipment market.
Complete Report Scope:
- By Equipment Type
- Surface Mining Equipment
- Underground Mining Equipment
- Mineral Processing Equipment
- Drills & Breakers
- Crushing, Pulverizing & Screening
- Loaders & Haul Trucks
- By Automation Level
- Manual Equipment
- Semi-Autonomous Equipment
- Fully Autonomous Equipment
- By Powertrain Type
- Internal-Combustion Engine Vehicles
- Battery-Electric Vehicles
- Hybrid Vehicles
- By Power Output
- Less than 500 HP
- 500 - 1,000 HP
- Above 1,000 HP
- By Application
- Metal Mining
- Mineral Mining
- Coal Mining
List of Companies Covered in this Report:
- Caterpillar Inc.
- Komatsu Ltd.
- Liebherr-International AG
- Sandvik AB
- Epiroc AB
- Volvo Construction Equipment
- Hitachi Construction Machinery
- Atlas Copco AB
- Metso Corporation
- Terex Corporation
- Doosan Infracore
- Sany Heavy Industry
- XCMG Group
- JCB Ltd.
- CNH Industrial (Case CE)
- Aramine ( Groupe Melkonian SAS)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Critical Raw Materials Push Revives Domestic Mining Investments
- 4.2.2 Surge In Automation and Remote-Operation Demand to Improve Safety / Productivity
- 4.2.3 Renewables-Led Metals Boom (Lithium, Copper, Tin) Expanding Equipment Demand
- 4.2.4 Government Incentives for Low-Emission Powertrains in Heavy Mobile Machinery
- 4.2.5 Modular Micro-Mine Robotics Pilots (ROBOMINERS, OMEE Projects) Accelerating Capex
- 4.2.6 Performance-Based Maintenance Contracts Boosting Equipment Replacement Cycles
- 4.3 Market Restraints
- 4.3.1 Lengthy Permitting and Strong Local Environmental Opposition
- 4.3.2 Cap-Ex Inflation and Component Supply-Chain Disruption Post-COVID
- 4.3.3 Water-Stress Restrictions on Andalusian and Extremaduran Mine Expansions
- 4.3.4 Shortage of Autonomy-Skilled Technicians Raising OPEX for Mines
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Equipment Type
- 5.1.1 Surface Mining Equipment
- 5.1.2 Underground Mining Equipment
- 5.1.3 Mineral Processing Equipment
- 5.1.4 Drills & Breakers
- 5.1.5 Crushing, Pulverizing & Screening
- 5.1.6 Loaders & Haul Trucks
- 5.2 By Automation Level
- 5.2.1 Manual Equipment
- 5.2.2 Semi-Autonomous Equipment
- 5.2.3 Fully Autonomous Equipment
- 5.3 By Powertrain Type
- 5.3.1 Internal-Combustion Engine Vehicles
- 5.3.2 Battery-Electric Vehicles
- 5.3.3 Hybrid Vehicles
- 5.4 By Power Output
- 5.4.1 Less than 500 HP
- 5.4.2 500 - 1,000 HP
- 5.4.3 Above 1,000 HP
- 5.5 By Application
- 5.5.1 Metal Mining
- 5.5.2 Mineral Mining
- 5.5.3 Coal Mining
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Liebherr-International AG
- 6.4.4 Sandvik AB
- 6.4.5 Epiroc AB
- 6.4.6 Volvo Construction Equipment
- 6.4.7 Hitachi Construction Machinery
- 6.4.8 Atlas Copco AB
- 6.4.9 Metso Corporation
- 6.4.10 Terex Corporation
- 6.4.11 Doosan Infracore
- 6.4.12 Sany Heavy Industry
- 6.4.13 XCMG Group
- 6.4.14 JCB Ltd.
- 6.4.15 CNH Industrial (Case CE)
- 6.4.16 Aramine ( Groupe Melkonian SAS)
7 Market Opportunities & Future Outlook

 中國礦山機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)印度礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)德國礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)非洲礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)馬來西亞礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)日本礦業機械:市場佔有率分析、產業趨勢及統計、成長預測(2026-2031)法國礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)英國礦業機械:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 礦業機械市場報告:趨勢、預測與競爭分析(至2035年)
 自主採礦機械市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。