


 |
市場調查報告書
商品編碼
2163476
3D牆板壁紙:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)3D Wall Panel Wallpaper - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,3D 牆板壁紙市場規模預計在 2025 年達到 7.4328 億美元,在 2026 年達到 7.9286 億美元,在 2031 年達到 10.9734 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 6.72%。
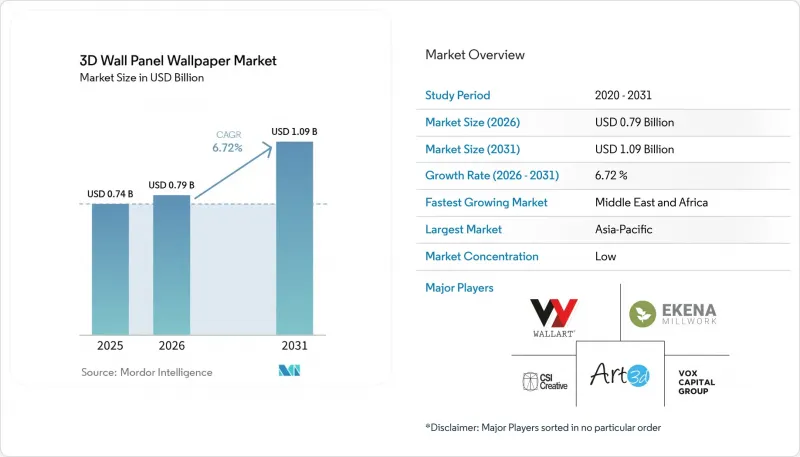
全球3D牆板及壁紙市場趨勢及洞察
翻新和整修的需求支撐著需求基礎。
隨著房屋翻新支出轉向可見的室內升級,3D牆板和壁紙市場將受益。哈佛大學根據美國住宅調查修訂後的基準,到2025年,美國住宅維修改造市場規模將達到5,090億美元,比先前的預測高出300億美元。如此龐大的支出基礎支撐著無需徹底重新設計即可改變房間氛圍的牆面裝飾。特色牆和獨特的表面裝飾為住宅提供了以設計為導向的替代方案,無需進行大規模的結構改造。這些選擇縮短了裝飾性飾面的決策週期,並刺激了更換需求。在歐洲,居住住宅和商業建築的維修很可能涉及相關表面材料的更換。 「建築能源性能指令」正在為整個歐洲建築存量進行更徹底的維修道路。因此,3D牆板和壁紙市場的需求不僅來自可選的裝飾,也與維修計劃息息相關。
數位印刷和設計客製化拓展了選擇範圍。
數位印刷技術正在拓展3D牆板壁紙市場的飾面選擇範圍。大尺寸印刷設備使得以往傳統生產方式無法實現的小規模製訂單成為可能。設計師可以指定更多紋理、顏色和圖案選項,而無需完全依賴大規模標準生產。這正在改變競爭格局,如今,除了工廠規模之外,設計廣度和訂單處理速度也至關重要。數位化配置工具和擴增實境(AR)視覺化技術可以幫助客戶在購買前預覽牆面飾面效果。這些工具還可以改善設計師、零售商、安裝人員和最終用戶之間的溝通。環保溶劑型、乳膠型和UV固化型油墨系統透過滿足耐用性和室內空氣品質要求,為此變革提供了支持。因此,獨立設計師和注重生活方式的消費者能夠更方便地獲得客製化的表面解決方案。
遵守消防安全和建築規範的成本限制了其商業用途。
符合防火安全標準可能會限制3D牆板壁紙進入商業項目市場。在美國,商業牆面和天花板裝飾材料必須符合基於國際建築標準(IBC)框架的ASTM E84阻燃和排煙要求。達到A級性能標準要求阻燃指數不超過25,排煙指數不超過450。為達到這些標準,可能需要對每種產品配置進行阻燃處理、實驗室測試並提供相關文件。根據顏色變化和麵板結構的不同,可能需要提供個別產品的證據,而不是依賴同一系列的其他產品。歐洲的參與企業也必須符合歐洲等級(Euroclass)要求和相關的測試框架。歐盟建築產品法規的實施加強了對建築產品安全性和永續性的監管。這些要求可能會加重小規模生產商的負擔,並將商業通路的准入集中在大型供應商手中。
細分市場分析
到2025年,PVC和乙烯基材料將佔據3D牆板壁紙市場33.8%的佔有率,成為領先的材料類別。這一地位反映了其尺寸穩定性、防潮性、可塗漆性和成本效益。由於其特性熟悉,PVC和乙烯基產品仍然是各種住宅和商業應用的實用之選。然而,隨著塑化劑和排放物相關文件影響產品選擇,這類材料將受到更嚴格的審查。在義大利,TVOC(總揮發性有機化合物)的閾值已收緊,並且對低揮發性材料設有評估標準,這可能導致商業規範中優先考慮替代配方[3]。這可能會促使製造商投資於低揮發性配方的開發、測試和更清晰的環境文件編制。聚氨酯板材在注重柔軟表面和複雜設計的領域仍保持著高階地位。木材、中密度纖維板(MDF)和高密度纖維板(HDF)產品也受益於人們對木紋飾面和親生物室內設計的日益成長的興趣。
纖維水泥板和金屬板主要用於一些特殊應用,例如高濕度商業環境以及室內外觀。石膏和灰泥在安裝人員經驗豐富且成本效益高的場合中仍然發揮著重要作用。植物纖維和甘蔗渣(甘蔗殘渣)是成長最快的材料類別,預計到2031年複合年成長率將達到7.6%。植物纖維和甘蔗渣3D牆板和壁紙的市場規模有望受益於低VOC和生物基表面材料的需求。對甘蔗渣吸音板的研究表明,其在1500-1600 Hz頻率下的吸聲係數高達0.98,且無需使用合成樹脂即可達到B-s1,d0級防火標準。這使得甘蔗渣基板材成為對聲學和排放氣體有要求的項目中的可靠選擇。然而,要使這一類別的產品在專業規範之外得到廣泛應用,仍需要穩定的供應、一致的產品品質和完善的專案文件。
到2025年,卡扣式/互鎖式系統將佔據3D牆板市場47.3%的佔有率。當牆板的對齊性和長期結構可靠性至關重要時,承包商和商業建築規範制定者會採用這些系統。這種方法適用於商業建築和承包商主導的住宅專案的專業安裝,也適用於需要牢固固定的重型牆板。由於能夠處理不規則的牆面,黏合劑式產品在中檔住宅建築中仍然很常見。機械緊固和砂漿/水泥基底安裝方式在重型牆板、潮濕環境以及需要高荷載的應用中仍扮演著重要角色。所有這些安裝方法都依賴基材的準備和承包商的技能。因此,對於此類應用而言,專業安裝仍然至關重要。
自黏和即撕即貼產品預計到2031年將以8.3%的複合年成長率成長,成為所有安裝方式中成長最快的。此類3D牆板和壁紙市場規模的成長主要受便利安裝需求的驅動。艾利丹尼森在美國進行的一項調查顯示,人們對使用即撕即貼牆面解決方案的興趣普遍較高,尤其是在千禧世代和Z世代受訪者中。可重新定位、低VOC和防潮的黏合劑使這些系統適用於更廣泛的室內環境。這些特性可能會吸引那些尋求可逆個人化裝飾的居住者和都市區家庭。隨著黏合劑性能的提升,它們也可能應用於一些商業領域。因此,產品組合正朝著減少人工依賴的設計方向發展,創新重點在於提高黏合劑的品質和與基材的兼容性。
區域分析
到2025年,亞太地區將佔據3D牆板和壁紙市場34.8%的佔有率。該地區的市場成長主要得益於室內材料的大規模生產,以及住宅建設活動和不斷成長的翻新需求。在中國,現有公寓的維修支撐了市場需求;而在印度,都市區住宅開發催生了早期室內裝修需求。東南亞則透過公寓和酒店設施的建設推動了市場成長。日本和韓國是成熟的市場,擁有完善的設計標準和性能規範,不僅支撐著對基礎裝飾產品的需求,也支撐著對高附加價值吸音材料和性能卓越的表面材料的需求。
歐洲市場受建築法規和政策的影響。 《建築能源性能指令 (EPBD)》支援包括牆體和天花板維修在內的維修項目,而《建築產品法規 (CPR)》則強調生命週期和產品性能文件的重要性。德國、法國、英國和比荷盧經濟聯盟是低排放材料的主要市場。在義大利,CAM Edilizia計劃於2026年收緊TVOC(總揮發性有機化合物)的限制,這表明市場偏好正在轉變。北美也受益於許多因素,例如強勁的維修支出、對低碳室內產品的需求、消防安全標準的合規要求、DIY的興起以及商業維修活動的活躍。
預計到2031年,中東和非洲地區的複合年成長率將達到8.5%,為所有地區中最高的成長率。大規模房地產和基礎設施項目,特別是海灣國家商業和酒店設施的開發,支撐了這一成長前景。杜拜、阿布達比和沙烏地阿拉伯的「2030願景」項目,包括NEOM、Diriya和New Muraba,正在推動高階室內建築材料的需求。南非和奈及利亞正在湧現新的商機,而南美洲預計將透過對輕型建築系統和石膏板生產能力的投資實現長期成長。供應商需要根據當地的建築能力、建築規範、氣候條件和分銷網路調整其產品,這使得製造商在提供耐用產品、培訓、本地支援和清晰的性能資訊方面具有優勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 房屋翻新改造的需求
- 數位印刷和設計客製化
- 飯店與體驗式商業室內設計
- 永續且低VOC的室內建築材料
- 「即撕即貼」與DIY安裝方式的普及
- 將聲學性能融入裝飾表面
- 市場限制因素
- 與遵守消防和建築規範相關的費用。
- 原物料價格和供應的波動
- 與施工品質和基材準備相關的風險
- 多層板材和壁紙丟棄後,回收受到限制。
- 產業價值鏈分析
- 波特五力分析
- 深入了解產業最新趨勢與創新
- 近期產業趨勢分析(新產品發布、策略性舉措、投資、合作、合資、業務擴張、併購等)
- 深入了解消費者對設計和表面圖案的偏好
第5章 市場規模與成長預測
- 材料
- 聚氯乙烯和乙烯基
- 聚氨酯
- 天然木材、中密度纖維板、高密度纖維板
- 石膏
- 纖維水泥
- 植物纖維和甘蔗渣
- 金屬
- 其他材料
- 透過安裝方法
- 黏合劑類型
- 機械固定
- 卡扣/互鎖
- 砂漿/水泥基建築
- 背膠型/即撕即貼
- 最終用戶
- 住宅
- 商業的
- 透過分銷管道
- B2C通路
- 大賣場和超級市場
- 專賣店
- 家居建材商店
- 線上
- 當地金屬製品
- 其他分銷管道
- B2B通路(承包商、建築商、室內設計師、建築師、專案採購和機構銷售)
- B2C通路
- 按地區
- 北美洲
- 加拿大
- 美國
- 墨西哥
- 南美洲
- 巴西
- 秘魯
- 智利
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 比荷盧經濟聯盟(比利時、荷蘭、盧森堡)
- 北歐國家(丹麥、芬蘭、冰島、挪威、瑞典)
- 其他歐洲國家
- 亞太地區
- 印度
- 中國
- 日本
- 澳洲
- 韓國
- 東南亞
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 奈及利亞
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度概述
- 策略趨勢
- 市佔率分析
- 公司簡介
- Art3d
- Ekena Millwork
- WallArt
- CSI Creative
- Profile VOX
- MyWallArt
- Greenmood
- Fibo AS
- Arte International
- Saint-Gobain SA
- Armstrong World Industries, Inc.
- Knauf Group
- Nichiha Corporation
- LIXIL Corporation
- Arktura
- Vicoustic
- Trespa International BV
- EGGER Group
- Kingspan Group plc
第7章 市場機會與未來展望
According to Mordor Intelligence, the 3D wall panel wallpaper market was valued at USD 743.28 million in 2025, is estimated at USD 792.86 million in 2026, and is forecast to reach USD 1,097.34 million by 2031, growing at a 6.72% CAGR during 2026-2031.
Global 3D Wall Panel Wallpaper Market Trends and Insights
Renovation and Remodeling Demand Anchors a Structural Demand Base
The 3D wall panel wallpaper market benefits when renovation spending shifts toward visible interior upgrades. Harvard University projected the United States home improvement and repair market at USD 509 billion in 2025, USD 30 billion above its earlier outlook after a revised American Housing Survey baseline. This spending base supports wall treatments that can alter a room without a full redesign. Accent walls and feature surfaces can offer homeowners a design-led alternative to larger structural projects. That choice can shorten the decision cycle for decorative finishes and support replacement demand. In Europe, building renovation programs can create related surface replacement work when upgrades involve occupied homes and commercial properties. The Energy Performance of Buildings Directive creates a pathway for deeper renovation across the European building stock. The 3D wall panel wallpaper market, therefore, has demand linked to refurbishment schedules as well as discretionary decoration.
Digital Printing and Design Customization Expand Design Choice
Digital printing is widening the range of finishing available in the 3D wall panel wallpaper market. Large-format equipment can support smaller custom orders that were less practical under conventional production methods. Designers can specify more texture, color, and pattern options without relying only on large standard runs. This changes competition because design range and order speed can matter alongside factory scale. Digital configuration tools and augmented reality visualization can help customers assess a wall treatment before purchase. These tools can also improve communication between designers, retailers, installers, and end users. Eco-solvent, latex, and UV-curable ink systems support the shift by addressing durability and indoor air quality requirements. The result is broader access to customized surface solutions for independent designers and lifestyle-focused consumers.
Fire-Safety and Building-Code Compliance Costs Limit Commercial Access
Fire-safety compliance can restrict access to commercial projects in the 3D wall panel wallpaper market. United States commercial wall and ceiling finishes must meet ASTM E84 flame-spread and smoke-development requirements under the International Building Code framework. Class A performance requires a flame spread index of 25 or below and a smoke developed index of 450 or below. Achieving this result can require fire-retardant treatment, laboratory testing, and documentation for each relevant product configuration. A colorway or panel construction may need separate evidence rather than relying on another product in the same range. European entrants must also address Euroclass requirements and related test frameworks. The European Union's Construction Products Regulation entered into force with stronger safety and sustainability provisions for construction products. These requirements increase the burden on smaller producers and can concentrate commercial channel access among larger suppliers.
Other drivers and restraints analyzed in the detailed report include:
- Hospitality and Commercial Interior Upgrades Support Project Specifications
- Sustainable Materials and Easier Installation Broaden Adoption
- Raw Material Volatility and Product Life-Cycle Limits Pressure Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PVC and Vinyl held 33.8% of the 3D wall panel wallpaper market share in 2025, making it the leading material category. Its position reflects dimensional stability, moisture resistance, paintability, and cost-effective production. PVC and Vinyl products can remain practical for broad residential and commercial use because they offer familiar handling characteristics. However, the material faces greater scrutiny where plasticizers and emissions documentation affect selection. Italy's tighter TVOC threshold and low-emitting material credits can favor alternative formulations in commercial specifications[3]. This can lead manufacturers to invest in lower-emission formulations, testing, and clearer environmental documentation. Polyurethane panels retain a premium position where a softer surface and detailed design are valued. Wood, MDF, and HDF products also benefit from interest in wood-grain finishes and biophilic interior design.
Fiber Cement and Metal panels serve more specialized uses, including humid commercial environments and exterior-interior facade applications. Gypsum and plaster remain relevant where labor familiarity and cost efficiency are important. Plant Fiber and bagasse represent the fastest-growing material category, with a forecast CAGR of 7.6% through 2031. The 3D wall panel wallpaper market size for plant fiber and bagasse can benefit from demand for low-VOC and bio-based surfaces. Research described for sugarcane bagasse acoustic boards reported sound absorption coefficients up to 0.98 at 1,500 to 1,600 Hz and Class B-s1,d0 fire performance without synthetic resins. This makes bagasse-based panels a credible option in acoustic and emissions-sensitive projects. The category still needs reliable supply, product consistency, and project documentation to scale beyond specialized specifications.
Clip/Interlocking systems accounted for 47.3% of the 3D wall panel wallpaper market share in 2025. Contractors and commercial specifiers use these systems where panel alignment and long-term structural reliability are important. The method suits professional installation in commercial properties and contractor-led residential projects. It can also support heavy panels that need a secure fixing approach. Adhesive-mounted products remain common in mid-range residential work because they can suit irregular walls. Mechanical fixing and mortar or cement-based installation remain relevant for heavy panels and wet or high-load applications. Each of these formats depends on substrate preparation and installer skill. This keeps professional installation important across much of the category.
Self-Adhesive and Peel-and-Stick products are forecast to grow at an 8.3% CAGR through 2031, the fastest rate among installation methods. The 3D wall panel wallpaper market size for this format is supported by demand for more accessible installation. Avery Dennison's United States survey found broad willingness to use peel-and-stick wall solutions, particularly among Millennial and Generation Z respondents. Repositionable, lower-VOC, and humidity-resistant adhesives can make these systems more useful in a wider set of interior conditions. These features can appeal to renters and urban households seeking reversible personalization. Some commercial uses may also become feasible as adhesive performance improves. The mix is therefore moving toward lower labor dependency, with innovation focused on adhesive quality and substrate compatibility.
Complete Report Scope:
- By Material
- PVC and Vinyl
- PU / Polyurethane
- Natural Wood, MDF, and HDF
- Gypsum/Plaster
- Fiber Cement
- Plant Fiber and Bagasse
- Metal
- Other Materials
- By Installation Method
- Adhesive-mounted
- Mechanical fixing
- Clip/interlocking
- Mortar/cement-based installation
- Self-adhesive / peel-and-stick
- By End User
- Residential
- Commercial
- By Distribution Channel
- B2C Channels
- Hypermarkets and Supermarkets
- Specialty Stores
- Home Improvement Stores
- Online
- Local Hardware Shops
- Other Distribution Channels
- B2B Channels (Contractors and Installers, Interior Designers and Architects, Project Procurement and Institutional Sales)
- B2C Channels
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia
- Rest of Asia-Pacific
- Middle East & Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East & Africa
- North America
Geography Analysis
Asia-Pacific accounted for 34.8% of the 3D wall panel wallpaper market share in 2025. The region combines substantial interior materials production with residential construction activity and growing renovation demand. China supports demand through upgrades to its existing apartment stock, while India generates first-cycle interior demand through urban housing development. Southeast Asia contributes through condominium and hospitality construction. Japan and South Korea are mature markets with established design standards and performance specifications, supporting demand for both basic decorative products and higher-value acoustic or documented surfaces.
Building regulations and renovation policies shape the European market. The Energy Performance of Buildings Directive supports renovation projects that may include wall and ceiling upgrades, while the Construction Products Regulation increases the importance of life-cycle and product-performance documentation. Germany, France, the United Kingdom, and the BENELUX countries are key specification markets for low-emission materials. Italy may signal changing preferences as CAM Edilizia will tighten the TVOC limit in 2026. North America also benefits from strong renovation spending, low-carbon interior manufacturing demand, fire-code compliance requirements, DIY adoption, and commercial renovation activity.
The Middle East and Africa are forecast to grow at an 8.5% CAGR through 2031, the highest regional growth rate. Large real estate and infrastructure projects, particularly Gulf commercial and hospitality developments, support this outlook. Dubai, Abu Dhabi, and Saudi Arabia's Vision 2030 projects, including NEOM, Diriyah, and New Murabba, create demand for premium interior materials. South Africa and Nigeria offer developing opportunities, while South America has long-term potential through investments in light construction systems and plasterboard capacity. Suppliers must adapt products to local installation capabilities, codes, climate conditions, and distribution networks, favoring manufacturers that offer durable products, training, local support, and clear performance information.
- Art3d
- Ekena Millwork
- WallArt
- CSI Creative
- Profile VOX
- MyWallArt
- Greenmood
- Fibo AS
- Arte International
- Saint-Gobain S.A.
- Armstrong World Industries, Inc.
- Knauf Group
- Nichiha Corporation
- LIXIL Corporation
- Arktura
- Vicoustic
- Trespa International B.V.
- EGGER Group
- Kingspan Group plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Renovation and Remodeling Demand
- 4.2.2 Digital Printing and Design Customization
- 4.2.3 Hospitality and Experiential Commercial Interiors
- 4.2.4 Sustainable and Low-VOC Interior Materials
- 4.2.5 Peel-and-Stick and DIY Installation Adoption
- 4.2.6 Acoustic Performance Embedded in Decorative Surfaces
- 4.3 Market Restraints
- 4.3.1 Fire-Safety and Building-Code Compliance Costs
- 4.3.2 Raw-Material Price and Supply Volatility
- 4.3.3 Installation Quality and Substrate-Preparation Risk
- 4.3.4 Limited End-of-Life Recycling for Multilayer Panels and Wallpapers
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Insights into the Latest Trends and Innovations in the Industry
- 4.7 Insights into the Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Industry
- 4.8 Insights into Consumer Preferences for Designs and Surface Patterns
5 Market Size & Growth Forecasts (Value in USD Billion)
- 5.1 By Material
- 5.1.1 PVC and Vinyl
- 5.1.2 PU / Polyurethane
- 5.1.3 Natural Wood, MDF, and HDF
- 5.1.4 Gypsum/Plaster
- 5.1.5 Fiber Cement
- 5.1.6 Plant Fiber and Bagasse
- 5.1.7 Metal
- 5.1.8 Other Materials
- 5.2 By Installation Method
- 5.2.1 Adhesive-mounted
- 5.2.2 Mechanical fixing
- 5.2.3 Clip/interlocking
- 5.2.4 Mortar/cement-based installation
- 5.2.5 Self-adhesive / peel-and-stick
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.4 By Distribution Channel
- 5.4.1 B2C Channels
- 5.4.1.1 Hypermarkets and Supermarkets
- 5.4.1.2 Specialty Stores
- 5.4.1.3 Home Improvement Stores
- 5.4.1.4 Online
- 5.4.1.5 Local Hardware Shops
- 5.4.1.6 Other Distribution Channels
- 5.4.2 B2B Channels (Contractors and Installers, Interior Designers and Architects, Project Procurement and Institutional Sales)
- 5.4.1 B2C Channels
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 Canada
- 5.5.1.2 United States
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 BENELUX (Belgium, Netherlands, Luxembourg)
- 5.5.3.7 NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- 5.5.3.8 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 South-East Asia
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East & Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East & Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration Overview
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Art3d
- 6.4.2 Ekena Millwork
- 6.4.3 WallArt
- 6.4.4 CSI Creative
- 6.4.5 Profile VOX
- 6.4.6 MyWallArt
- 6.4.7 Greenmood
- 6.4.8 Fibo AS
- 6.4.9 Arte International
- 6.4.10 Saint-Gobain S.A.
- 6.4.11 Armstrong World Industries, Inc.
- 6.4.12 Knauf Group
- 6.4.13 Nichiha Corporation
- 6.4.14 LIXIL Corporation
- 6.4.15 Arktura
- 6.4.16 Vicoustic
- 6.4.17 Trespa International B.V.
- 6.4.18 EGGER Group
- 6.4.19 Kingspan Group plc
7 Market Opportunities & Future Outlook
- 7.1 Low-Carbon, Fully Documented 3D Wallcoverings
- 7.2 Modular Acoustic Feature Walls for Retrofit Projects

 住宅3D牆板市場:全球市場預測,2026-2032年
 抗指紋美耐板市場報告:趨勢、預測與競爭分析(至2035年)
 全球裝飾層壓板市場
 醫療壁紙:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)印度裝飾層壓板市場:市場佔有率分析、行業趨勢與統計及成長預測(2026-2031)無PVC壁紙:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)裝飾層壓板:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)凹版裝飾覆膜油墨:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 牆面藝術和裝飾配件市場預測至2034年——按產品類型、材質、風格、價格範圍、分銷管道、最終用戶和地區分類的全球分析
 高壓層壓和塑膠樹脂市場規模、佔有率和成長分析:按產品類型、應用、分銷管道、最終用戶和地區分類-2026-2033年產業預測