


 |
市場調查報告書
商品編碼
2157095
美國液壓機:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)United States Hydraulic Presses - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
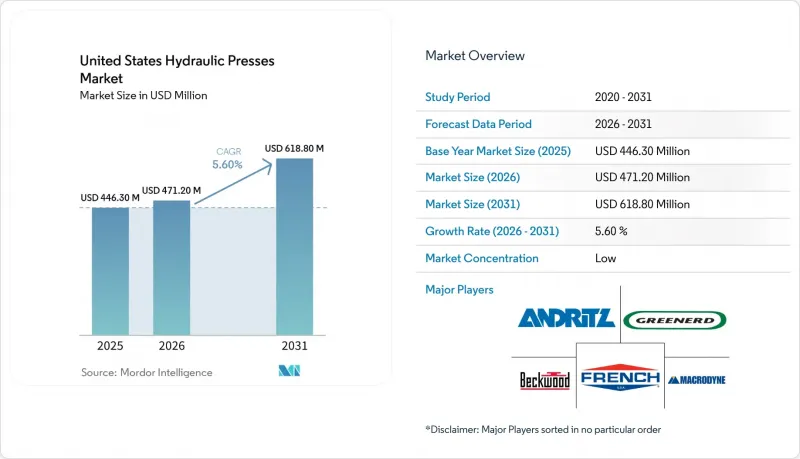
據 Mordor Intelligence 稱,2025 年美國液壓機市值為 4.463 億美元,預計到 2031 年將達到 6.188 億美元,而 2026 年為 4.712 億美元,2026 年至 2031 年預測期內的複合年成長率為 5.6%。
生產回流、工廠投資以及航太和國防領域的生產活動正在推動對新型成型和鍛造能力的需求。本報告按框架類型(C型框架、H型框架、四柱框架、雙柱框架及其他)、噸位(100噸以下、101-500噸、501-1000噸、1000噸以上)、應用領域(鈑金加工、鍛造、彎曲、組裝、粉末成型、液壓航太、航太等。市場預測以美元(USD)計價。
美國液壓機市場的趨勢與洞察
將生產活動轉移回國內並擴大國內生產能力
隨著國內產能的擴張,液壓機在沖壓加工、成型和鍛造製程的需求日益成長。根據“2026年回流調查”,63%的受訪目的地設備製造商(OEM)計劃在2026年或2027年投資回流或擴大國內生產。 65%的受訪者表示關稅是推動這些計畫的主要因素,60%的受訪者表示地緣政治風險是主要因素。根據美國國家標準與技術研究院(NIST)的報告,供應鏈的韌性以及製造和工程部門的地理位置接近性是OEM考慮回流的關鍵因素。這些優先事項非常適用於長壽命設備,例如可以根據生產計畫的變更進行重新配置或升級的壓平機。美國液壓機市場將受惠於設備升級項目和新產能擴張項目的同步推進。
自動化、機器人和智慧印刷機的整合
自動化正在改變人們對整個沖壓系統(而不僅僅是沖壓機架本身)的重視程度。 Greenerd公司推出了一款自動化多工位液壓沖壓系統,生產能力為每分鐘60件,集矯直、剪切、壓痕、鑽孔、倒角和穿梭輸送於一體。整合單元通常需要更大的工作檯面來容納機器人末端執行器、捲料送料系統和多模具佈局。即使成型工序可以用較小的獨立式壓平機完成,這種需求也可能需要選擇H型框架或四柱結構。 Macrodyne公司為Union公司位於德克薩斯州的155毫米砲彈工廠提供了一條自動化液壓沖壓生產線,這表明承包系統在國防生產中的重要性日益凸顯。此外,協調力和位移監測有助於在設備的整個生命週期中製定品管和維護計劃。
初始投資額高,投資回收期長
大量生產的液壓機系統需要大量的初期投資,這可能會限制中小型製造商的訂單。對於購買大型機械的公司而言,設備貸款和租賃是常見的資金籌措方式。美國國稅局 (IRS) 允許符合條件的公司在 2026 會計年度獲得 120 萬美元的第 179 條款稅收抵免,這可以降低稅後設備成本。然而,對於課稅收入有限或融資管道受限的買家來說,這項優惠可能作用不大。鎖定和機器保護要求可能會增加專案的設計、安裝和試運行成本。這些因素可能會推遲更換液壓機的決定,尤其是在公司可以透過維護工作延長現有液壓機使用壽命的情況下。
細分市場分析
到2025年,H型和直邊式液壓機將佔總銷量的41%,成為各型式液壓機中市佔率最大的。這些液壓機的導引滑塊設計適用於精密連續沖壓、航太鈑金成形和重型鍛造等對平行度要求極高的場合。這些液壓機在汽車行業的一級供應商和航太產業的成型工廠中擁有良好的應用記錄。其較長的使用壽命也帶來了持續的檢修、控制系統升級和液壓系統更換需求。這些成熟的應用記錄鞏固了H型液壓機在美國液壓機市場的地位。
預計到2031年,C型和間隙式液壓機的複合年成長率將達到8.05%。這些前置式結構非常適合需要機器人裝載、捲料送料和生產佈局柔軟性的訂單工廠。四柱壓力機在橡膠墊成型、寬幅複合複合材料成型和深拉延等領域繼續發揮至關重要的作用,因為它們可以將壓力分散到更大的工作面積。雙柱壓力機和桌上型壓力機則用於維護、實驗室和輕型組裝工作,這些工作對壓力要求較低,面積也較小。 Greenerd公司在2025年FABTECH展會上展示的多工位系統,將不同的沖頭和噸位配置整合在一個生產單位中。
到2025年,101-500噸級液壓機的銷售量將占美國液壓機總銷量的46%,成為美國液壓機市場中按壓力量分類的最大佔有率。此噸位範圍涵蓋通用金屬衝壓加工、汽車落料、橡膠壓縮成型以及二級航太零件組裝。它也被廣泛應用於美國中西部和東南部的成熟加工廠。許多在1990年代至1910年代安裝的液壓機,如今已需要對其原有的液壓系統進行大規模維修。由於其應用範圍廣泛,該頻寬的液壓機在美國液壓機市場中繼續佔據核心地位。
預計到2031年,噸位超過2000噸的壓力機將以6.67%的複合年成長率成長。需求主要來自航太鍛造、國防相關合約、海軍推進系統製造、能源基礎設施用渦輪軸成型。斯科特鍛造公司(Scott Forge)在伊利諾伊州斯普林格羅夫安裝了一台5000噸的開式模液壓機,並配備了在線超音波檢測功能,同時還獲得了一份與海軍推進系統相關的訂單,該訂單將持續到2029年。噸位在501至1000噸和1001至2000噸範圍內的壓力機主要用於航太領域的艙壁成型、液壓成型和結構複合材料成型。噸位在100噸以下的壓平機則繼續用於沖壓加工、複合材料修復以及研發活動。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
第5章 市場概覽
- 市場促進因素
- 將生產活動轉移回國內並擴大國內生產能力
- 自動化、機器人技術以及與智慧印刷機的整合
- 航太和國防領域對高負載成型的需求
- 汽車輕量化和先進材料的成型
- 現有印刷設備的維修需求及各區域的服務要求
- 升級為高效能伺服液壓和混合式壓力機。
- 市場限制因素
- 設備初始投資高,投資回收期長。
- 熟練勞動力短缺和工程師招募受限
- 液壓元件、鋼材和能源成本的波動
- 使用伺服電動壓力機和機械壓力機的替代技術和替代方案
- 市場規模與價值鏈分析
- 原料和結構件
- 液壓單元、幫浦、閥門、油缸
- 控制設備、感測器和自動化組件
- 模具和夾俱生態系統
- 安裝、維護、維修和重建服務
- 進口依賴和國內供應商本地化
- 監理情勢
- 美國職業安全與健康管理局 (OSHA) 對機器防護的要求
- 美國職業安全與健康管理局 (OSHA) 對危險能源和上鎖/掛牌的管理
- ANSI B11.2 液壓和氣壓動力壓力機的安全要求
- 液壓油、噪音和廢棄物。
- 技術展望
- 伺服液壓和高效驅動系統
- 自動化、機器人和自動化物料輸送系統
- 互聯媒體、工業物聯網與狀態監控
- 先進的力、位置和壓力控制
- 先進材料和複合材料的成型技術
- 地緣政治和貿易趨勢的影響
- 關稅和進口限制
- 液壓和控制元件的供應鏈風險
- 液壓機製造本地化
- 工業和製造業趨勢
- 汽車電氣化和電瓶組件製造
- 航太生產和國防領域的現代化
- 工業回流和工廠現代化
- 高品種、小批量生產
- 永續性和能源效率
- 每個成型週期的能耗
- 液壓油洩漏的預防和修復
- 延長產品壽命並創建循環經濟
第6章 市場規模與成長預測
- 框架/結構配置
- C型框架/間隙框架液壓機
- H型框架/直邊/導軌式液壓機
- 四柱/四柱液壓機
- 雙柱式液壓機
- 桌上型/車間液壓機
- 其他特殊液壓機配置
- 按噸位/壓力
- 不到100噸
- 101-500噸
- 501至1000噸
- 1001-2000噸
- 超過2000噸
- 透過應用/成型工藝
- 鈑金成形與深拉延
- 鍛造
- 彎曲和伸直
- 沖孔、打孔和壓印
- 壓縮成型
- 粉末成型
- 液壓成型
- 組裝、壓入配合和一般壓接作業
- 其他特殊用途
- 按最終用途行業分類
- 航太/國防
- 工業機械及一般製造業
- 電氣和電子設備
- 塑膠、橡膠、複合材料
- 建築和重型機械
- 能源和電力設備
- 鐵路和船舶
- 粉末冶金、陶瓷和先進材料
- 其他終端用戶產業
第7章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ANDRITZ Schuler Group
- Macrodyne Technologies Inc.
- Beckwood Press Company
- Greenerd Press & Machine Company, Inc.
- French Oil Mill Machinery Co.
- Enerpac Tool Group Corp.
- Pacific Press Holdings, LLC
- HPM North America
- Neff Press, Inc.
- Dake Corporation
- Betenbender Manufacturing, Inc.
- Multipress, Inc.
- Sutherland Presses
- Eagle Press & Equipment Co. Ltd.
- AIDA Engineering, Ltd.
- Komatsu Ltd.
- JIER Machine-Tool Group Co., Ltd.
- Fagor Arrasate
- Siempelkamp Group
- LASCO Umformtechnik GmbH
- Heim Corporation
- Ajax-CECO-Erie Press
- Hare Press Company
- Butech Bliss
- Carver, Inc.
- Dorst Technologies GmbH & Co. KG
- Gasbarre Products, Inc.
- Grimco Hydraulic Presses
第8章 市場機會與未來展望
- 評估閒置頻段和未滿足的需求
- 高效率伺服液壓機
- 老舊印刷機的維修和現代化改造
- 自動化聯網液壓機系統
- 高噸位航太與國防應用
- 先進材料和複合材料的成型
- 以在地化服務、零件和回收網路為重點
According to Mordor Intelligence, the United States hydraulic presses market size was valued at USD 446.3 million in 2025 and is estimated to grow from USD 471.2 million in 2026 to reach USD 618.8 million by 2031, at a CAGR of 5.6% during the forecast period 2026-2031.
Reshoring, factory investment, and aerospace and defense production are supporting demand for new forming and forging capacity. This report is Segmented by Frame (C-Frame, H-Frame, Four-Post, Two-Post, Other), by Tonnage (Up To 100, 101-500, 501-1, 000, and More), by Application (Sheet Metal, Forging, Bending, Compression Molding, Powder Compaction, Hydroforming, Assembly, Other), and by End-Use (Aerospace/Defense, Automotive, Machinery, Electronics, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Hydraulic Presses Market Trends and Insights
Reshoring and Domestic Manufacturing Capacity Expansion
Domestic capacity expansion is increasing the need for hydraulic presses across stamping, forming, and forging operations. The 2026 Reshoring Survey found that 63% of original equipment manufacturer respondents planned capital expenditures in 2026 or 2027 for reshoring or domestic expansion. Tariffs were identified by 65% of respondents and geopolitical risk by 60% as major catalysts for those plans. NIST reported that supply chain resilience and proximity between manufacturing and engineering operations were among the leading reshoring considerations for original equipment manufacturers. These priorities suit equipment with long operating lives, including presses that can be rebuilt or upgraded as production programs change. The United States hydraulic presses market benefits when both replacement projects and new capacity projects proceed at the same time.
Automation, Robotics, and Smart-Press Integration
Automation is changing the value placed on the press system rather than the press frame alone. Greenerd presented automated multi-station hydraulic press systems that combine straightening, shearing, dimpling, hole formation, chamfering, and shuttle transfer for an output of 60 parts per minute. Integrated cells often need larger beds for robotic end effectors, coil feed systems, and multi-die layouts. That requirement can favor H-frame and four-post equipment even when a smaller standalone press could form the part. Macrodyne supplied automated hydraulic press lines for UNION's 155mm artillery shell factory in Texas, showing the increasing importance of turnkey systems in defense production. Connected force and displacement monitoring can also support quality control and maintenance planning over the life of the asset.
High Initial Investment and Long Equipment Payback
Production-grade hydraulic press systems require significant initial capital, which can limit orders from smaller manufacturers. Equipment loans and leases are common funding methods for firms buying major machinery. The Internal Revenue Service allows qualifying businesses to claim a Section 179 deduction of USD 1.2 million for 2026, which can reduce after-tax equipment costs. The benefit is less useful for buyers with limited taxable income or limited access to credit. Lockout and machine guarding requirements can add engineering, installation, and commissioning costs to projects. These factors may postpone replacement decisions, especially when firms can extend the life of an existing press through service work.
Other drivers and restraints analyzed in the detailed report include:
- Demand for High-Force Forming in Aerospace and Defense
- Automotive Lightweighting and Advanced Material Forming
- Skilled Workforce Shortage and Technician Availability Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
H-frame and straight-side hydraulic presses held 41% of revenue in 2025, giving them the largest position by frame type. Their guided ram design supports precision progressive-die stamping, aerospace sheet forming, and heavy forging where parallelism is important. Automotive Tier-1 stampers and aerospace forming shops have a large installed base of these presses. Long service lives create a recurring need for rebuilding, control upgrades, and hydraulic system replacement. This established installed base gives H-frame equipment a durable role in the United States hydraulic presses market.
C-frame and gap-frame hydraulic presses are forecast to grow at an 8.05% CAGR through 2031. Their front-access arrangement supports robotic loading, coil feeding, and work in job shops where production layouts need flexibility. Four-post presses remain important for rubber-pad forming, wide-panel composite molding, and deep drawing because they distribute force over a larger bed area. Two-post and benchtop presses serve maintenance, laboratory, and light assembly work that needs lower force and a smaller footprint. Greenerd's multi-station systems presented at FABTECH 2025 combined different ram and tonnage configurations in a single production cell.
The 101-500 tons band held 46% of revenue in 2025, the largest share of the United States hydraulic presses market size by press force. This range covers general metal stamping, automotive blanking, rubber compression molding, and Tier-2 aerospace subassembly. It is also common in established fabricating plants across the Midwest and Southeast. Many units installed from the 1990s through the 2010s are approaching the point where original hydraulic systems require major work. The wide application range keeps this band central to the United States hydraulic presses market.
Above 2,000 tons presses are forecast to grow at a 6.67% CAGR through 2031. Demand is tied to aerospace forging, defense contracts, naval propulsion work, and turbine-shaft forming for energy infrastructure. Scot Forge commissioned a 5,000-ton open-die hydraulic press in Spring Grove, Illinois, with in-line ultrasonic inspection and naval propulsion orders extending through 2029. The 501-1,000 tons and 1,001-2,000 tons ranges serve aerospace bulkhead forming, hydroforming, and structural composite molding. Up to 100 tons presses continue to support press fitting, composite repair, research, and development work.
Complete Report Scope:
- By Frame / Structural Configuration
- C-Frame / Gap-Frame Hydraulic Presses
- H-Frame / Straight-Side / Gib-Guided Hydraulic Presses
- Four-Post / Four-Column Hydraulic Presses
- Two-Post / Column Hydraulic Presses
- Benchtop / Workshop Hydraulic Presses
- Other Specialized Hydraulic Press Configurations
- By Tonnage / Press Force
- Up to 100 Tons
- 101-500 Tons
- 501-1,000 Tons
- 1,001-2,000 Tons
- Above 2,000 Tons
- By Application / Forming Process
- Sheet Metal Forming and Deep Drawing
- Forging
- Bending and Straightening
- Punching, Blanking and Coining
- Compression Molding
- Powder Compaction
- Hydroforming
- Assembly, Press-Fitting and General Pressing
- Other Specialized Applications
- By End-Use Industry
- Aerospace and Defense
- Industrial Machinery and General Manufacturing
- Electrical and Electronics
- Plastics, Rubber and Composites
- Construction and Heavy Equipment
- Energy and Power Equipment
- Rail and Marine
- Powder Metallurgy, Ceramics and Advanced Materials
- Other End-Use Industries
List of Companies Covered in this Report:
- ANDRITZ Schuler Group
- Macrodyne Technologies Inc.
- Beckwood Press Company
- Greenerd Press & Machine Company, Inc.
- French Oil Mill Machinery Co.
- Enerpac Tool Group Corp.
- Pacific Press Holdings, LLC
- HPM North America
- Neff Press, Inc.
- Dake Corporation
- Betenbender Manufacturing, Inc.
- Multipress, Inc.
- Sutherland Presses
- Eagle Press & Equipment Co. Ltd.
- AIDA Engineering, Ltd.
- Komatsu Ltd.
- JIER Machine-Tool Group Co., Ltd.
- Fagor Arrasate
- Siempelkamp Group
- LASCO Umformtechnik GmbH
- Heim Corporation
- Ajax-CECO-Erie Press
- Hare Press Company
- Butech Bliss
- Carver, Inc.
- Dorst Technologies GmbH & Co. KG
- Gasbarre Products, Inc.
- Grimco Hydraulic Presses
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
5 Market Overview
- 5.1 Market Drivers
- 5.1.1 Reshoring and Domestic Manufacturing Capacity Expansion
- 5.1.2 Automation, Robotics, and Smart-Press Integration
- 5.1.3 Demand for High-Force Forming in Aerospace and Defense
- 5.1.4 Automotive Lightweighting and Advanced Material Forming
- 5.1.5 Retrofit Demand from Installed Press Bases and Local Service Requirements
- 5.1.6 Energy-Efficient Servo-Hydraulic and Hybrid Press Upgrades
- 5.2 Market Restraints
- 5.2.1 High Initial Investment and Long Equipment Payback
- 5.2.2 Skilled Workforce Shortage and Technician Availability Constraints
- 5.2.3 Hydraulic Component, Steel, and Energy Cost Volatility
- 5.2.4 Alternative Technologies and Substitution by Servo-Electric and Mechanical Presses
- 5.3 Value and Supply-Chain Analysis
- 5.3.1 Raw Materials and Structural Components
- 5.3.2 Hydraulic Power Units, Pumps, Valves, and Cylinders
- 5.3.3 Controls, Sensors, and Automation Components
- 5.3.4 Tooling and Die Ecosystem
- 5.3.5 Installation, Maintenance, Retrofit, and Rebuild Services
- 5.3.6 Import Dependence and Domestic Supplier Localization
- 5.4 Regulatory Landscape
- 5.4.1 OSHA Machine Guarding Requirements
- 5.4.2 OSHA Control of Hazardous Energy and Lockout/Tagout
- 5.4.3 ANSI B11.2 Safety Requirements for Hydraulic and Pneumatic Power Presses
- 5.4.4 Environmental Compliance for Hydraulic Fluids, Noise, and Waste
- 5.5 Technological Outlook
- 5.5.1 Servo-Hydraulic and Energy-Efficient Drive Systems
- 5.5.2 Automation, Robotics, and Automated Material Handling
- 5.5.3 Connected Presses, IIoT, and Condition Monitoring
- 5.5.4 Advanced Force, Position, and Pressure Control
- 5.5.5 Advanced Material and Composite Forming Technologies
- 5.6 Impact of Geopolitical and Trade Developments
- 5.6.1 Tariffs and Import Restrictions
- 5.6.2 Supply-Chain Risks for Hydraulic and Control Components
- 5.6.3 Localization of Hydraulic Press Manufacturing
- 5.7 Industry and Manufacturing Trends
- 5.7.1 Automotive Electrification and Battery-Component Manufacturing
- 5.7.2 Aerospace Production and Defense Modernization
- 5.7.3 Industrial Reshoring and Factory Modernization
- 5.7.4 High-Mix, Low-Volume Manufacturing
- 5.8 Sustainability and Energy Efficiency
- 5.8.1 Energy Consumption per Forming Cycle
- 5.8.2 Hydraulic Fluid Leakage Prevention and Recovery
- 5.8.3 Press Life Extension and Circularity
6 MARKET SIZE AND GROWTH FORECASTS
- 6.1 By Frame / Structural Configuration
- 6.1.1 C-Frame / Gap-Frame Hydraulic Presses
- 6.1.2 H-Frame / Straight-Side / Gib-Guided Hydraulic Presses
- 6.1.3 Four-Post / Four-Column Hydraulic Presses
- 6.1.4 Two-Post / Column Hydraulic Presses
- 6.1.5 Benchtop / Workshop Hydraulic Presses
- 6.1.6 Other Specialized Hydraulic Press Configurations
- 6.2 By Tonnage / Press Force
- 6.2.1 Up to 100 Tons
- 6.2.2 101-500 Tons
- 6.2.3 501-1,000 Tons
- 6.2.4 1,001-2,000 Tons
- 6.2.5 Above 2,000 Tons
- 6.3 By Application / Forming Process
- 6.3.1 Sheet Metal Forming and Deep Drawing
- 6.3.2 Forging
- 6.3.3 Bending and Straightening
- 6.3.4 Punching, Blanking and Coining
- 6.3.5 Compression Molding
- 6.3.6 Powder Compaction
- 6.3.7 Hydroforming
- 6.3.8 Assembly, Press-Fitting and General Pressing
- 6.3.9 Other Specialized Applications
- 6.4 By End-Use Industry
- 6.4.1 Aerospace and Defense
- 6.4.2 Industrial Machinery and General Manufacturing
- 6.4.3 Electrical and Electronics
- 6.4.4 Plastics, Rubber and Composites
- 6.4.5 Construction and Heavy Equipment
- 6.4.6 Energy and Power Equipment
- 6.4.7 Rail and Marine
- 6.4.8 Powder Metallurgy, Ceramics and Advanced Materials
- 6.4.9 Other End-Use Industries
7 COMPETITIVE LANDSCAPE
- 7.1 Market Concentration
- 7.2 Strategic Moves
- 7.3 Market Share Analysis
- 7.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 7.4.1 ANDRITZ Schuler Group
- 7.4.2 Macrodyne Technologies Inc.
- 7.4.3 Beckwood Press Company
- 7.4.4 Greenerd Press & Machine Company, Inc.
- 7.4.5 French Oil Mill Machinery Co.
- 7.4.6 Enerpac Tool Group Corp.
- 7.4.7 Pacific Press Holdings, LLC
- 7.4.8 HPM North America
- 7.4.9 Neff Press, Inc.
- 7.4.10 Dake Corporation
- 7.4.11 Betenbender Manufacturing, Inc.
- 7.4.12 Multipress, Inc.
- 7.4.13 Sutherland Presses
- 7.4.14 Eagle Press & Equipment Co. Ltd.
- 7.4.15 AIDA Engineering, Ltd.
- 7.4.16 Komatsu Ltd.
- 7.4.17 JIER Machine-Tool Group Co., Ltd.
- 7.4.18 Fagor Arrasate
- 7.4.19 Siempelkamp Group
- 7.4.20 LASCO Umformtechnik GmbH
- 7.4.21 Heim Corporation
- 7.4.22 Ajax-CECO-Erie Press
- 7.4.23 Hare Press Company
- 7.4.24 Butech Bliss
- 7.4.25 Carver, Inc.
- 7.4.26 Dorst Technologies GmbH & Co. KG
- 7.4.27 Gasbarre Products, Inc.
- 7.4.28 Grimco Hydraulic Presses
8 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 8.1 White-Space and Unmet-Need Assessment
- 8.1.1 Energy-Efficient and Servo-Hydraulic Presses
- 8.1.2 Retrofit and Modernization of Legacy Presses
- 8.1.3 Automated and Connected Hydraulic Press Systems
- 8.1.4 High-Tonnage Aerospace and Defense Applications
- 8.1.5 Advanced Materials and Composite Forming
- 8.1.6 Localized Service, Parts, and Rebuild Networks

 壓縮機市場:全球市場預測,2026-2032年冷擠壓與雙作用液壓機市場:全球市場預測,2026-2032年壓平機市場:全球市場預測,2026-2032年
 亞太地區工業壓平機:市佔率分析、產業趨勢與統計及成長預測(2026-2031)越南液壓機市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)北美液壓機市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)日本液壓機市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)歐洲液壓機:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)液壓機:市佔率分析、產業趨勢與統計、成長預測(2026-2031)
 2026-2030年全球液壓壓平機市場