


 |
市場調查報告書
商品編碼
2154843
南美洲電動車市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)South America Electric Drives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
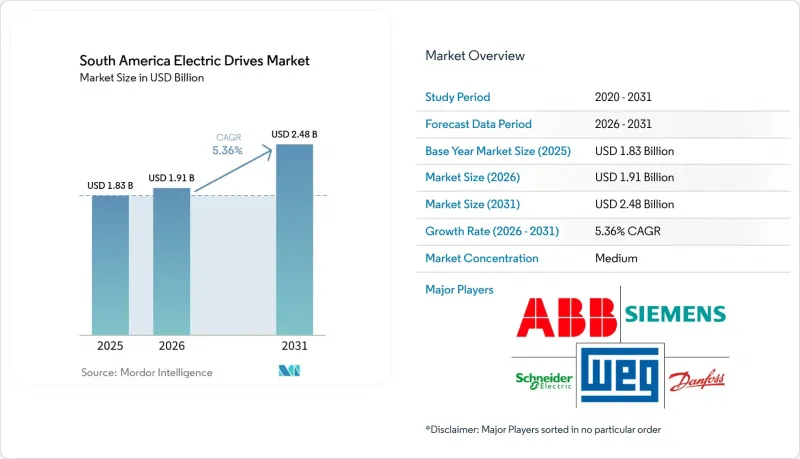
據 Mordor Intelligence 稱,2025 年南美電動裝置市場價值為 18.3 億美元,預計到 2031 年將從 2026 年的 19.1 億美元成長至 24.8 億美元,預測期(2026-2031 年)複合年成長率為 5.36%。
南美洲電動驅動市場趨勢與洞察
工業自動化與棕地改造
南美洲各地的製造商正在老舊生產設施中用變速系統取代恆速設備。這一趨勢正在推動南美洲的電動驅動市場發展,尤其是在巴西的現有工業區,除了節能之外,設備更換需求也日益成為更換決策的重要因素。數位化試運行可以減少複雜維修工程的工程工作量,並縮短現場運作。 2026年2月,羅克韋爾自動化公司報告稱,其在巴西Falcare工業設備公司的專案中實現了更短的專案週期和更少的工程工作量。在多驅動設備維修專案中,擁有現場工程師和完善服務網路的供應商更具優勢。
提高馬達效率和降低能源成本的法規
巴西的能源效率法規正在推動老舊馬達及其相關控制設備的更新換代。高效率馬達和驅動器的結合使用可以降低幫浦和風扇等變扭矩應用中的電力消耗。聯合國環境規劃署(UNEP)將馬達系統政策定位為加速推廣高效率馬達應用的手段。如果升級改造能夠滿足諧波抑制和安全要求,南美馬達驅動市場也將從中受益。 ABB在戈亞斯州薩內阿戈的四個泵站安裝了15台ACQ580驅動器和高效率馬達。該專案使能耗降低了25%,相當於每年節省超過6000兆瓦時,並帶來了每年340萬巴西幣(約58.6萬美元)的成本節約。
高初始成本與接觸器啟動器的比較
變頻驅動系統的成本可能是同等規格直驅接觸器啟動器的三到八倍。這種價格差異對於資金籌措管道有限的中小型企業而言仍然是一個巨大的障礙。 2025年巴西國內利率的上升進一步加劇了低馬達負載項目的成本門檻。許多營運商仍根據購置成本而非全生命週期電力消耗量來評估設備。大規模工業營運商可以透過正規的能源管理專案來部署驅動系統,而小規模工廠可能仍會選擇接觸器或緩衝啟動器。這種兩極化的採購模式正在限制南美洲電力驅動市場的短期成長。
細分市場分析
到2025年,交流變頻器將佔產品銷售額的68.47%,成為南美洲馬達驅動市場最大的產品類型。交流變頻器廣泛應用於泵浦、風扇、暖通空調系統和壓縮機,為常見的工業負載提供變速控制。其久經考驗的性能支撐了水處理、食品加工和一般製造業的替換需求。直流驅動器則繼續用於紙漿、印刷和金屬加工等行業的舊設備。預計到2031年,伺服驅動器的複合年成長率將達到5.92%。
伺服系統可在灌裝、貼標、包裝、電子產品和汽車組裝等領域實現精確且可重複的運動。其成長反映了巴西新增自動化生產能力的擴張,而非現有交流變頻器的規模擴大。自動化設備的安全要求也推動了對整合安全功能的系統的需求。供應商正將伺服驅動器定位為更廣泛的運動控制方案的一部分。需要精確機器控制的高價值應用正在推動對這些系統的需求。
到2025年,低電壓驅動器的銷售額將佔總銷售額的74.62%,這主要得益於大量馬達運轉電壓低於690V。這些系統廣泛應用於食品加工廠、供水管網、暖通空調設備以及各種生產線。即使大規模資本項目延期,低壓驅動器的長期成功應用也能確保市場需求的持續成長。預計到2031年,中壓驅動器的年複合成長率將達到6.21%。低壓驅動器的市佔率反映的是銷售需求,而非單筆訂單金額。
銅提煉、海上壓縮系統、紙漿廠和高產能加工廠是中壓設備的主要應用領域。與更換低壓設備相比,這些項目的核准、安裝和維護週期更長。新建礦山電氣系統擴大採用大型馬達和整合控制系統進行設計。這種趨勢凸顯了能夠提供全面設備供應、現場支援和長期維護的供應商的重要性。南美洲的電動裝置市場涵蓋多個電壓等級,採購週期和客戶需求各不相同。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 工業自動化與棕地改造
- 有關馬達效率和降低能源成本的法規
- 投資領域包括採礦、金屬、紙漿和造紙以及水利基礎設施。
- 電池、汽車和包裝生產線對精密運動的需求
- 巴西製造商正引領該地區電機驅動生態系統的擴張。
- 針對偏遠地區和惡劣環境下的資產進行驅動器級預測性維護。
- 市場限制因素
- 與接觸器起動器相比,初始成本較高
- 外匯波動及進口電力電子產品風險
- 在主要工業中心以外,提供本地化服務的能力有限。
- 與諧波、熱力學和電網相容性相關的維修的複雜性。
- 宏觀經濟因素對市場的影響
- 產業供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品
- 交流變頻器
- 直流驅動器
- 伺服驅動器
- 透過電壓
- 低壓驅動
- 中壓驅動
- 額定功率
- 小於250千瓦
- 251~500 kW
- 500千瓦或以上
- 按最終用戶行業分類
- 石油和天然氣
- 水和污水處理
- 化工/石油化工
- 食品/飲料
- 發電
- HVAC
- 紙漿和造紙
- 各行業
- 其他終端用戶產業
- 按地區
- 巴西
- 智利
- 阿根廷
- 其他南美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB Ltd
- Siemens AG
- WEG SA
- Schneider Electric SE
- Danfoss A/S
- Rockwell Automation, Inc.
- Yaskawa Electric Corporation
- Mitsubishi Electric Corporation
- Nidec Corporation
- Fuji Electric Co., Ltd.
- Hitachi, Ltd.
- Toshiba International Corporation
- Emerson Electric Co.
- Eaton Corporation plc
- TMEIC Corporation
- SEW-EURODRIVE GmbH & Co KG
- Bonfiglioli Riduttori SpA
- Lenze SE
- Parker-Hannifin Corporation
- Delta Electronics, Inc.
- Kollmorgen Corporation
- Envases del Plata SA
- Impress Brasil Embalagens Metalicas Ltda.
- Metalgrafica Industria e Comercio Ltda.
第7章 市場機會與未來展望
According to Mordor Intelligence, the South America electric drives market size was valued at USD 1.83 billion in 2025 and is estimated to grow from USD 1.91 billion in 2026 to reach USD 2.48 billion by 2031, at a CAGR of 5.36% during the forecast period (2026-2031).
South America Electric Drives Market Trends and Insights
Industrial Automation and Brownfield Modernization
Manufacturers are replacing fixed-speed equipment with variable-speed systems in aging production sites across South America. This activity supports replacement demand in the South America Electric Drives Market, especially in Brazil's established industrial areas. The replacement decision increasingly reflects production needs as well as energy savings. Digital commissioning can reduce engineering work and shorten site disruption during complex retrofits. Rockwell Automation reported reduced project-delivery time and engineering effort at Falcare Industrial Equipment in Brazil in February 2026. Suppliers with field technicians and established service networks are better positioned for multi-drive retrofit work.
Motor Efficiency and Energy Cost Reduction Mandates
Brazil's efficiency rules support replacement cycles for older motors and associated control equipment. Pairing an efficient motor with a drive can reduce electricity use in variable-torque applications such as pumps and fans. The United Nations Environment Program identifies motor-system policies as a route to faster deployment of efficient electric motors. The South America Electric Drives Market also benefits when upgrades include harmonic and safety requirements. ABB installed 15 ACQ580 drives and high-efficiency motors at 4 Saneago pumping stations in Goias. The project reduced energy consumption by 25%, equal to more than 6,000 MWh annually, and generated annual savings of BRL 3.4 million (USD 586,000).
High Upfront Cost Versus Contactor Starters
Variable-frequency drive systems can cost 3 to 8 times more than comparable direct-on-line contactor starters. This price gap remains a material barrier for small and medium enterprises with limited access to financing. Higher domestic interest rates in Brazil during 2025 increased the cost hurdle for projects with smaller motor loads. Many operators still assess equipment using purchase cost rather than lifetime electricity use. Large industrial operators can adopt drives through formal energy-management programs, while smaller facilities may continue to select contactors and soft starters. This two-speed purchasing pattern moderates near-term growth in the South America Electric Drives Market.
Other drivers and restraints analyzed in the detailed report include:
- Mining, Metals, Pulp and Paper, and Water Infrastructure Investment
- Precision Motion Demand From Battery, Automotive, and Packaging Lines
- Currency Volatility and Imported Power Electronics Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
AC drives accounted for 68.47% of product revenue in 2025 and were the largest product category in the South America Electric Drives Market. They are widely used in pumps, fans, air-handling equipment, and compressors because they provide variable-speed control for common industrial loads. Their installed base supports replacement demand across water treatment, food processing, and general manufacturing. DC drives continued to serve older equipment in pulp, printing, and metalworking applications. Servo drives are forecast to grow at a CAGR of 5.92% through 2031.
Servo systems enable precise, repeatable motion in filling, labeling, packaging, electronics, and vehicle assembly. Their growth reflects new automated production capacity in Brazil rather than the scale of the installed AC-drive base. Safety requirements for automated equipment also favor systems with integrated safety functions. Suppliers are positioning servo drives as part of wider motion-control packages. Higher-value applications that need accurate machine control support demand these systems.
Low-voltage drives accounted for 74.62% of revenue in 2025, driven by the large number of motors below 690 V. These systems serve food plants, water networks, HVAC equipment, and discrete manufacturing lines. Their broad installed base provides recurring demand even when larger capital projects are delayed. Medium-voltage drives are forecast to grow at a CAGR of 6.21% through 2031. The low-voltage share reflects volume demand rather than the value of individual orders.
Copper concentrators, offshore compression systems, pulp mills, and high-capacity treatment plants are central applications for medium-voltage equipment. Such projects have longer approval, installation, and service cycles than low-voltage replacements. Electrical systems in new mines are increasingly designed around large electric motors and integrated controls. This approach raises the importance of suppliers that can provide equipment, site support, and long-term maintenance. The South America Electric Drives Market covers voltage tiers with different purchase cycles and customer requirements.
Complete Report Scope:
- By Product
- AC Drives
- DC Drives
- Servo Drives
- By Voltage
- Low-Voltage Drives
- Medium-Voltage Drives
- By Power Rating
- Less Than 250 kW
- 251-500 kW
- Above 500 kW
- By End-User Industry
- Oil and Gas
- Water and Wastewater
- Chemicals and Petrochemicals
- Food and Beverages
- Power Generation
- HVAC
- Pulp and Paper
- Discrete Industries
- Other End-User Industries
- By Geography
- Brazil
- Chile
- Argentina
- Rest of South America
List of Companies Covered in this Report:
- ABB Ltd
- Siemens AG
- WEG S.A.
- Schneider Electric SE
- Danfoss A/S
- Rockwell Automation, Inc.
- Yaskawa Electric Corporation
- Mitsubishi Electric Corporation
- Nidec Corporation
- Fuji Electric Co., Ltd.
- Hitachi, Ltd.
- Toshiba International Corporation
- Emerson Electric Co.
- Eaton Corporation plc
- TMEIC Corporation
- SEW-EURODRIVE GmbH & Co KG
- Bonfiglioli Riduttori S.p.A.
- Lenze SE
- Parker-Hannifin Corporation
- Delta Electronics, Inc.
- Kollmorgen Corporation
- Envases del Plata S.A.
- Impress Brasil Embalagens Metalicas Ltda.
- Metalgrafica Industria e Comercio Ltda.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Industrial Automation and Brownfield Modernization
- 4.2.2 Motor-Efficiency and Energy-Cost Reduction Mandates
- 4.2.3 Mining, Metals, Pulp and Paper, and Water Infrastructure Investment
- 4.2.4 Precision Motion Demand From Battery, Automotive, and Packaging Lines
- 4.2.5 Local Motor-Drive Ecosystem Expansion Led by Brazilian Manufacturers
- 4.2.6 Drive-Level Predictive Maintenance for Remote and Harsh-Environment Assets
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost Versus Contactor Starters
- 4.3.2 Currency Volatility and Imported Power-Electronics Exposure
- 4.3.3 Limited Regional Service Skills Outside Major Industrial Hubs
- 4.3.4 Harmonic, Thermal, and Grid-Compatibility Retrofit Complexity
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 AC Drives
- 5.1.2 DC Drives
- 5.1.3 Servo Drives
- 5.2 By Voltage
- 5.2.1 Low-Voltage Drives
- 5.2.2 Medium-Voltage Drives
- 5.3 By Power Rating
- 5.3.1 Less Than 250 kW
- 5.3.2 251-500 kW
- 5.3.3 Above 500 kW
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Water and Wastewater
- 5.4.3 Chemicals and Petrochemicals
- 5.4.4 Food and Beverages
- 5.4.5 Power Generation
- 5.4.6 HVAC
- 5.4.7 Pulp and Paper
- 5.4.8 Discrete Industries
- 5.4.9 Other End-User Industries
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Chile
- 5.5.3 Argentina
- 5.5.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 WEG S.A.
- 6.4.4 Schneider Electric SE
- 6.4.5 Danfoss A/S
- 6.4.6 Rockwell Automation, Inc.
- 6.4.7 Yaskawa Electric Corporation
- 6.4.8 Mitsubishi Electric Corporation
- 6.4.9 Nidec Corporation
- 6.4.10 Fuji Electric Co., Ltd.
- 6.4.11 Hitachi, Ltd.
- 6.4.12 Toshiba International Corporation
- 6.4.13 Emerson Electric Co.
- 6.4.14 Eaton Corporation plc
- 6.4.15 TMEIC Corporation
- 6.4.16 SEW-EURODRIVE GmbH & Co KG
- 6.4.17 Bonfiglioli Riduttori S.p.A.
- 6.4.18 Lenze SE
- 6.4.19 Parker-Hannifin Corporation
- 6.4.20 Delta Electronics, Inc.
- 6.4.21 Kollmorgen Corporation
- 6.4.22 Envases del Plata S.A.
- 6.4.23 Impress Brasil Embalagens Metalicas Ltda.
- 6.4.24 Metalgrafica Industria e Comercio Ltda.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 OEM 電動驅動單元 (EDU) 市場規模、佔有率和成長分析:按驅動單元類型、車輛類型、電動車類型、馬達類型、驅動配置和地區分類 - 2026-2033 年行業預測
 2026 年至 2035 年 OEM 電動驅動單元的市場機會、成長要素、產業趨勢分析與預測。
 亞太地區電動驅動市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)交流電驅動:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)低壓馬達驅動:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)電動驅動:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2034年全球電動驅動單元市場預測-按組件、驅動系統、電壓架構、推進方式、架構類型、銷售管道和地區分類的分析
 電氣和機械驅動裝置市場:2026-2032年全球市場預測(按驅動系統、額定功率、速度範圍、最終用戶產業、應用和控制系統分類)中東和非洲的電動式驅動:市場佔有率分析、產業趨勢和成長預測(2025-2030)全球直流 (DC) 電力驅動市場:市場佔有率分析、產業趨勢與統計、成長預測(2025-2030 年)