


 |
市場調查報告書
商品編碼
2154249
新加坡航運代理服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Singapore Shipping Agency Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,新加坡船舶代理服務市場在 2025 年的價值將達到 3.7711 億美元,預計到 2031 年將達到 4.9286 億美元,而 2026 年為 3.9486 億美元,預測期(2026-2031 年)的複合年成長率為 4.3%。
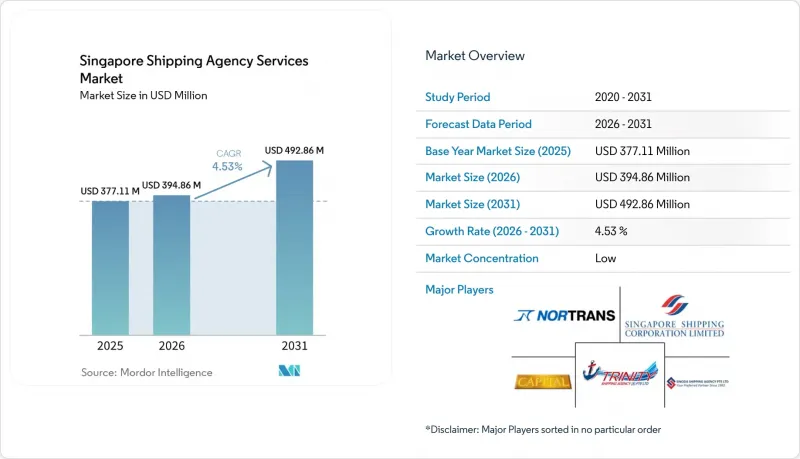
新加坡船舶代理服務市場主要受新加坡作為重要港口樞紐的地位驅動,繁忙的商船航運活動持續推高了對持牌代理商的需求。本報告按代理類型(港口代理、貨運代理、租船代理及其他)、客戶類型(船東、租船人/租賃人及其他客戶類型)和服務類型(包裝服務、航運服務、清關、物流支援服務及其他服務)進行細分。市場預測以美元計價。
新加坡船舶代理服務市場的趨勢與洞察
新加坡港的船舶吞吐量和到港船舶數量均有所增加。
新加坡的船舶代理服務市場以船舶到港數量和貨櫃吞吐量為基礎,因為商業船舶靠港需要本地代理的支援。預計到2025年,船舶到港總噸位將達到32.2億總噸,貨櫃吞吐量將達到4,466萬標準箱。根據《海事及港務管理局法》和港口法規,授權代理商必須透過digitalPORT@SG™平台處理港口申報和海關文件。預計到2025年,新加坡註冊船舶總噸位將成長27%,達到1.3746億總噸,這將擴大可委任當地經銷商的船東數量。這一成長還包括液化天然氣船隊管理者和海上航運運營商,他們需要的船舶管理支援不僅限於交易服務。自2024年推出以來,已有超過150家港口用戶加入即時規劃與協調平台,隨著泊位和海事服務能力日益緊張,即時協調變得愈發重要。
擴大船舶燃料庫和替代燃料處理量
預計2025年,新加坡港處理的替代船用燃料量將增加44%,達到195萬噸。其中,生質燃料混合物預計增加54%,液化天然氣(LNG)增加24%,甲醇量將達到3,000噸。新加坡已於2026年1月1日起頒發商業甲醇燃料庫許可證,並將基於TR129技術標準的新工作流程納入常規港口靠泊安排。船舶代理需要在停泊期間協調燃料特定認證、質量流量計檢驗和電子燃油交付單(BDN)等程序。新加坡海事及港務管理局(MPA)及新加坡企業發展局計畫於2026年將LNG加註供應的技術標準升級為新加坡標準,而氨加註供應的技術標準也預計將於2026年制定。因此,新加坡船舶代理服務市場越來越重視能夠處理多種燃料相關文書程序而不影響船舶航程的訓練有素的員工。
分散的競爭格局與價格壓力
新加坡有超過100家持牌代理機構,從擁有國際網路的大型業者到員工不足10人的精品公司,都在競相爭奪港口靠泊貨物的合約。這種競爭格局持續對低層級的支付和船舶管理費用帶來壓力。與OCEANS-X和TradeTrust等平台進行數位化整合正成為部分客戶的最低要求,但低利潤率限制了小規模代理商的投資。新加坡航運協會(SSA)成員在2025年11月舉行的MPA-SSA執行長對話會前夕,將不斷上漲的營運成本列為主要擔憂。租船人/租賃人是成長最快的客戶群體,他們通常會比較不同供應商的代理費,並且可能對標準服務的價格越來越敏感。新加坡船舶代理服務市場對那些透過專業燃油運營、可靠的數位化執行或廣泛的服務範圍脫穎而出的公司仍然具有吸引力。
細分市場分析
2025年,港口代理在新加坡船舶代理服務市場中佔據55.97%的佔有率。這是因為,根據新加坡本地港口框架,商船進出港需要全面的代理商支援。這些服務包括港口出入港文件辦理、與相關部門協調以及船舶靠泊期間的實際支援。新加坡船舶代理服務市場中港口代理的市場規模之所以如此之大,是因為每次商船靠港都需要重複辦理相關手續。隨著2026年1月甲醇燃料的啟用以及氨燃料加註程序的逐步完善,此類船舶管理和燃料加註服務將變得更加精細化。負責處理這些靠港事務的代理需要管理燃料專用證書、質量流量計檢查以及電子燃料交付單據(BDN)的記錄。此外,由於租船人和托運人會委託其他代理商負責船舶管理安排,因此保護性代理商的重要性也不斷提升。這可能會增加與單次靠港相關的代理合約數量。貨運代理業務持續受惠於貨櫃、乾散貨、液散貨和件雜貨運輸活動,其中新加坡在 2025 年處理的貨櫃量達 4,466 萬標準箱。班輪貨運代理也擁有穩定的貨運量基礎,這得益於受《集團豁免令》保護的船舶共用協議,該豁免令已續期至 2029 年。
預計2026年至2031年間,租船代理業務將以5.33%的複合年成長率成長,成為新加坡航運代理服務市場中成長最快的代理類別。這一成長反映了租船業務在船舶類型和貿易航線上的多元化發展。新加坡擁有九條綠色數位化航運走廊,包括2025年開通的通往印度和韓國的航線。這些航線將催生新的航次結構,並可能導致對指定代理商的進一步協調需求。對於使用替代燃料的船舶,租船合約條款可能需要明確規定燃料合規性檢查的責任方。這項責任通常由指定代理機構在船舶靠港時承擔。因此,無論是船東指定的租船代理服務還是租船人指定的租船代理服務,都在針對液化天然氣運輸船、甲醇相容船舶和專案貨船進行擴展。同時,由於數位化平台簡化了日常文書工作,貨運代理商和無船承運人(NVOCC)的支援服務價格仍然相對敏感。雖然這些角色本身仍然存在,但當不再需要專業的現場工作時,提供服務業者被取代的風險正在增加。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 當前市場狀況
- 市場促進因素
- 新加坡港口吞吐量和船舶進出數量均有所增加。
- 擴大船舶燃料庫和替代燃料補給港口停靠次數
- 位於麻六甲海峽的戰略位置
- 對港口停靠和船舶管理服務一體化的需求日益成長。
- 引入可互通的電子載貨證券
- 網路安全和數位合規支援的需求日益成長
- 市場限制因素
- 分散的競爭格局與價格壓力
- 熟練的海事和港口作業人員短缺
- 數位貿易平台之間的互通性差距
- 與網路安全、資料完整性和法律責任相關的風險日益增加。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 地緣政治事件對市場的影響
第5章 市場規模與成長預測
- 市場規模及預測
- 按機構類型分類
- 港口代理
- 貨運代理
- 包機機構
- 其他
- 依客戶類型
- 船東
- 包租人/租賃人
- 其他客戶類型
- 按服務類型
- 包裝服務
- 送貨服務
- 報關
- 物流支援服務
- 其他服務
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Sinoda Shipping Agency Pte Ltd
- Nortrans
- Singapore Shipping Corporation Limited
- Capital Shipping Agency(S)Pte Ltd
- Trinity Shipping Agency(S)Pte Ltd
- AlfaShip Agencies(Singapore)Pte Ltd
- Singapore Maritime Services
- Golden Harvest Shipping Agency
- Straits Link Ship Agencies & Management Pte Ltd
- Pacmar Shipping Pte Ltd
- Atomic Shipping & Trading Co Pte Ltd
- Amancare Marine Offshore Pte Ltd
- Focal Shipping Services Pte Ltd
- RTA Shipping
- Himo Marine Service Pte Ltd
- Edtech Marine
- Singapore Marine Agency Pte. Ltd.
- Amigoz Singapore Pte Ltd
- Parsh Marine
- Crystal Offshore Pte Ltd
第7章 市場機會與未來展望
第8章附錄
According to Mordor Intelligence, the Singapore shipping agency services market was valued at USD 377.11 million in 2025 and estimated to grow from USD 394.86 million in 2026 to reach USD 492.86 million by 2031, at a CAGR of 4.53% during the forecast period (2026-2031).
The Singapore shipping agency services market is supported by Singapore's role as a major port hub, where commercial vessel activity creates a continuing need for licensed agents. This report is Segmented by Agency Type (Port Agency, Cargo Agency, Charter Agency, Others), by Client Type (Shipowners, Charterers/Lessee, Other Client Type), and by Service Type (Packaging Services, Shipping Services, Customs Clearance, Logistical Support Services, Other Services). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Shipping Agency Services Market Trends and Insights
Growth in Singapore Port Throughput and Vessel Arrivals
The Singapore shipping agency services market draws a direct volume base from vessel arrivals and container handling because commercial calls require local agency support. Vessel arrivals reached 3.22 billion GT in 2025, while container throughput reached 44.66 million TEUs. The MPA Act and port regulations require a licensed agent to handle arrival declarations and clearance documentation through digitalPORT@SG(TM). The Singapore Registry of Ships expanded 27% to 137.46 million GT in 2025, which increased the group of vessel principals that can appoint local agents. This expansion included LNG fleet managers and offshore vessel operators that often need wider husbandry support rather than narrow, transaction-based services. More than 150 port users had joined the Just-In-Time Planning and Coordination Platform after its 2024 launch, making real-time coordination more important when berth and marine-service windows are tighter.
Expansion of Bunkering and Alternative Marine Fuel Calls
Alternative marine fuel volume at the Port of Singapore rose 44% to 1.95 million tons in 2025. Biofuel blends rose 54%, LNG rose 24%, and methanol volume reached 3,000 tons during the year. Singapore issued commercial methanol bunkering licenses effective January 1, 2026, bringing new workflows under Technical Reference TR129 into ordinary port-call coordination. Agents must coordinate fuel-specific certification, mass flow meter verification, and electronic Bunker Delivery Note processes during these calls. MPA and Enterprise Singapore are upgrading the LNG bunkering technical reference to a Singapore Standard in 2026, and an ammonia bunkering technical reference is expected in 2026. The Singapore shipping agency services market, therefore, places greater value on trained staff who can manage several fuel-documentation procedures without disrupting vessel schedules.
Fragmented Competitive Structure and Pricing Pressure
More than 100 licensed agencies compete for Singapore port-call mandates, including international network operators and boutique firms with fewer than 10 employees. This structure keeps pressure on disbursement margins and husbandry fees in the lower tier. Digital integration with OCEANS-X and TradeTrust-enabled platforms is becoming a minimum capability for some principals, but thin margins restrict investment by smaller agencies. Singapore Shipping Association members identified rising operating costs as a leading concern before the November 2025 MPA-SSA CEO dialogue. Charterers/Lessees, which are the fastest-growing client group, commonly compare agent fees across providers and may increase the price focus for standard services. The Singapore shipping agency services market remains more attractive for firms that differentiate through specialist fuel work, reliable digital execution, or broader service coverage.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Interoperable Electronic Bills of Lading
- Rising Demand for Integrated Port Call and Husbandry Services
- Shortage of Skilled Maritime and Port-Operations Personnel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Port agency held 55.97% of the Singapore shipping agency services market share in 2025 because commercial vessel arrivals need full-agency support under the local port framework. The service includes arrival and departure documentation, coordination with authorities, and practical support during a vessel's stay. The Singapore shipping agency services market size for Port agency is supported by the recurring nature of formalities at every commercial call. Husbandry and bunker work within this category have become more detailed as methanol bunkering started in January 2026, and ammonia procedures are under development for 2026. Agents handling these calls must manage fuel-specific certificates, mass flow meter checks, and electronic bunker delivery note records. Protective agency is also gaining relevance when charterers and cargo interests appoint a separate agent to oversee husbandry arrangements for their own account. This can increase the number of agency appointments connected with one vessel call. Cargo Agency continues to benefit from container, dry bulk, liquid bulk, and breakbulk activity, including the 44.66 million TEUs processed in Singapore during 2025. Liner cargo agencies also receive a stable volume base from vessel-sharing arrangements covered by the Block Exemption Order renewed through 2029.
Charter agency is projected to grow at a 5.33% CAGR from 2026 to 2031, making it the fastest-growing agency category in the Singapore shipping agency services market. The increase reflects a broader mix of charter activity across vessel types and trade routes. Singapore had 9 green and digital shipping corridors, including corridors with India and Korea established in 2025. These routes can create new voyage structures and additional coordination needs for appointed agents. Alternative-fuel vessels may require charter-party clauses that define responsibilities for fuel-compliance checks. Those responsibilities often involve the nominated agent during the call. Shipowner-nominated and charterer-nominated charter agency services are therefore growing together across LNG, methanol-capable, and project-cargo vessels. Freight agency and NVOCC support remain more price-sensitive because digital platforms can simplify routine documentation. Their role persists, but their providers face a greater risk of being replaced when the work does not require specialized local execution.
Complete Report Scope:
- Market Size and Forecast
- By Agency Type
- Port Agency
- Cargo Agency
- Charter Agency
- Others
- By Client Type
- Ship Owners
- Charterers/Lessee
- Other Client Types
- By Service Type
- Packaging Services
- Shipping Services
- Customs Clearance
- Logistical Support Services
- Other Services
List of Companies Covered in this Report:
- Sinoda Shipping Agency Pte Ltd
- Nortrans
- Singapore Shipping Corporation Limited
- Capital Shipping Agency (S) Pte Ltd
- Trinity Shipping Agency (S) Pte Ltd
- AlfaShip Agencies (Singapore) Pte Ltd
- Singapore Maritime Services
- Golden Harvest Shipping Agency
- Straits Link Ship Agencies & Management Pte Ltd
- Pacmar Shipping Pte Ltd
- Atomic Shipping & Trading Co Pte Ltd
- Amancare Marine Offshore Pte Ltd
- Focal Shipping Services Pte Ltd
- RTA Shipping
- Himo Marine Service Pte Ltd
- Edtech Marine
- Singapore Marine Agency Pte. Ltd.
- Amigoz Singapore Pte Ltd
- Parsh Marine
- Crystal Offshore Pte Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Current Market Scenario
- 4.3 Market Drivers
- 4.3.1 Growth in Singapore Port Throughput and Vessel Arrivals
- 4.3.2 Expansion of Bunkering and Alternative Marine Fuel Calls
- 4.3.3 Strategic Location on the Strait of Malacca
- 4.3.4 Rising Demand for Integrated Port Call and Husbandry Services
- 4.3.5 Adoption of Interoperable Electronic Bills of Lading
- 4.3.6 Increasing Need for Cybersecurity and Digital Compliance Support
- 4.4 Market Restraints
- 4.4.1 Fragmented Competitive Structure and Pricing Pressure
- 4.4.2 Shortage of Skilled Maritime and Port-Operations Personnel
- 4.4.3 Interoperability Gaps Across Digital Trade Platforms
- 4.4.4 Rising Cybersecurity, Data-Integrity, and Liability Exposure
- 4.5 Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Industry Rivalry
- 4.9 Impact of Geopolitical Events on the Market
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 Market Size and Forecast
- 5.2 By Agency Type
- 5.2.1 Port Agency
- 5.2.2 Cargo Agency
- 5.2.3 Charter Agency
- 5.2.4 Others
- 5.3 By Client Type
- 5.3.1 Ship Owners
- 5.3.2 Charterers/Lessee
- 5.3.3 Other Client Types
- 5.4 By Service Type
- 5.4.1 Packaging Services
- 5.4.2 Shipping Services
- 5.4.3 Customs Clearance
- 5.4.4 Logistical Support Services
- 5.4.5 Other Services
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Sinoda Shipping Agency Pte Ltd
- 6.4.2 Nortrans
- 6.4.3 Singapore Shipping Corporation Limited
- 6.4.4 Capital Shipping Agency (S) Pte Ltd
- 6.4.5 Trinity Shipping Agency (S) Pte Ltd
- 6.4.6 AlfaShip Agencies (Singapore) Pte Ltd
- 6.4.7 Singapore Maritime Services
- 6.4.8 Golden Harvest Shipping Agency
- 6.4.9 Straits Link Ship Agencies & Management Pte Ltd
- 6.4.10 Pacmar Shipping Pte Ltd
- 6.4.11 Atomic Shipping & Trading Co Pte Ltd
- 6.4.12 Amancare Marine Offshore Pte Ltd
- 6.4.13 Focal Shipping Services Pte Ltd
- 6.4.14 RTA Shipping
- 6.4.15 Himo Marine Service Pte Ltd
- 6.4.16 Edtech Marine
- 6.4.17 Singapore Marine Agency Pte. Ltd.
- 6.4.18 Amigoz Singapore Pte Ltd
- 6.4.19 Parsh Marine
- 6.4.20 Crystal Offshore Pte Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Future Market Outlook, 2026-2031
8 APPENDIX

 全球貨櫃市場
 裝卸輸送機市場規模、佔有率和成長分析:按輸送機類型、運作模式、應用、最終用戶產業、輸送機配置和地區分類-2026-2033年產業預測
 亞太地區拼箱貨運 (LCL):市場佔有率分析、產業趨勢和統計數據以及成長預測 (2026-2031)北美保溫運輸貨櫃:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)貨櫃航運:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 貨櫃短期租賃市場分析及預測(至2035年):按類型、產品、服務、技術、組件、應用、部署、最終用戶及解決方案分類
 2026-2034 年航運貨櫃市場規模、佔有率、成長、全球產業分析、區域趨勢和預測。
 ISO標準貨櫃市場:預測(至2034年)-按貨櫃類型、貨櫃尺寸、材料、所有權、應用、最終用戶和地區分類的全球分析海運貨櫃:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)歐洲沿海滾裝海運:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)