


 |
市場調查報告書
商品編碼
2124237
亞太地區車載資訊服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)APAC Telematics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,亞太地區車載資訊服務市場在 2025 年的價值為 187 億美元,預計到 2031 年將達到 327.9 億美元,而 2026 年為 205.4 億美元,預測期(2026-2031 年)的複合年成長率為 9.9.9.9.9.82%。
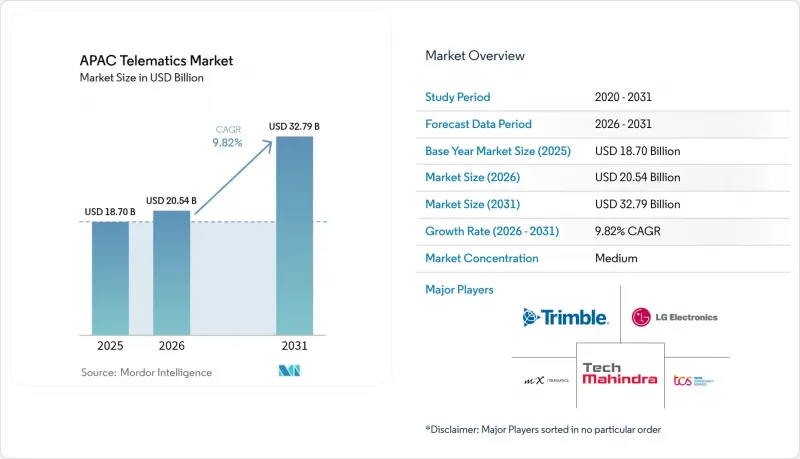
本報告按車輛類型(輕型商用車、中型和重型商用車)、通路(OEM整合、售後市場(有線)、售後市場OBD-II適配器)、服務類型(車輛和資產追蹤、導航和資訊娛樂、其他)、通訊技術(GNSS/GPS、蜂窩網路、其他)以及國家/地區進行細分。市場預測以美元計價。
亞太地區車載資訊服務市場的趨勢與洞察
OEM整合連接模組的普及
工廠預裝的車載資訊系統正日益成為新型商用車的標配,預計到2028年,搭載率將達到94%。中國製造商正與國內行動網路營運商合作,整合嵌入式SIM卡;而日本OEM廠商則採用Android Automotive作業系統,並提供雲端原生服務。這種轉變簡化了合規流程,實現了空中軟體更新,並支援預測性維護,從而減少了意外停機時間。同時,由於車隊營運商要求將車載資訊系統與車輛進行更深層次的整合,而這只有透過嵌入式硬體才能實現,售後市場供應商正面臨價格壓力。
AIS-140 和 eCall 的監管要求
印度運輸部根據AIS-140標準,強制要求所有商用車輛配備GPS追蹤系統和緊急按鈕,並計畫從2026年4月起將此項要求擴展至大型乘用車,包括緊急煞車和疲勞駕駛警告系統。日本和韓國已推出eCall系統,旨在提升統一的緊急應變能力。儘管這些進展使得平台供應商能夠全部區域擴展合規解決方案,但技術規格的差異仍需要模組化的軟體架構。
網路安全和資料隱私問題
車輛管理業者擔憂遠端駭客攻擊以及未授權存取位置資料和CAN總線資料。亞太地區多個國家的政府正在實施嚴格的資料本地化法規,並對違規行為處以罰款,導致合規預算增加。硬體供應商目前正在整合信任根(RoT)晶片,並與電信業者合作實施端對端加密。託管安全營運中心(MSOC)服務也正在興起,用於監控異常情況並協調快速修補更新。
細分市場分析
預計到2031年,中/重型商用車(M/HCV)的年複合成長率(CAGR)將達到10.41%,成長最快。但到2025年,輕型商用車(LCV)將佔據亞太地區車載資訊服務市場53.58%的佔有率。長途貨車的高平均單車收入得益於合規模組的應用,這些模組能夠減少成本高昂的路邊檢查,並提供先進的燃油分析和煞車磨損預測功能。同時,輕型商用車業者正優先考慮低成本的GPS追蹤技術,以確保貨物安全並提高都市區的配送效率。印度針對巴士和卡車引入高級駕駛輔助系統(ADAS)法規等監管舉措,進一步推動了車載資訊服務在中/重型商用車(M/HCV)中的應用。平台整合,正如 Platform Science 於 2025 年收購 Trimble 的車隊業務部門所表明的那樣,涵蓋 ELD(電子駕駛記錄儀)合規性和電池健康儀表板的整合解決方案將推動未來的成長。
在中重型商用車電氣化專案中,同步部署遠端資訊處理技術對於延長續航里程和最佳化充電時間至關重要。受電子商務服務等級協定 (SLA) 的約束,輕型商用車 (LCV) 車隊管理者正在部署基於攝影機的駕駛行為分析技術,以降低事故率。儘管輕型商用車仍佔據總部署量的大部分,但功能豐富的解決方案與訂閱式分析平台相結合,正將收入佔有率轉移到中重型商用車。因此,這些跨細分市場的互動正在塑造硬體原始設備製造商 (OEM) 和平台提供者差異化的打入市場策略。
到2025年,OEM嵌入式單元將維持41.89%的銷售佔有率,而售後市場OBD-II適配器的複合年成長率為10.02%。注重成本的車隊營運商優先考慮易於自行安裝以及能夠在不失去保固的情況下更換供應商。相較之下,嵌入式模組與車輛匯流排整合度更高,並支援無線韌體下載和原廠診斷功能。 OEM廠商正擴大開放API介面,以支援第三方軟體平台,從而縮小傳統上在柔軟性的差距,並推廣混合部署模式。
經認證的售後市場設備在改裝老舊車輛和使其符合印度AIS-140標準方面繼續發揮著至關重要的作用。有線黑盒子用於需要防篡改記錄和基於衛星的故障轉移的容錯移轉。雲端原生車載資訊服務供應商透過提供整合式儀表板來彌合通路差距,這些儀表板可以同時接收嵌入式和售後市場的資料流。隨著5G數據機在2026年後逐步標準化,供應商預計硬體更新週期將加快,而基於訂閱且資本投入極低的套餐有望促進小規模營運商的採用。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- OEM整合連接模組的普及
- AIS-140 和 eCall 的監管要求
- 對按里程計費保險(UBI)的需求不斷成長
- 電子商務最後一公里配送車輛增加
- 透過智慧城市智慧交通系統示範計畫促進數據互聯
- OEM-金融科技租賃模式與遠端資訊處理結合
- 市場限制因素
- 網路安全和資料隱私問題
- 初始硬體通訊成本相對較高。
- 互通性標準碎片化
- 2025年以後半導體供應鏈的波動性
- 價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對產業的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按車輛類型
- 輕型商用車(LCV)
- 中型/大型商用車(M/HCV)
- 通道特異性
- OEM嵌入式
- 售後市場(有線硬體)
- 售後 OBD-II 轉接器
- 按服務類型
- 車輛和資產追蹤
- 導航和資訊娛樂
- 遠距離診斷
- 安全(eCall、SVR)
- 保險遠端資訊處理(UBI/PAYD)
- 透過通訊技術
- GNSS/GPS
- 蜂窩通訊(2G/3G/4G/5G)
- 衛星通訊
- DSRC/C-V2X
- 國家
- 中國
- 日本
- 韓國
- 印度
- 澳洲和紐西蘭
- 東南亞(印尼、泰國、馬來西亞、新加坡、越南、菲律賓)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- LG Electronics Inc.
- Tata Consultancy Services Limited(TCS)
- MiX Telematics India Private Limited(Powerfleet)
- Trimble Inc.
- Tech Mahindra Limited
- Octo Telematics Ltd.
- Meitrack Group
- Concox(Shenzhen Jimi IoT Co., Ltd.)
- Arya Omnitalk Wireless Solutions Private Limited
- Asia Mobiliti Sdn. Bhd.
- Efkon India Private Limited
- Geotab Inc.
- CalAmp Corp.
- SinoTrack Group Limited
- Teltonika IoT Group
- Bosch Mobility Platform and Solutions India Private Limited
- Harman International Industries, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the APAC telematics market size was valued at USD 18.70 billion in 2025 and estimated to grow from USD 20.54 billion in 2026 to reach USD 32.79 billion by 2031, at a CAGR of 9.82% during the forecast period (2026-2031).
This report is Segmented by Vehicle Type (Light Commercial Vehicles, Medium and Heavy Commercial Vehicles), Channel (OEM-Embedded, Aftermarket Hard-Wired, Aftermarket OBD-II Dongle), Service Type (Fleet/Asset Tracking, Navigation and Infotainment, and More), Communication Technology (GNSS/GPS, Cellular, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
APAC Telematics Market Trends and Insights
Proliferation of OEM-installed connectivity modules
Factory-fitted telematics units are increasingly standard across new commercial vehicles as attach rates rise toward 94% by 2028. Chinese manufacturers collaborate with domestic mobile-network operators to integrate embedded SIMs, while Japanese OEMs layer Android Automotive OS to deliver cloud-native services. The shift simplifies regulatory compliance, enables over-the-air software updates, and supports predictive maintenance that cuts unplanned downtime. Aftermarket vendors face pricing pressure as fleets favor deeper vehicle-bus integration that only embedded hardware can provide.
Regulatory mandates on AIS-140 and eCall
India's transport ministry requires GPS tracking and panic buttons under AIS-140 for all commercial vehicles, and from April 2026, will extend emergency braking and drowsiness warnings to larger passenger vehicles. Japan and South Korea have rolled out eCall, driving uniform emergency-response capabilities. This convergence allows platform vendors to scale compliance solutions region-wide, though varying technical formats still demand modular software architectures.
Cyber-security and data-privacy concerns
Fleet operators worry about remote hacking and unauthorized access to location or CAN bus data. Several APAC governments enforce strict rules on data localization and impose penalties for breaches, raising compliance budgets. Hardware vendors now integrate root-of-trust chips and collaborate with telecom carriers to deploy end-to-end encryption. Managed security operations center services are also emerging to monitor anomalies and coordinate rapid patching .
Other drivers and restraints analyzed in the detailed report include:
- Rising demand for usage-based insurance (UBI)
- Growth of e-commerce last-mile fleets
- Semiconductor supply-chain volatility post-2025
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Medium and Heavy Commercial Vehicles account for the fastest expansion at 10.41% CAGR to 2031, whereas Light Commercial Vehicles held 53.58% of the APAC telematics market share in 2025. The higher average revenue per installed unit on long-haul trucks comes from advanced fuel analytics, brake-wear prediction, and compliance modules that reduce costly roadside inspections. Conversely, LCV operators prioritize low-cost GPS tracking to safeguard parcels and streamline urban drops. Regulatory momentum, such as India's incoming ADAS rules for buses and trucks, further lifts M/HCV penetration. Platform consolidation, evident in Platform Science's 2025 acquisition of Trimble's fleet unit, signals that integrated offerings spanning ELD compliance and battery-health dashboards will dominate future growth.
M/HCV electrification projects necessitate concurrent telematics deployment to extend driving range and optimize charging windows. LCV fleet managers, pressed by e-commerce service-level agreements, adopt camera-based driver-behavior analytics to cut accident rates. Although the overall installed-base majority remains within LCVs, revenue share tilts toward M/HCVs because of feature-rich solutions bundled with subscription analytics platforms. The segment interplay, therefore, shapes differentiated go-to-market strategies for hardware OEMs and platform providers.
OEM-embedded units retained 41.89% revenue share in 2025, yet Aftermarket OBD-II dongles are on pace for 10.02% CAGR. Cost-conscious fleets value the ease of self-installation and the ability to switch vendors without forfeiting warranties. In contrast, embedded modules offer deeper vehicle-bus integration that supports over-the-air firmware downloads and factory-grade diagnostics. OEMs increasingly open APIs to third-party software platforms, narrowing the historical gap in flexibility and encouraging hybrid deployment models.
Certified aftermarket devices remain pivotal for retrofitting older assets and meeting AIS-140 in India. Hard-wired black boxes serve fleets demanding tamper-proof records or satellite fallback. Cloud-native telematics vendors bridge the channel divide by delivering a unified dashboard that ingests both embedded and aftermarket data streams. As 5G modems become standard from 2026 onward, vendors expect hardware refresh cycles to accelerate, allowing capex-light subscription bundles to spur adoption among small operators.
Complete Report Scope:
- By Vehicle Type
- Light Commercial Vehicles (LCV)
- Medium and Heavy Commercial Vehicles (M/HCV)
- By Channel
- OEM-embedded
- Aftermarket Hard-wired
- Aftermarket OBD-II Dongle
- By Service Type
- Fleet/Asset Tracking
- Navigation and Infotainment
- Remote Diagnostics
- Safety and Security (eCall, SVR)
- Insurance Telematics (UBI/PAYD)
- By Communication Technology
- GNSS/GPS
- Cellular (2G/3G/4G/5G)
- Satellite-based
- DSRC/C-V2X
- By Country
- China
- Japan
- South Korea
- India
- Australia and New Zealand
- South-East Asia (Indonesia, Thailand, Malaysia, Singapore, Vietnam, Philippines)
List of Companies Covered in this Report:
- LG Electronics Inc.
- Tata Consultancy Services Limited (TCS)
- MiX Telematics India Private Limited (Powerfleet)
- Trimble Inc.
- Tech Mahindra Limited
- Octo Telematics Ltd.
- Meitrack Group
- Concox (Shenzhen Jimi IoT Co., Ltd.)
- Arya Omnitalk Wireless Solutions Private Limited
- Asia Mobiliti Sdn. Bhd.
- Efkon India Private Limited
- Geotab Inc.
- CalAmp Corp.
- SinoTrack Group Limited
- Teltonika IoT Group
- Bosch Mobility Platform and Solutions India Private Limited
- Harman International Industries, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of OEM-installed connectivity modules
- 4.2.2 Regulatory mandates on AIS-140 and eCall
- 4.2.3 Rising demand for usage-based insurance (UBI)
- 4.2.4 Growth of e-commerce last-mile fleets
- 4.2.5 Smart-city ITS pilots driving data partnerships
- 4.2.6 OEM-fintech leasing models bundling telematics
- 4.3 Market Restraints
- 4.3.1 Cyber-security and data-privacy concerns
- 4.3.2 High upfront hardware/communication cost
- 4.3.3 Fragmented interoperability standards
- 4.3.4 Semiconductor supply-chain volatility post-2025
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Industry
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Vehicle Type
- 5.1.1 Light Commercial Vehicles (LCV)
- 5.1.2 Medium and Heavy Commercial Vehicles (M/HCV)
- 5.2 By Channel
- 5.2.1 OEM-embedded
- 5.2.2 Aftermarket Hard-wired
- 5.2.3 Aftermarket OBD-II Dongle
- 5.3 By Service Type
- 5.3.1 Fleet/Asset Tracking
- 5.3.2 Navigation and Infotainment
- 5.3.3 Remote Diagnostics
- 5.3.4 Safety and Security (eCall, SVR)
- 5.3.5 Insurance Telematics (UBI/PAYD)
- 5.4 By Communication Technology
- 5.4.1 GNSS/GPS
- 5.4.2 Cellular (2G/3G/4G/5G)
- 5.4.3 Satellite-based
- 5.4.4 DSRC/C-V2X
- 5.5 By Country
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 South Korea
- 5.5.4 India
- 5.5.5 Australia and New Zealand
- 5.5.6 South-East Asia (Indonesia, Thailand, Malaysia, Singapore, Vietnam, Philippines)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 LG Electronics Inc.
- 6.4.2 Tata Consultancy Services Limited (TCS)
- 6.4.3 MiX Telematics India Private Limited (Powerfleet)
- 6.4.4 Trimble Inc.
- 6.4.5 Tech Mahindra Limited
- 6.4.6 Octo Telematics Ltd.
- 6.4.7 Meitrack Group
- 6.4.8 Concox (Shenzhen Jimi IoT Co., Ltd.)
- 6.4.9 Arya Omnitalk Wireless Solutions Private Limited
- 6.4.10 Asia Mobiliti Sdn. Bhd.
- 6.4.11 Efkon India Private Limited
- 6.4.12 Geotab Inc.
- 6.4.13 CalAmp Corp.
- 6.4.14 SinoTrack Group Limited
- 6.4.15 Teltonika IoT Group
- 6.4.16 Bosch Mobility Platform and Solutions India Private Limited
- 6.4.17 Harman International Industries, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 東南亞車載資訊服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026-2030年全球汽車售後市場遠端資訊處理市場
 全球車用通訊系統市場:按服務、車輛類型、外形尺寸、產品/服務、連接方式、車隊管理服務和地區分類-預測至2033年歐洲車用通訊系統:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)歐洲車載資訊服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)車用通訊系統系統:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 車載資訊服務市場 - 全球預測,2026-2032 年
 全球汽車遠端資訊處理市場(第11版)租賃車輛遠端資訊處理(第四版)
 車用通訊系統市場預測至2034年:按類型、產品、連接方式、動力方式、應用、最終用戶和地區分類的全球分析